


Could FI 02 Lens Win Alter The Investment Case For Nippon Electric Glass Stock?
- Nippon Electric Glass reported that its FI-02 chalcogenide IR Transmitting Glass has been adopted by Heimann Sensor for a thermal camera lens unit that offers a 120° × 68° field of view and supports press molding for volume manufacturing.
- The FI-02 material combines high infrared transmittance, high refractive index, low dispersion, and a composition free of arsenic and selenium, which directly targets performance, cost, and regulatory pressures in the infrared sensing market.
- This development illustrates how Nippon Electric Glass's investment narrative is influenced by FI-02's adoption in wide angle thermal lenses and broader infrared sensing applications.
Scan beyond Nippon Electric Glass and compare this infrared materials story with other specialty manufacturers in our hand picked list of solid balance sheet and fundamentals (22 results) for context on balance sheet strength and fundamentals.
What Is Nippon Electric Glass' Investment Narrative?
To own Nippon Electric Glass, you need to believe this is more than a cyclical glass supplier. The appeal is a specialist materials business that can turn niche products like FI-02 into repeat, higher value programs across infrared sensing, displays, semiconductors and industrial glass. The Heimann Sensor win points in that direction. It shows Nippon Electric Glass can meet tight optical specs and support volume production, which matters if you care about execution and not just headlines.
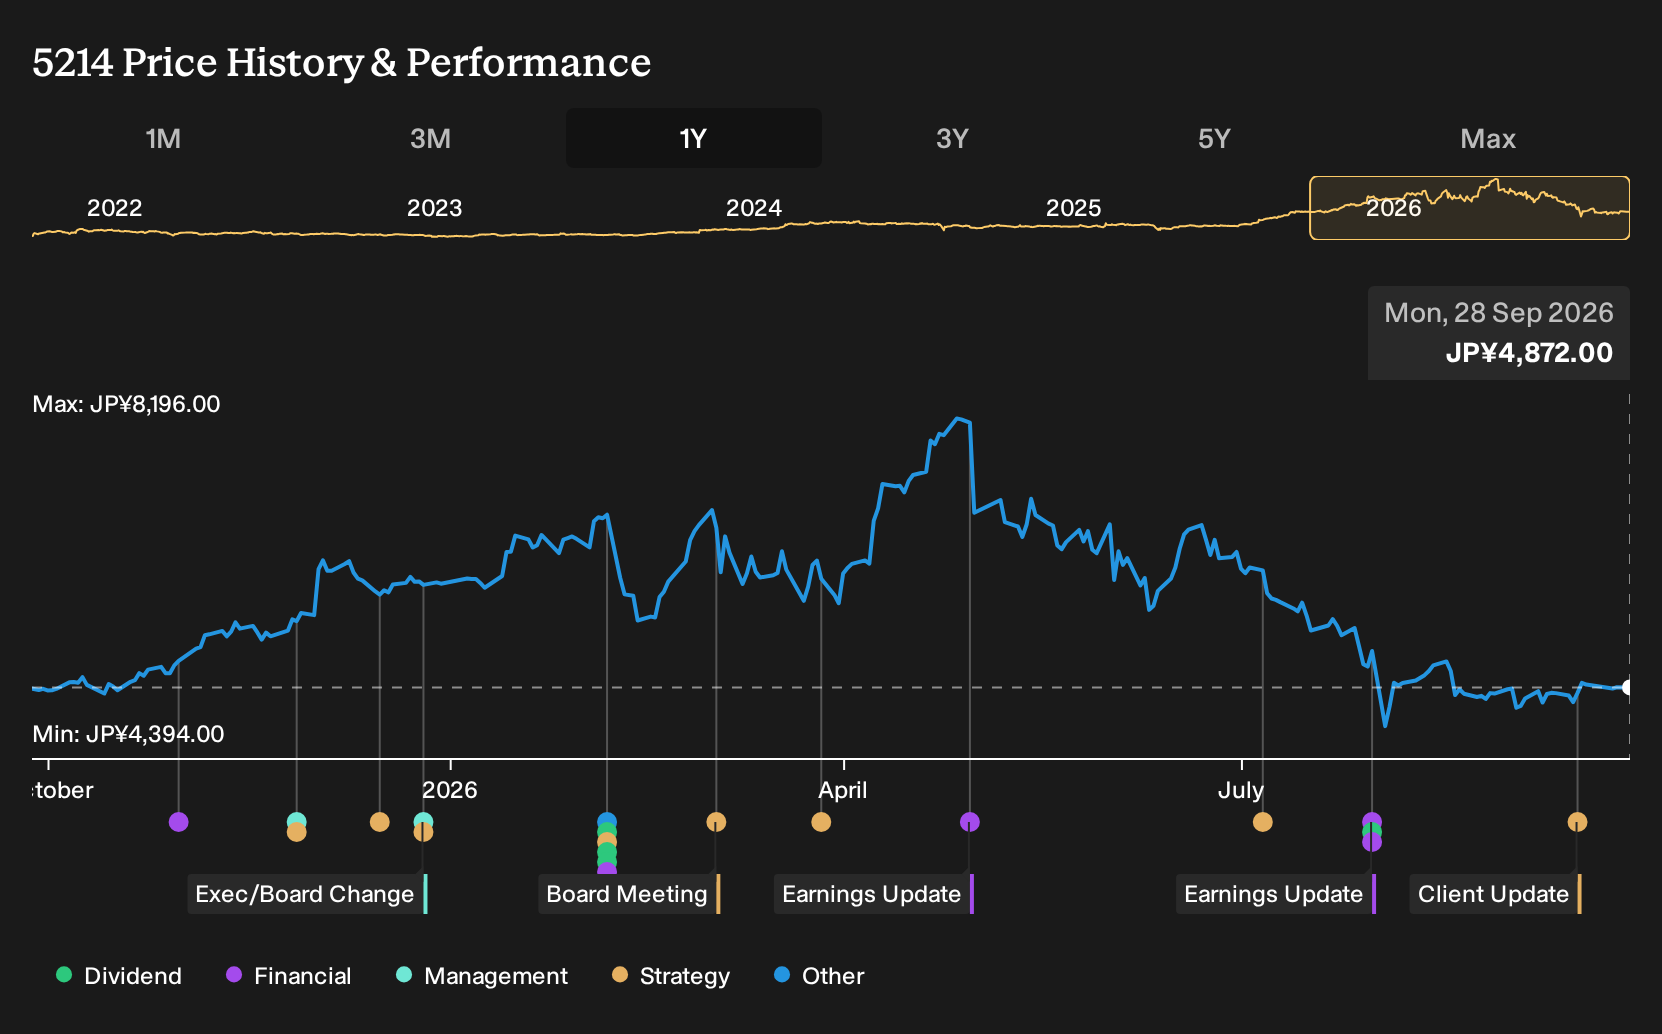
In the short term, the lens adoption is unlikely to transform revenue on its own, especially with the share price down around 26% over 90 days and returns lagging the broader JP market over 1 year. The more immediate levers remain consistent profitability, capital discipline in a capital intensive industry and proving that forecast earnings growth around the mid single digits is achievable. Pricing power in specialty glass, an unstable dividend history and a relatively low forecast return on equity still frame the risk side of the story.
Even so, there is one uncomfortable thread that runs through the Nippon Electric Glass story which only really comes into focus when you look at ...
There's only one way to know the right time to buy, sell or hold Nippon Electric Glass. Head to Simply Wall St's company report for the latest analysis of Nippon Electric Glass's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nippon Electric Glass research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nippon Electric Glass. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nippon Electric Glass' overall financial health at a glance.
Looking For More Investment Ideas Beyond Nippon Electric Glass?
If the FI-02 story has you thinking about where else strong fundamentals and clear use cases might show up, it can help to scan a broader universe of businesses before deciding where Nippon Electric Glass fits in your portfolio.
- For investors who want income that aims to be resilient, review companies in the 16 dividend fortresses that may offer higher yields with more robust balance sheets.
- If capital preservation and steadier risk profiles matter most to you, start with the 21 resilient stocks with low risk scores and see which stocks line up with that mindset.
- When you want to get ahead of the crowd and research potential future favourites, filter through the 74 high quality undiscovered gems to find lesser known businesses with stronger fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com