


3 Korean Dividend Stocks Worth Watching As Bond Yields Rise
When bond yields jump and headlines focus on pressure in equity markets, domestically focused Korean dividend and value stocks can quietly become the most interesting corner of the market. Higher rates punish stretched valuations, but they can also push attention toward companies backed by real cash flow and existing payouts. This article walks through three Korean stocks tied to this rate shock story, and shows where investors might see potential or risk.
The stocks covered in the list below are just a starting sample, since the full screen surfaced 19 more Korean dividend and value companies with equally compelling stories that are not detailed here. To go straight to the full universe of ideas, use the Korean Domestic-Oriented Dividend and Value Stocks screener to identify, analyze, and focus on the opportunities that best match your own conviction.
LG Uplus (KOSE:A032640)
Overview: LG Uplus is a Korean telecom operator that sells mobile, broadband, IPTV, and smart home connectivity and digital services nationwide.
Operations: LG Uplus generates about ₩14.4b from its LG U+ division and ₩1.1b from LG Hello Vision, with all ₩15.4b in revenue coming from South Korea.
Market Cap: ₩6.2t
LG Uplus fits this Korean dividend and value theme as a domestic subscription telecom player, where recurring connectivity and home services can matter more than market swings when bond yields spike.
"Investment in AI-powered platforms and security solutions (for example, anti-deepfake/voice, AI-driven contact centers, and participation in the national sovereign AI initiative) enhances product differentiation and operational efficiency, which can lower cost structures and help expand net margins over time."
What happens to those margins if one unseen pressure on how much cash can be returned to shareholders shifts direction?
If that pressure on cash returns is starting to shift, the full narrative for LG Uplus explains how LG Uplus could see those forces decouple from headline rate moves.

Korea Asset In Trust (KOSE:A123890)
Overview: Korea Asset In Trust is a Seoul based real estate trustee that structures, manages, and services income focused property and financing trusts.
Operations: Korea Asset In Trust generates approximately ₩210.6b in revenue from South Korean real estate related trust activities and associated services.
Market Cap: ₩296.7b
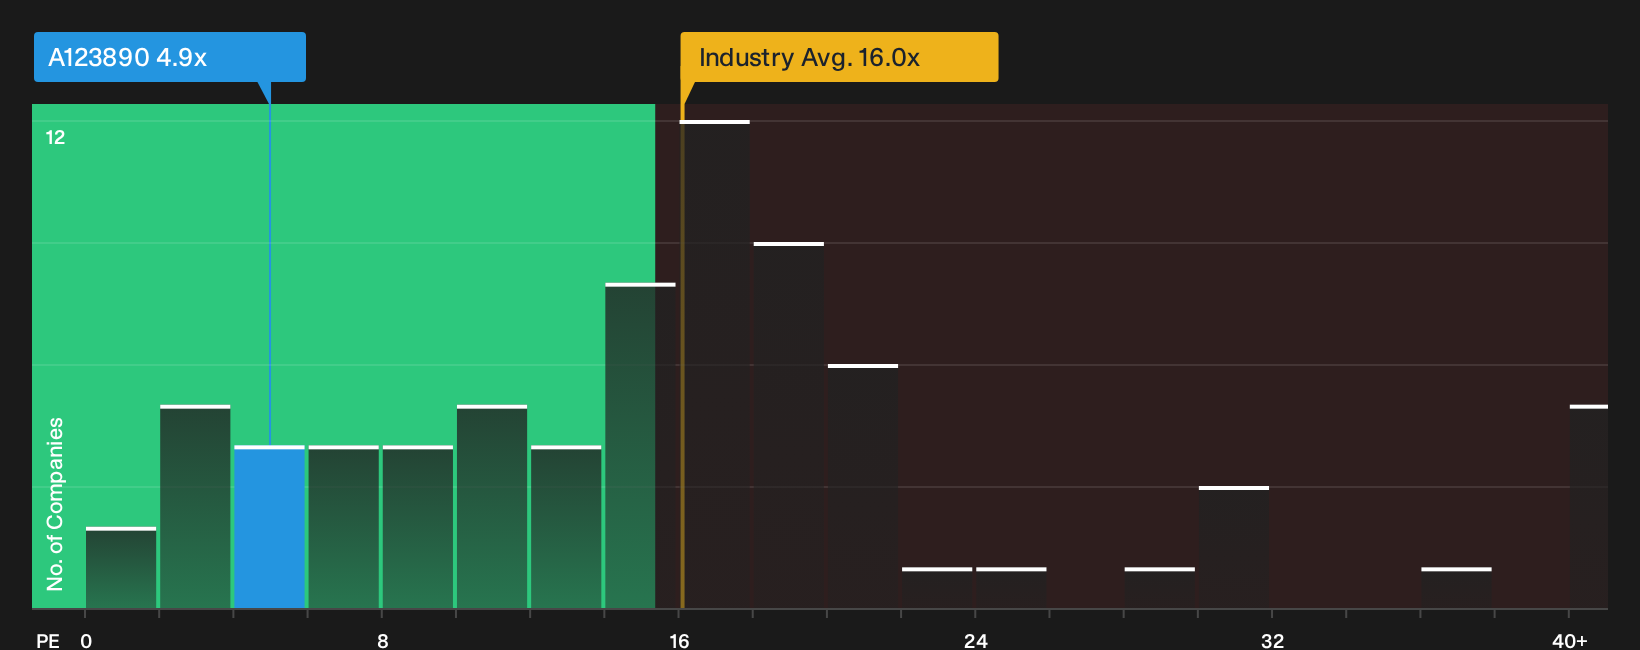
Korea Asset In Trust fits this domestic dividend and value screen as a Korea focused, REIT like trust business with cash flow anchored to local property assets and financing mandates. Investors looking for income exposure may find the combination of a low P/E and improved recent profitability noteworthy, while keeping in mind that there is an unresolved pressure on future payout capacity and funding costs.
That payout question is exactly why the 2 key rewards and 3 important warning signs (1 is major!) could help you see where Korea Asset In Trust’s income story might really be heading.
KT (KOSE:A030200)
Overview: KT runs Korea focused mobile, broadband, media, and platform services that anchor everyday connectivity and subscription spending across the country.
Operations: KT generates about ₩19.2b from ICT, ₩9.7b from other services, ₩3.3b from finance, and ₩0.9b from real estate, with almost all ₩27.4b in revenue earned in South Korea.
Market Cap: ₩12.5t
KT fits this Korean dividend and value theme as a domestically driven telecom and platform group. For income focused investors, recurring bills and data usage can matter more than short term swings in bond yields.
"KT's accelerated investment and leadership in secure 5G networks, combined with early-mover advantage in data center and confidential computing, position the company as the prime beneficiary of surging data consumption and AR/VR adoption in Korea. This could unlock exponential growth in telecom infrastructure, managed security services, and cloud revenues."
The real tension for KT is how one underappreciated shift in capital spending and cash returns ultimately feeds through to earnings power.
That cash return shift is exactly what the full narrative for KT sets out, showing how KT’s capital spend, payouts, and data growth could be quietly accelerating.

Seeking Fresh Alternatives Before They Fly
Markets can move quickly when momentum builds and quiet winners start breaking out. Fresh ideas are picked over quickly, and under the radar opportunities can drop off screens. Act now.
- Spot resilient payers early and track companies built to keep distributing income using the 159 dividend fortresses while the yields still make sense for your risk profile.
- Rotate into quality at a discount and sift through financially robust businesses with the 189 high quality undervalued stocks before the crowd starts chasing the same recovery story.
- Hunt for cash-generating AI leaders and review the 37 profitable AI stocks that aren't just burning cash while these operators remain under the radar and valuations still look grounded.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com