


Why Is SHO-BOND HoldingsLtd (TSE:1414) Getting Fresh Attention?
SHO-BOND HoldingsLtd (TSE:1414) was removed from the FTSE All-World Index (USD) on 19 September 2026. This change can influence index-tracking funds and overall trading liquidity for the stock.
For context, SHO-BOND HoldingsLtd is trading at ¥1,265.5, with the share price down 4.2% year to date but supported by a 1-year total shareholder return of 6.63% that reflects dividends in addition to modest price gains.
Scan beyond SHO-BOND HoldingsLtd and compare it with a hand picked list of solid balance sheet and fundamentals (22 results) to see how other repair and infrastructure focused businesses stack up on quality and resilience.
The FTSE exit put a spotlight on SHO-BOND HoldingsLtd. Is this price reset a comment on the long term repair business, or just a short term swing in sentiment that leaves valuation looking different to before?
Price-to-Earnings of 16.4x: Is it justified?
Valuation on SHO-BOND HoldingsLtd leans on a P/E of 16.4x at a share price of ¥1,265.5, which positions the stock at a richer tag than peers rather than a bargain.
The P/E ratio compares what investors are paying for each unit of current earnings, which matters a lot for a mature repair and reinforcement specialist where growth expectations are steady rather than rapid. For a business focused on maintaining roads, bridges, tunnels and other infrastructure, the multiple shows how the market weighs that relatively predictable earnings stream against other options in the Construction sector.
SWS data flags this directly. 1414 is described as expensive on a P/E of 16.4x against the Japan Construction industry on 11.2x, and also above a peer average of 13x. The same framework suggests a fair P/E closer to 11.5x, which is materially lower than where SHO-BOND HoldingsLtd trades today and indicates that the market is attaching a premium that could compress toward that fair level if sentiment cools.
Explore the SWS fair ratio for SHO-BOND HoldingsLtd.
Result: Price-to-Earnings of 16.4x (OVERVALUED)
Still, two things could unsettle the SHO-BOND HoldingsLtd story: weaker contract pipelines in domestic construction and any hit to infrastructure repair budgets in Japan.
Find out about the key risks to this SHO-BOND HoldingsLtd narrative.
Another view on SHO-BOND HoldingsLtd’s value
The P/E case paints SHO-BOND HoldingsLtd as expensive, yet the SWS DCF model points in a different direction. At ¥1,265.5, the share price sits about 4.4% below an estimated future cash flow value of ¥1,324.16. That gap is small. Does it hint at a modest cushion rather than pure overpricing?
Look into how the SWS DCF model arrives at its fair value.
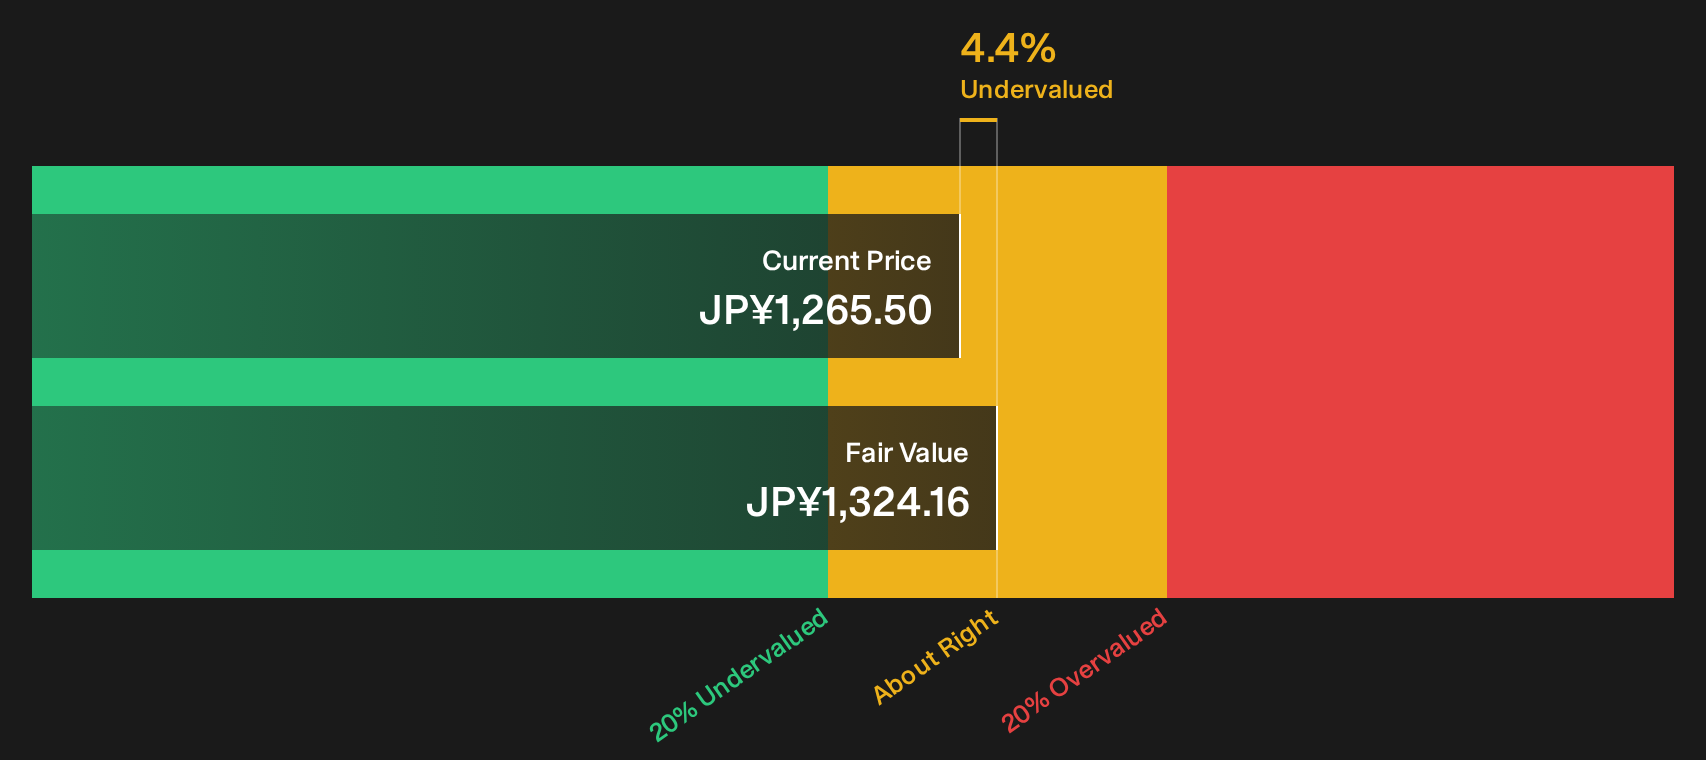
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SHO-BOND HoldingsLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around SHO-BOND HoldingsLtd may feel mixed, so consider reviewing the underlying numbers for yourself and see how they align with your expectations using the 4 key rewards.
Looking for more ideas beyond SHO-BOND HoldingsLtd?
If SHO-BOND HoldingsLtd has your attention, do not stop here. Use the Simply Wall St Screener to compare fresh ideas, spot new themes and keep your watchlist ahead of the crowd.
- Target potential mispricings by zeroing in on 19 high quality undervalued stocks that pair solid fundamentals with prices the market has not fully recognised yet.
- Strengthen your income stream by scanning 14 dividend fortresses that aim to combine higher yields with staying power through different market conditions.
- Prioritise resilience first and hunt for a 21 resilient stocks with low risk scores that could help anchor a more defensive corner of your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com