


3 Stocks Tied To Short Duration Bond ETFs As Cash Yields Stay High
Interest rates are back at levels last seen during the 2000s housing bubble, war in Iran is feeding inflation worries, and AI investment is soaking up capital. Cash no longer feels like an afterthought. It feels like a decision. Short-duration bond and ultra-short fixed-income ETFs now sit where fear and opportunity meet. This article walks through three stocks exposed to those forces and explains why they may matter for your portfolio.
The specific ETFs and funds covered next are just a small sample, and the full screen surfaced 23 more vehicles with equally compelling cash-style stories that are not unpacked in this article. To size up that broader universe quickly, identify your preferred risk profile, and analyze yield trade-offs in one focused view, head straight to the Short-Duration Bond and Ultra-Short Fixed-Income ETFs screener.
Federated Hermes (FHI)
Federated Hermes is one of the clearest plays on the short-duration and cash-style theme. It runs money market and ultra-short fixed income portfolios that sit at the point where higher short-term yields meet investors’ search for liquidity-focused income.
Federated Hermes manages US$1.9b from its Investment Management Business, mainly through funds and portfolios spanning equities, bonds and money markets, and has a market value of about US$4.1b.
"Growth in money market fund assets, supported by increasing institutional and retail demand for safety and attractive yields within a volatile, low-to-moderate interest rate environment, positions Federated Hermes' money market franchise for sustained asset and revenue gains."
The real test is how one quiet shift in client behavior toward cash-style ETFs versus deposits or direct T-bill buying ultimately plays out.
That slow drift into cash-style ETFs is exactly what the full narrative for Federated Hermes unpacks. It surfaces how shifting flows, fees and product mix could be quietly reshaping Federated Hermes.

Fiducian Group (ASX:FID)
Fiducian Group plugs into the short-duration and cash-style theme through its conservative fund range and advice platforms. These often steer everyday investors toward cash, income and short-maturity fixed interest options when rates and inflation worries start to bite.
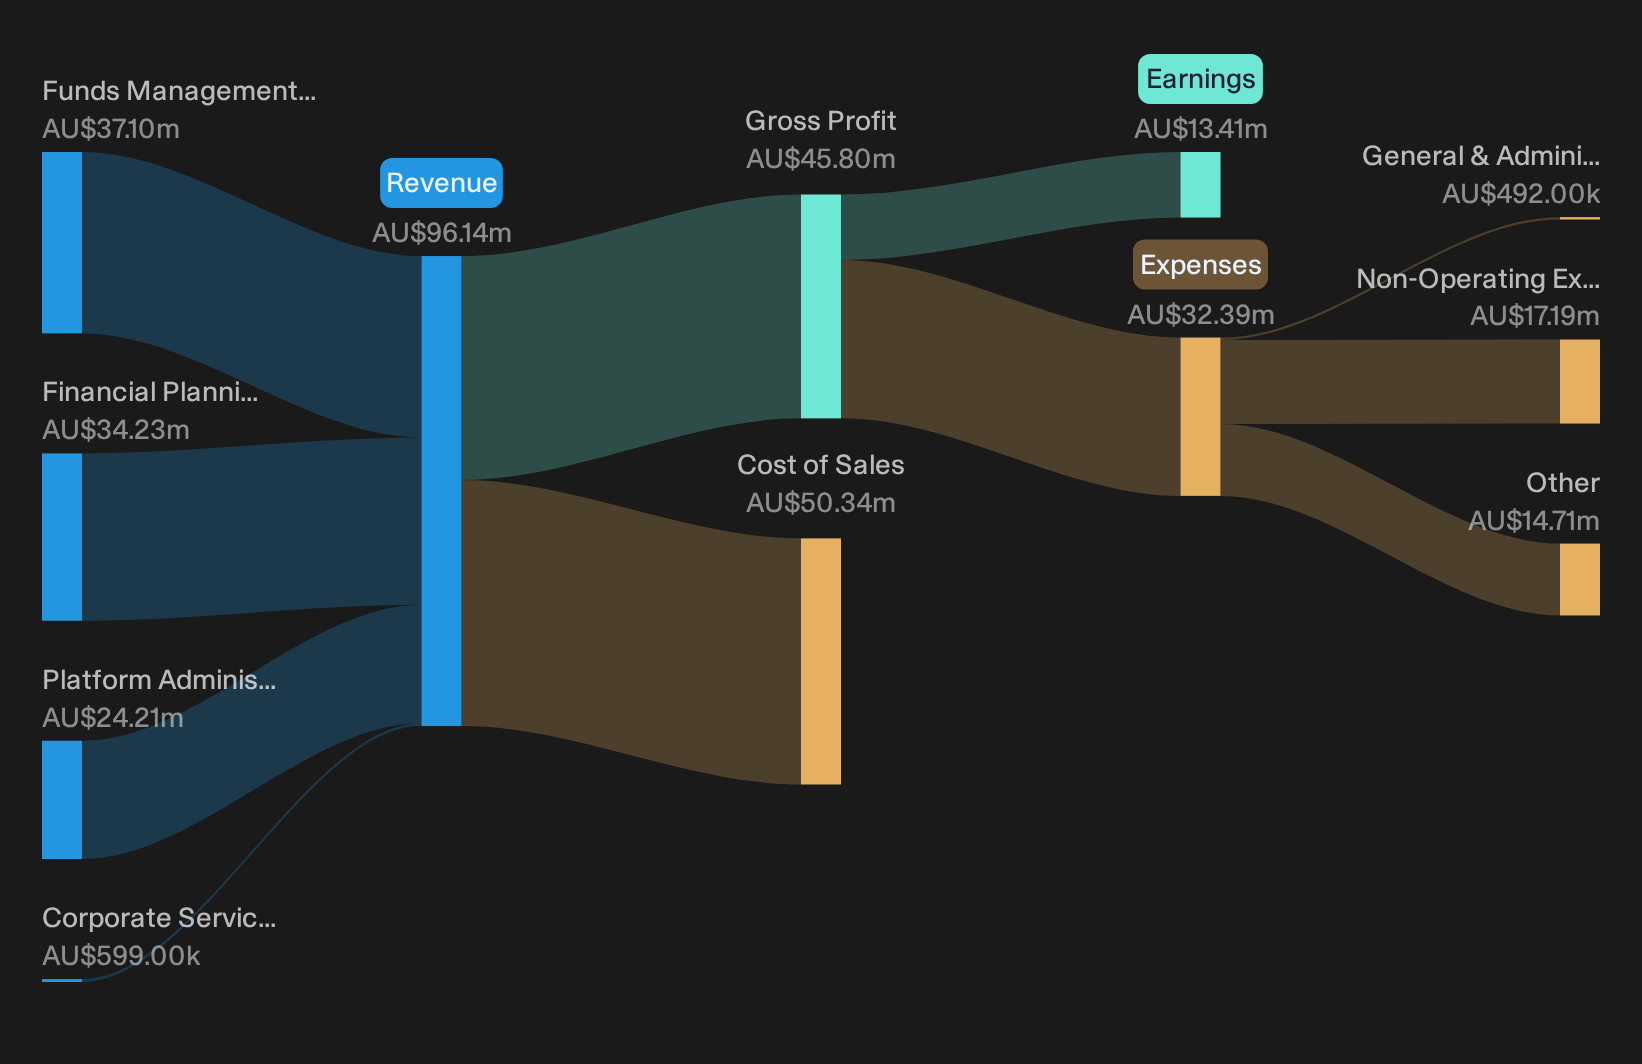
Fiducian Group generates A$37 million from funds management, A$34 million from financial planning, A$24 million from platform administration and A$1 million from corporate services. This provides a diversified A$96 million revenue base, and the stock is valued at about A$274 million.
For a business built around steady advice, platforms and conservative income products, the real interest is how Fiducian Group handles operational challenges while keeping cash-style investors comfortable.
"If ASIC’s claims are accurate, Fiducian may need to invest time and capital into strengthening data governance and compliance systems."
What happens to growth ambitions and profit margins if a single unseen pressure on trust and client inflows starts to bite harder?
If that pressure on trust grows, the full narrative for Fiducian Group shows where Fiducian Group’s advice engine could still accelerate client inflows and reshape its earnings mix.
Perpetual (ASX:PPT)
Perpetual plugs into the short-duration bond and cash-style theme through its fixed interest and cash funds. It also runs a broad mix of multi-asset and trustee services that link fee revenue to how clients position portfolios when rates stay higher for longer.
Perpetual Limited is a Sydney-based investment manager offering funds, advice and trustee services, with A$890 million from Asset Management and A$220 million from Corporate segments, supported by A$39 million from Group Support, and a market value of about A$1.9b.
"The proceeds are expected to be used primarily to repay debt, with net debt expected to fall to approximately 0.2 times EBITDA following completion."
What happens to Perpetual’s margins and product mix if a single shift in investor appetite for short-duration income products gathers pace from here?
If that shift accelerates, the full narrative for Perpetual shows how Perpetual’s debt reset, fee mix and cash-style exposure could be quietly reshaping earnings power.

Curious About Alternative Opportunities?
Fresh ideas move first, then everyone else chases the breakout. Scan under the radar for now, before momentum gets fully priced in, and get in early.
- Spot sturdier balance sheets before the crowd by scanning the list of solid balance sheet and fundamentals (24 results), which highlights companies built to handle shocks while others are still reacting.
- Target cash-generative AI plays that are not just story stocks by reviewing the 37 profitable AI stocks that aren't just burning cash, curated to focus on real earnings and disciplined spending.
- Position ahead of potential changes in the metals cycle by checking the curated 36 best rare earth metal stocks, focused on producers tied to long-term demand for critical materials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com