


Umios (TSE:1333), What Is Driving Fresh Attention Now?
Umios (TSE:1333) recently completed a corporate rebrand from Maruha Nichiro Corporation to its new identity, giving investors a fresh label on a long-established seafood and food processing business in Tokyo.
Recent trading tells a quieter story than the rebrand. Umios shares are around ¥1,291, with a year-to-date share price return that is slightly lower and a 1-year total shareholder return of 13.57% that suggests momentum built over a longer period.
Spot opportunities around Umios by scanning a hand picked 74 high quality undiscovered gems with strong fundamentals that are still flying under most investors' radar.Umios has a fresh brand and a ¥1,291 share price; however, its intrinsic value estimate points to a slight premium rather than a bargain. Does that gap reflect quality or overenthusiasm around the rebrand?
Price-to-Earnings of 10.1x: Is it justified?
Umios trades on a P/E of 10.1x, which sits below both the wider Japanese market and food peers, even though the share price is around ¥1,291 and our intrinsic value estimate screens as a small premium.
The P/E ratio compares the current share price to earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a diversified food and seafood group like Umios, this is often the headline yardstick because earnings capture the mix of fishing, farming, processing, and trading income in one number.
Profit trends complicate the picture. Earnings have grown by 9.2% per year over the past 5 years, yet profits declined 17.7% over the last year and net profit margins slipped from 2.1% to 1.7%. On top of that, the latest 12 month results include a sizeable one off gain of ¥8.4b, so part of the earnings that feed into the P/E and the discounted cash flow estimate reflects items outside day to day operations.
Compared to the JP Food industry average P/E of 16.8x and a peer average of 13.5x, the 10.1x multiple is materially lower. The market is assigning Umios a cheaper earnings tag than both the sector and its direct comparables, even though the SWS DCF model estimate of future cash flow value sits at ¥383.99 per share while the stock trades at ¥1,291, pointing to a rich price relative to that specific cash flow model.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 10.1x (OVERVALUED)
Still, the one off ¥8.4b gain and recent profit decline mean Umios earnings quality could be tested if trading conditions or consumer demand weaken.
Find out about the key risks to this Umios narrative.
Another View on Umios using the SWS DCF model
The SWS DCF model offers a very different read on Umios. It puts future cash flow value near ¥383.99 per share, which is far below the current ¥1,291 trading level. That gap points to a rich price on this metric and leaves investors asking which signal to trust.
Look into how the SWS DCF model arrives at its fair value.
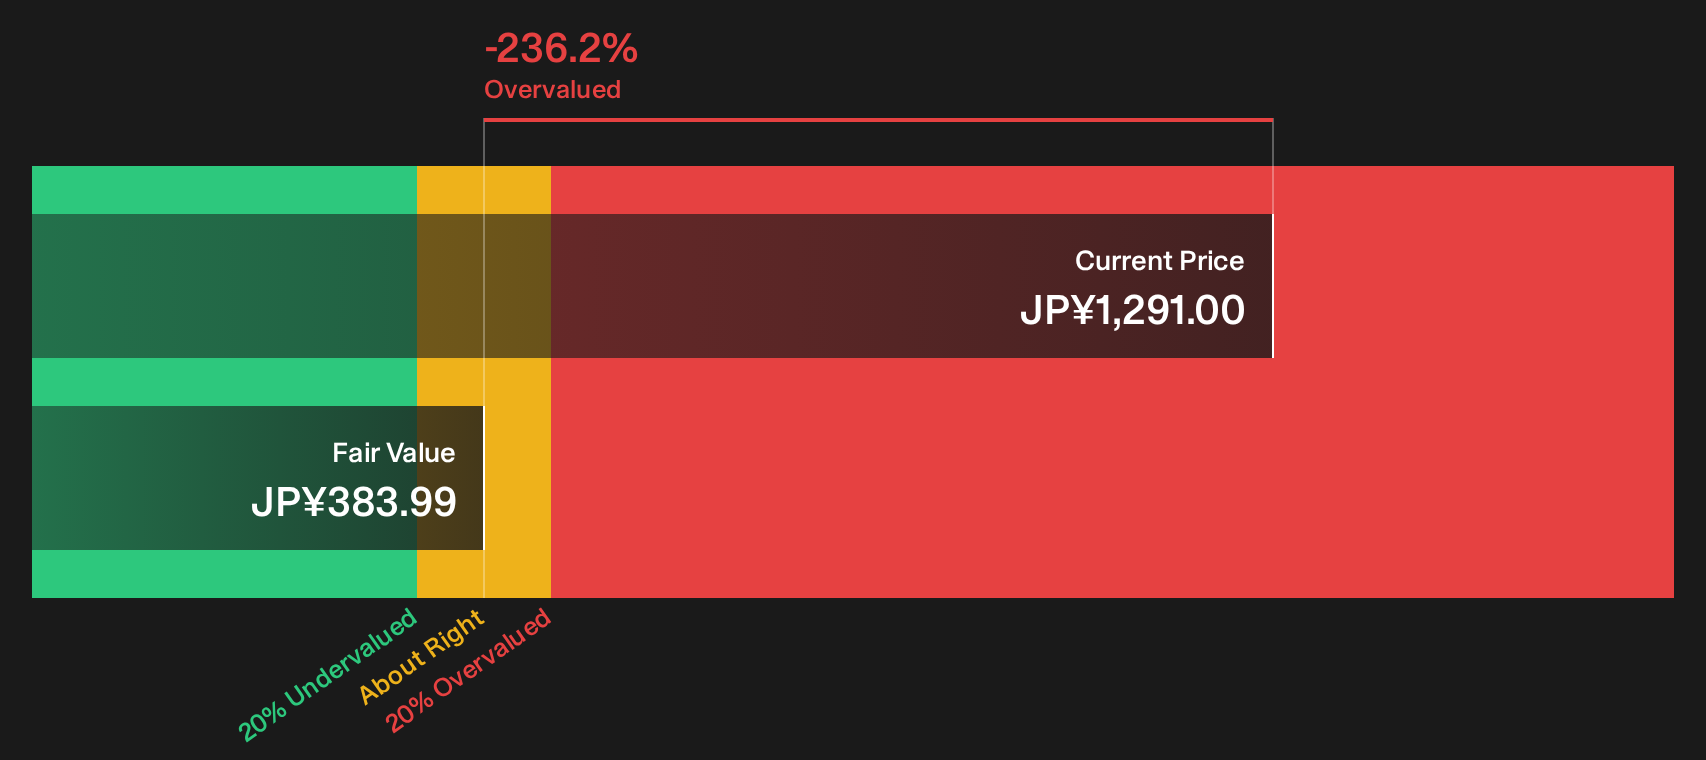
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Umios for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Umios so far. If that leaves you on the fence, review the underlying numbers and weigh the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Umios?
Do not stop with Umios. Broaden your watchlist with a few focused stock ideas that match different risk levels and return profiles.
- Target resilient opportunities by scanning a 21 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles and fewer balance sheet surprises.
- Hunt for value by using a 19 high quality undervalued stocks that filters for companies where quality fundamentals and pricing appear out of sync.
- Strengthen your income angle by reviewing a 14 dividend fortresses designed to highlight higher yield payers that still show solid financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com