


Tower Semiconductor Stock In Focus After Index Addition And AI Optics Shipments
- Tower Semiconductor was recently added to the PHLX Semiconductor Sector Index and, together with NewPhotonics, reported high volume shipments of silicon photonics optical engines for AI-oriented data infrastructure.
- The collaboration with NewPhotonics highlights Tower Semiconductor's focus on high-bandwidth, energy efficient photonic integrated circuits that target AI datacenters, near packaged optics, and other demanding connectivity workloads.
- This article examines how Tower Semiconductor's investment narrative aligns with its index inclusion and its silicon photonics activity for AI infrastructure.
Tower Semiconductor Investment Narrative Recap
To own Tower Semiconductor, you need to believe its specialty foundry focus on silicon photonics and SiGe can keep attracting AI, data center, and connectivity customers as capacity ramps. Index inclusion helps liquidity and visibility, but does not change the basic execution test. The short term catalyst still sits in how efficiently the company fills committed capacity and maintains pricing on higher value platforms.
The main near term risk remains the heavy CapEx program of more than US$1.15b through 2026 if demand or customer commitments soften. Customer concentration and geopolitical exposure add another layer of uncertainty. Recent AI optics news validates current positioning but does not remove the utilization or competitive risks already present.
The NewPhotonics high volume shipment announcement is the clearest operational tie in to the AI optics story. It shows Tower Semiconductor’s PH18DA silicon photonics platform is in volume use for 800G to 1.6T optical engines, with a roadmap toward 6.4T NPO solutions planned for volume shipment starting in the first half of 2027. That speaks directly to Tower’s aim to support higher bandwidth AI infrastructure.
For you as an investor, the practical question is whether these photonics programs scale fast enough to support the CapEx and sustain margins while competition in specialty nodes increases. Execution on the 6.4T roadmap, customer stickiness in NPO and pluggable optics, and any updates around ECOC 2026 will likely act as reference points for how real those catalysts look against the existing risk list.
Tower Semiconductor’s consensus narrative points to revenues of US$4.1b and earnings of US$1.3b by 2029. This outlook is built on analysts’ assumption of 33.5% yearly top line growth and an earnings step up of roughly US$1.0b from US$289.6m today.
Uncover why Tower Semiconductor's fair value indicates a 36% potential upside to its current price, which could narrow quickly.
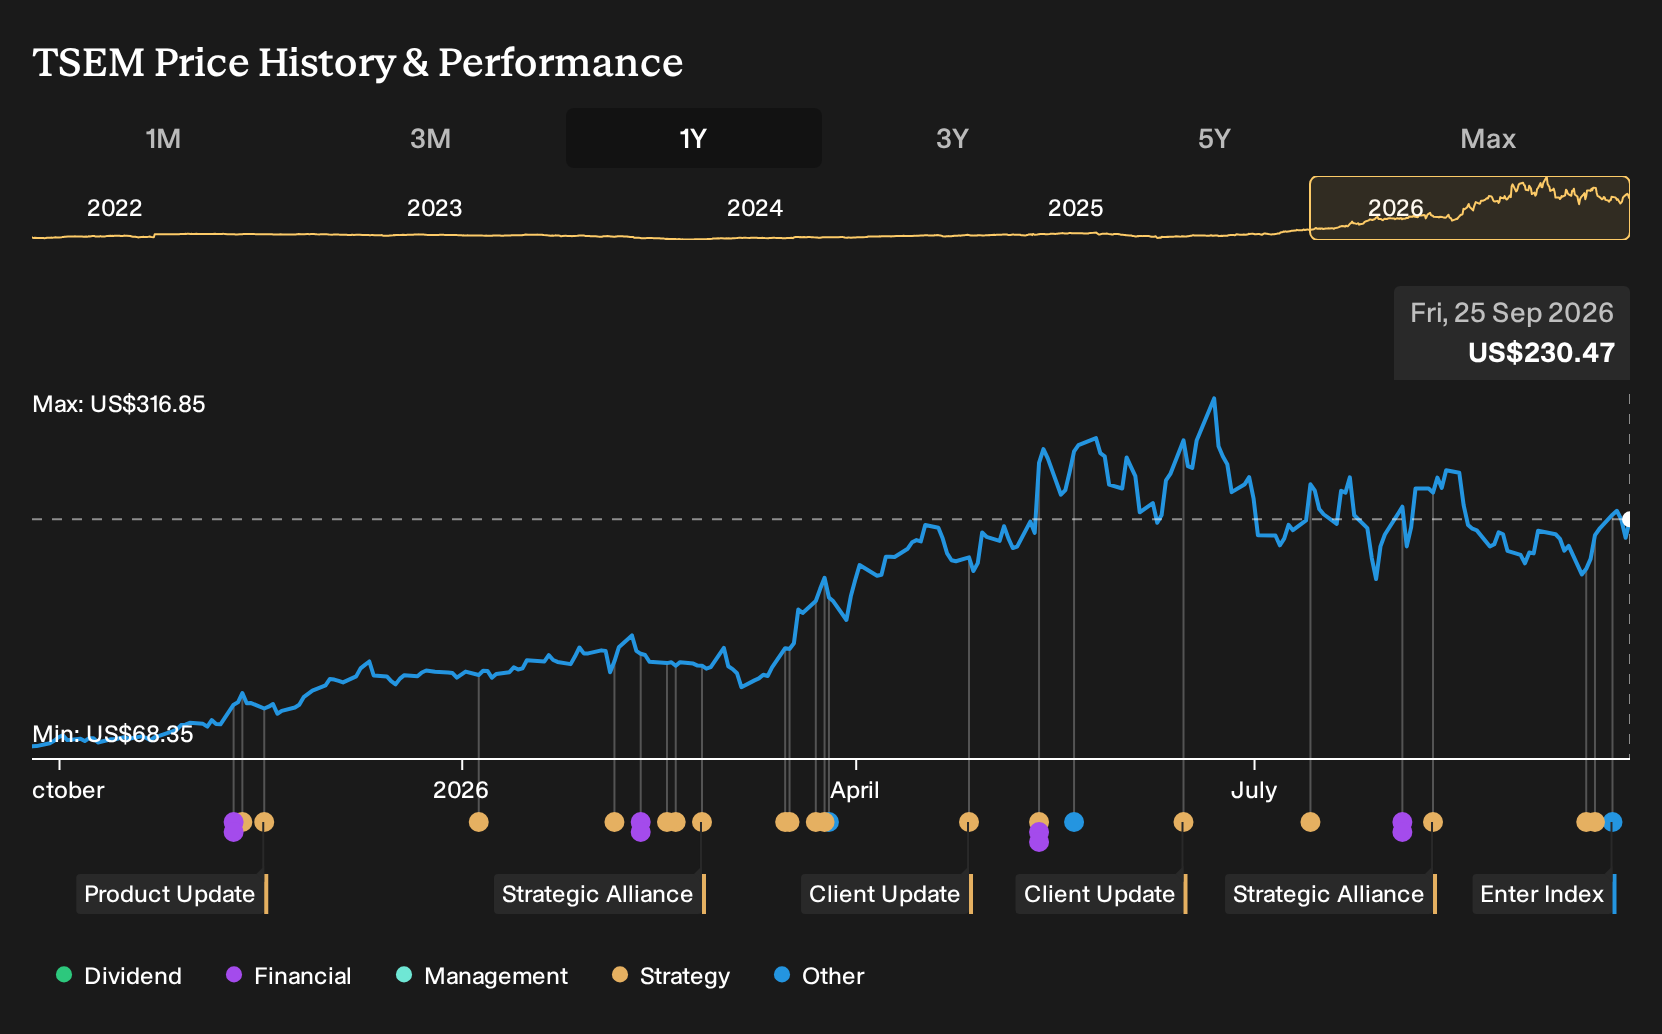
Exploring Other Perspectives
Some of the most optimistic analysts focus on Tower Semiconductor’s silicon photonics capacity reservations as a possible game changer. Before this index add and NewPhotonics shipment news, the bullish camp was already modeling about US$4.2b of revenue and US$1.4b of earnings by 2029. That is far above the lower US$986.7m earnings view, which shows just how wide the opinion spread is and why these headlines could prompt analysts to revisit both ends of the range.
Explore 3 other Tower Semiconductor fair value estimates, including one that suggests as much as 36% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so go with your instincts.
- A great starting point for your Tower Semiconductor research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tower Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tower Semiconductor's overall financial health at a glance.
Looking for more investment ideas beyond Tower Semiconductor?
If Tower Semiconductor's AI optics story has your attention, it can help to widen the lens and compare it with other businesses that share traits you care about, whether that is value, resilience, or balance sheet strength.
- For investors who want quality at a reasonable entry point, scan a curated set of 32 high quality undervalued stocks that may offer a more attractive risk reward profile than the broader market.
- If capital preservation and steadier profiles matter most to you, review a focused group of 30 resilient stocks with low risk scores that score well on stability, volatility, and financial robustness.
- When you care about financial resilience first, use the screener to zero in on a list of solid balance sheet and fundamentals (24 results) and compare their debt levels, liquidity, and asset backing against Tower Semiconductor.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com