


Independent Bank (INDB) Following Its Dividend Declaration Is Valuation Still Compelling
Independent Bank (INDB) drew fresh attention after its board declared a US$0.64 per share dividend, payable on October 9, 2026, to shareholders of record on September 28, 2026.
Independent Bank shares changed hands at US$81.20 on the latest close, with the stock posting a 1-day share price return of 1.20% but easing over the past month and quarter. A 10.94% year to date share price return and 18.15% 1-year total shareholder return suggest momentum has been more supportive over a longer stretch.
Scan the wider banking space for dividend payers and balance-sheet strength similar to Independent Bank using our hand picked list of solid balance sheet and fundamentals (24 results) as a starting universe.
Independent Bank has already rewarded patient holders, yet the recent dividend news and solid trailing returns raise a fresh question. Is most of the share price upside already booked, or does valuation still leave room ahead?
Most Popular Narrative: 10.3% Undervalued
On the most followed view of Independent Bank, a fair value of $90.57 sits above the recent $81.20 close. This puts the focus squarely on how the business can turn today’s earnings base into that higher valuation over time.
Rapid integration of the Enterprise Bank acquisition, with targeted cost synergies (~30% of expense base) expected in 2026 and a larger, more diversified deposit/loan base, offers scale benefit and cross-sell opportunities, enhancing net interest income and noninterest revenue growth potential.
See why 6 investors see Independent Bank as 10% undervalued.
Result: Fair Value of $90.57 (UNDERVALUED)
Still, Independent Bank faces meaningful pressure from its commercial real estate exposure, as well as the execution risk around integrating Enterprise Bank and completing the 2026 core technology migration.
Find out about the key risks to this Independent Bank narrative.
Another View On Independent Bank’s Valuation
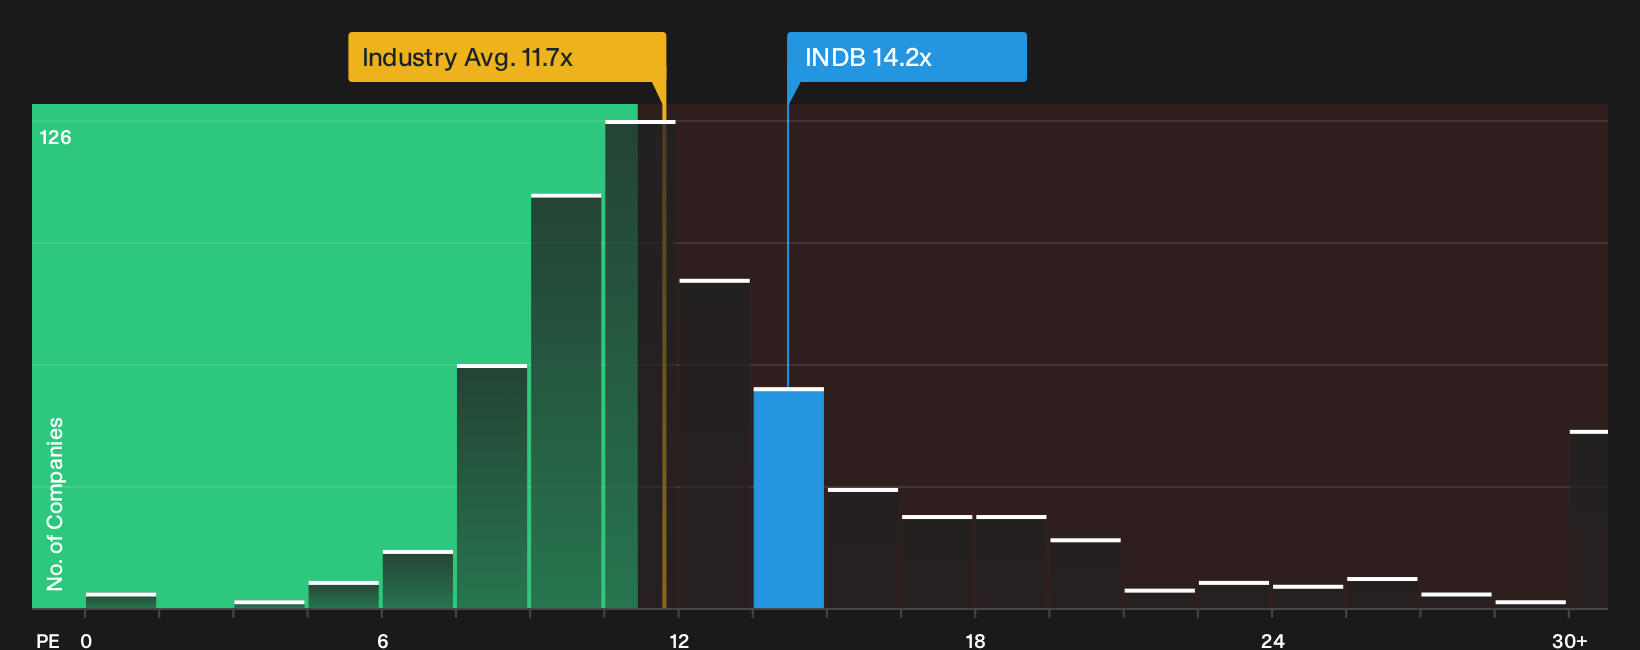
A second lens tells a different story. Independent Bank trades on a P/E of 14.2x, which is higher than both the US Banks industry at 11.7x and its peer average of 12.5x, and even slightly above its own fair ratio of 14.1x. That premium suggests less room for error if growth or credit trends disappoint, so how comfortable are you paying up for that analyst narrative?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Independent Bank’s valuation and risks so far. Act while the details are fresh in mind and weigh both sides with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Independent Bank?
Independent Bank gives you one angle on the market, but you will miss plenty of opportunities if you stop your research with a single ticker.
- Target fresh upside potential by scanning for mispriced businesses that combine quality fundamentals with attractive entry points using the 32 high quality undervalued stocks.
- Prioritise resilience by focusing on companies with stronger financial footing and cleaner leverage profiles through the 30 resilient stocks with low risk scores.
- Spot potential future market leaders early by filtering for underfollowed companies with solid metrics using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com