


How Investors May Respond To Ducommun (DCO) $35 Million PAC 3 Contract
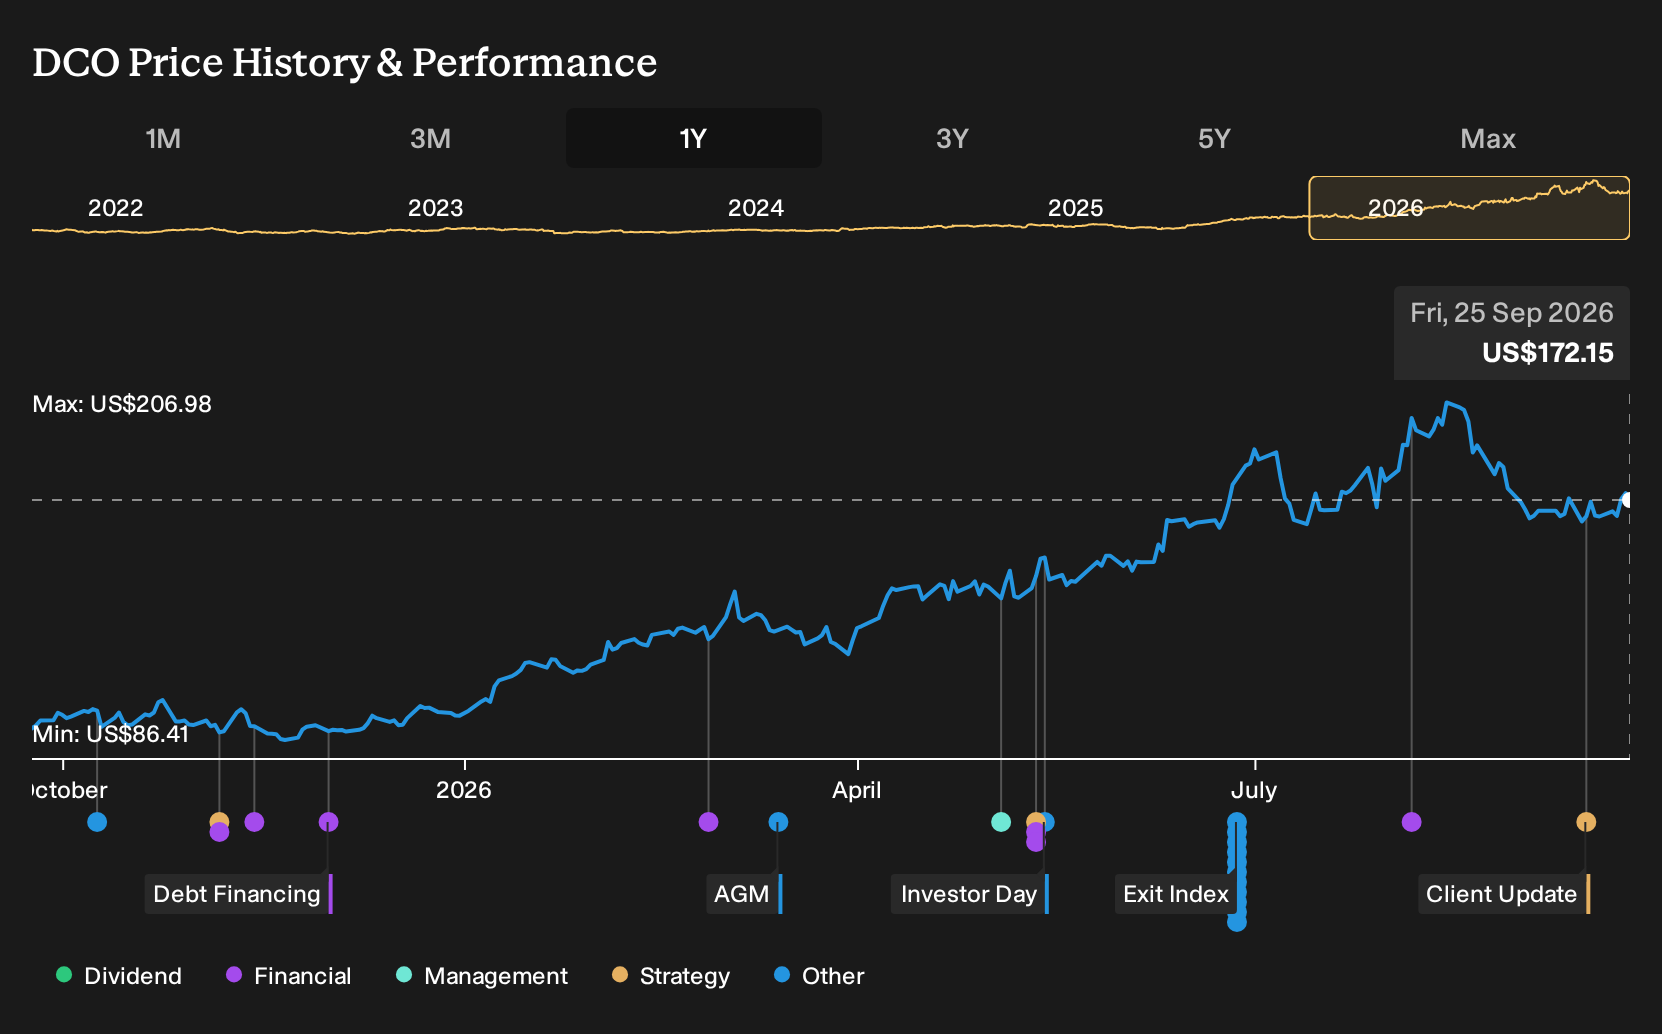
- Ducommun announced that it secured an agreement worth over US$35 million from Simmonds Precision Products Inc. to supply electronic assemblies for Lockheed Martin’s PAC-3 missile family, with production at its Tulsa, Oklahoma performance center.
- This PAC-3 award expands Ducommun’s content on a key missile platform and adds multi-year workload to a focused engineering and manufacturing site that already supports defense electronics.
- We will now see how Ducommun's investment narrative could be influenced by this new US$35 million PAC-3 electronics award.
Scan how Ducommun’s PAC-3 win compares with peers by lining it up against 40 power grid technology and infrastructure stocks targeting the defense and infrastructure backbone behind modern missile and aerospace systems.
Ducommun Investment Narrative Recap
To own Ducommun, you need to be comfortable with a story built on defense exposure, a recovery thesis in commercial aerospace, and ongoing margin work through mix and efficiency. The PAC-3 win reinforces the defense electronics side of that equation. It supports the idea that Ducommun can keep building content on key missile platforms, but it does not change the overall thesis on its own.
The near term hinge point remains execution on facility consolidations and production transitions while the business is still unprofitable and Return on Equity is weak. The biggest risk is operational hiccups or a shift in U.S. defense priorities that hits missile and radar programs, especially as defense becomes a larger share of the revenue base.
The PAC-3 award lines up cleanly with earlier commentary about elevated global defense spending and a 30% increase in missile backlog. That backdrop had already been flagged as a key driver for Ducommun, with rising program content and order activity seen as core to the story. This new electronics workload fits into that same missile and radar replenishment theme.
For you as a shareholder, the key thread to watch is whether contracts like PAC-3 help Ducommun move further toward its higher margin engineered products mix and support the longer term plan for better cash conversion. The operational flip side is concentration risk. A heavier tilt into missile programs can amplify the impact of any change in defense budgets or platform focus on both revenue and earnings volatility.
What The PAC-3 Award Means Against Ducommun’s Forecasts
Ducommun's narrative projects US$1.1b revenue and US$146.1m earnings by 2029. That path assumes revenue increases at 8.4% per year and earnings improve by about US$167m from a current loss of US$21.2m to the 2029 consensus level.
Discover how Ducommun's fair value indicates a 23% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts look at Ducommun’s growing missile exposure as a potential accelerator rather than a concentration risk. Before this PAC-3 news, they were already modeling about US$1.1b of revenue and US$142.6m of earnings by 2029. You can read this as a reminder that views can differ sharply and may shift again as new contracts surface.
Explore another Ducommun fair value estimate, including one that suggests as much as 23% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ducommun research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Ducommun. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ducommun's overall financial health at a glance.
Looking For More Ideas Beyond Ducommun?
If you like the Ducommun story but want to widen your watchlist, the Simply Wall St screener can help you quickly surface other stocks that fit your style and risk tolerance.
- If you are hunting for value with quality at the core, check out a curated set of companies through the 32 high quality undervalued stocks that might line up with your return and risk goals.
- For investors who care more about resilience than excitement, filter for stability and balance sheet strength using the 30 resilient stocks with low risk scores that can help you focus on businesses with lower assessed risk profiles.
- When you want to spot potential early-stage opportunities with solid underlying fundamentals, scan the 16 high quality undiscovered gems and see which lesser known stocks deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com