


Vail Resorts (MTN) Is Drawing Fresh Attention, What Are Investors Weighing?
Vail Resorts (MTN) moved into the spotlight after Oasis Management nominated four directors to its board, pushing for changes in governance, operations, and how the resort portfolio supports long term shareholder value.
That activism push comes after a patchy run for Vail Resorts, with the share price down over the past month and year but only slightly positive on a year to date basis. Multi year total shareholder returns have been considerably weaker, pointing to fading momentum that helps explain why governance and execution are now under scrutiny.
Scan how Vail Resorts stacks up against other travel and leisure plays facing their own turning points by checking our hand picked 16 high quality undiscovered gems.
With Vail Resorts trading near US$136 after a weak multi year return profile and an activist challenge now public, do you lean into the reset today, or wait for a clearer entry once the valuation work is done?
Most Popular Narrative: 8% Undervalued
Against a last close of $136.11, the most followed narrative pins Vail Resorts' fair value at $148.50, pointing to a modest valuation gap that active investors now have to weigh against weather risk, leverage and governance pressure.
Vail Resorts is on track to deliver $100 million in annualized cost efficiencies by the end of fiscal year 2026 through its Resource Efficiency Transformation Plan. This could positively impact earnings by improving net margins. Continued investment in guest experience through lift, terrain, and food and beverage expansions, along with technology upgrades like My Epic App and AI capabilities, are expected to support higher ancillary revenue and overall customer satisfaction, contributing positively to revenue growth.
See why 9 investors see Vail Resorts as 8% undervalued.
Result: Fair Value of $148.50 (UNDERVALUED)
Still, weather driven drops in skier visits and softer early pass sales sit uncomfortably alongside higher pricing assumptions. These assumptions underpin the Vail Resorts upside story.
Find out about the key risks to this Vail Resorts narrative.
Another View: Vail Resorts On Earnings Multiples
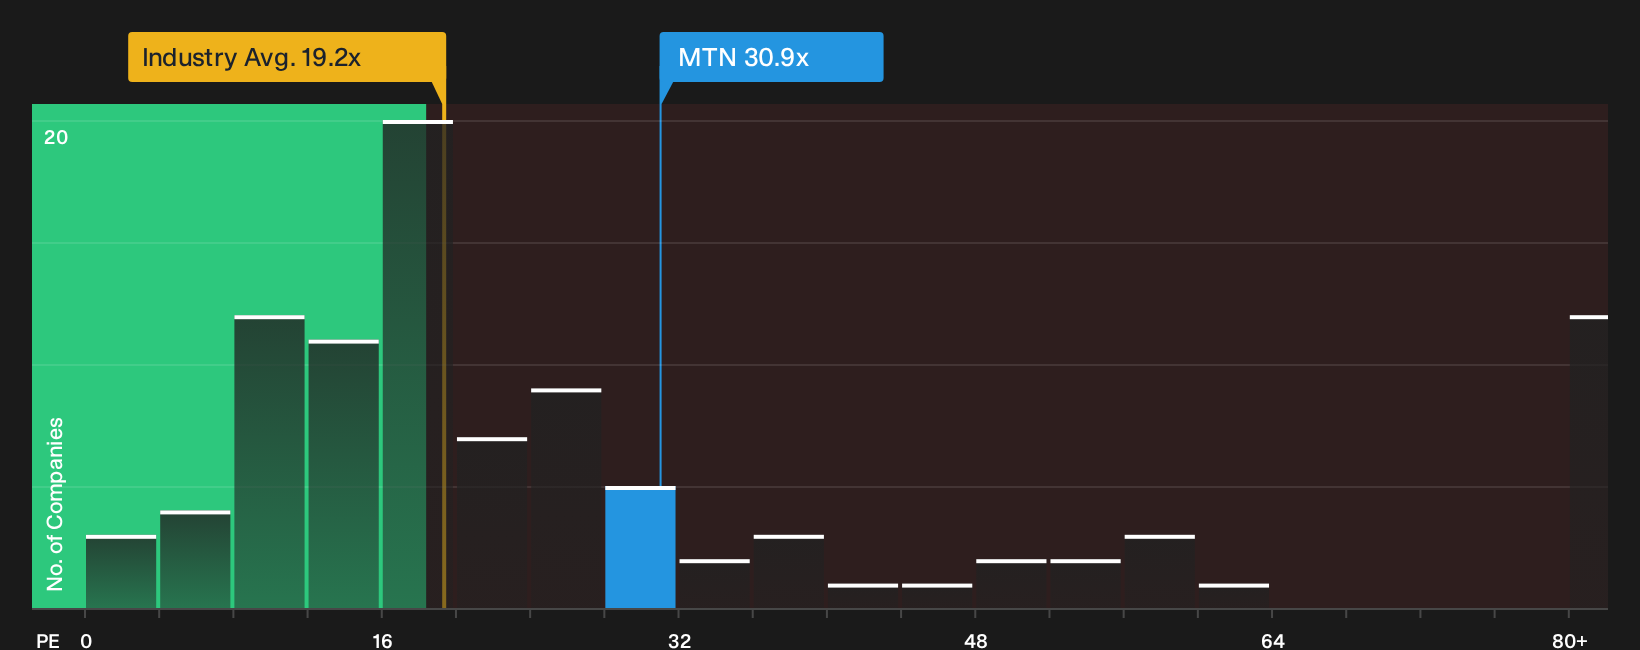
The 8% undervaluation narrative looks different when viewed through a basic P/E lens. Vail Resorts trades at 30.9x earnings compared with about 19x for both the US Hospitality industry and its peer group, while the fair ratio points closer to 25.9x. That gap suggests investors are already paying a premium, so how comfortable are you with that valuation if the weather or governance story disappoints?
To stress test that earnings multiple against hard numbers and peer benchmarks, take a closer look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Vail Resorts can tempt you to sit on the fence, but the clock keeps moving and the data is already on the table. Weigh the upside potential against the pressure points by reviewing the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Vail Resorts?
If Vail Resorts has you rethinking your portfolio mix, do not stop there. Use focused stock lists to pressure test your next move and reduce guesswork.
- Target resilience by scanning a 30 resilient stocks with low risk scores that screens for businesses designed to handle tougher conditions without sharp swings.
- Hunt for value by reviewing a 32 high quality undervalued stocks that filters for companies where price and fundamentals appear out of sync.
- Spot early opportunities by tracking a 6 elite penny stocks with strong financials that highlights smaller stocks with stronger financial profiles than many peers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com