


3 High Insider Ownership Growth Stocks For September 2026
AI-driven spending is shaking up global bond markets, with long-term yields reaching multidecade highs and safer assets suddenly paying more. Cash now has a louder voice, yet that makes fast growing businesses with founders and executives heavily invested in their own stock especially interesting. This article walks through three such high conviction growth stocks, all with significant insider ownership, and explains why some investors are watching them closely today.
The three stocks below are just a small sample, and the full screen surfaced 347 more companies with strong growth stories and heavy insider ownership that are not covered here. To identify and analyze the highest conviction ideas that fit this theme, head straight into the Fast Growing Stocks With High Insider Ownership screener.
Tesla (TSLA)
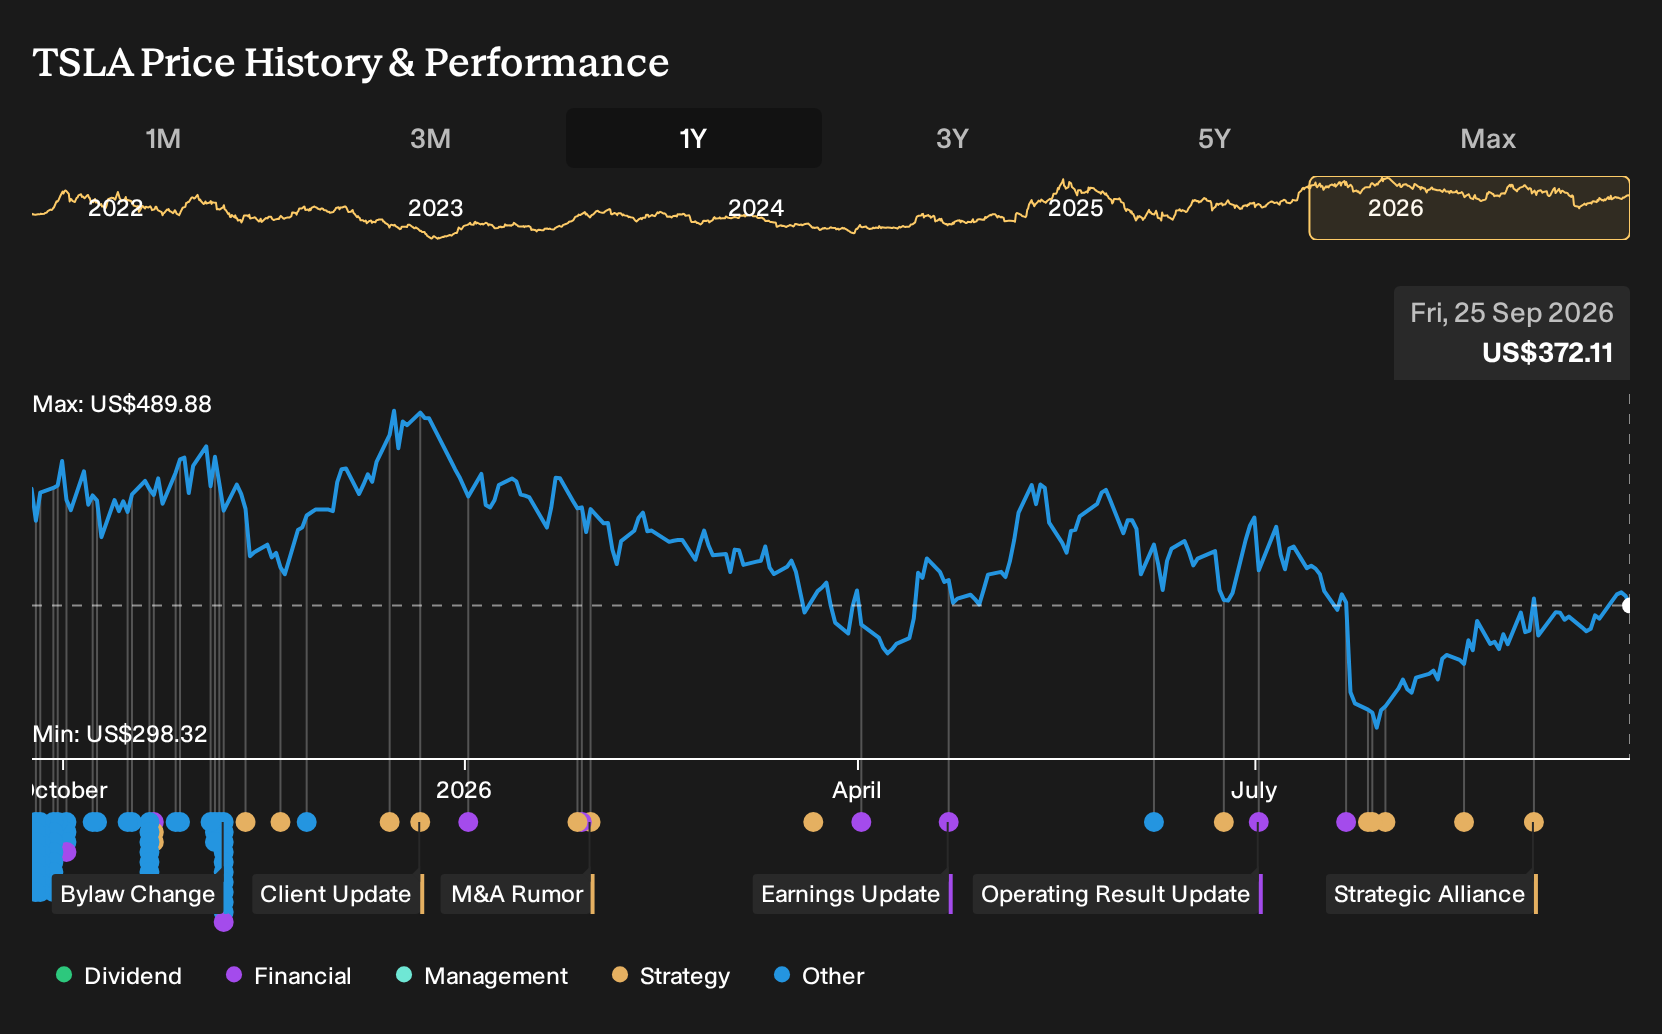
Tesla is the clearest fit for this high growth, high insider ownership theme, with its electric vehicle business and related software ecosystem forming the main engine behind ambitious plans in energy, AI and mobility that have attracted intense attention from both analysts and management.
Tesla, Inc. designs and sells electric vehicles supported by software, charging and in-app upgrades, while also running an energy storage and solar arm. Automotive operations generated about US$90.8b of the roughly US$103.6b total segment revenue, with energy at US$12.8b. The company carries a market cap near US$1.47t.
Tesla is pursuing a range of ambitious and, in some cases, speculative opportunities, including AI leadership, robotaxis, humanoid robotics and battery storage. While the company has achieved some success in energy storage, competition is intensifying there as well.
What happens to Tesla’s long term growth story if one unseen pressure quietly reshapes how much profitable demand those big ideas can really support?
If that pressure matters to you, read the full narrative for Tesla to see how Tesla’s ambitions, capital needs and insider alignment could be decoupling from headline hype.
Oracle (ORCL)
Oracle plugs directly into the fast growth, high insider alignment theme through its cloud software and infrastructure push, where Fusion Cloud applications, NetSuite and Oracle Cloud Infrastructure sit on long contracts and upbeat management commentary about future demand.
Oracle runs a broad enterprise software and infrastructure platform. Most of its US$62.8b revenue comes from cloud and software, alongside US$5.8b from services and US$3.2b from hardware, and the group carries a market value around US$415.6b.
Oracle is building gigawatt-scale data centers. One massive, 1,100-acre campus in Abilene, Texas, featuring eight buildings, is dedicated initially to OpenAI workloads and will function as the largest supercomputer ever constructed.
What that kind of cloud buildout does to long run cash flows and capital intensity depends on how one critical cost pressure evolves.
If that cost curve is what you are watching, move straight to the full narrative for Oracle to see how Oracle’s next growth phase could be accelerating.

Super Micro Computer (SMCI)
Super Micro Computer builds high performance server and storage platforms for AI, cloud and data center customers, with AI GPU systems and liquid cooled racks anchoring its fit with this fast growth, high insider ownership theme. The business generates about US$39.1b from high performance server solutions and carries a market value near US$28.4b.
For investors focused on AI infrastructure, Super Micro Computer connects this screener theme directly to the hardware that powers training clusters, inference farms and data hungry analytics. This gives management’s upbeat commentary added weight when order books and customer commitments start to swell.
The accelerating global adoption of AI and analytics continues to drive demand for high-performance, scalable server and data center solutions, positioning Super Micro for strong multi-year revenue growth as enterprises and nations build out AI infrastructure.
What that means for future earnings power depends on how one crucial pressure shapes the balance between AI-related demand and the cost of pursuing it.
That pressure is worth unpacking in the full narrative for Super Micro Computer, which traces how Super Micro Computer’s AI buildout could convert today’s demand into durable, compounding earnings power.

Seeking Fresh Alternatives Before They Fly?
New ideas move fast. Breakout themes gain momentum, then get caught by the crowd. Scan fresh stock picks while information is still under the radar for now and act now.
- Spot resilient compounders with clean balance sheets before wider attention catches them by reviewing the curated list of solid balance sheet and fundamentals (24 results).
- Ride long term income momentum from companies built around steady cash returns by scanning the hand picked 8 dividend fortresses.
- Position ahead of the next infrastructure buildout cycle by reviewing the targeted 40 power grid technology and infrastructure stocks focused on critical grid and electrification plays.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com