


EverCommerce (EVCM) Shares Just Moved, So What Is Going On?
EverCommerce (EVCM) just reshuffled its leadership bench, with longtime President and EverPro chief Matt Feierstein stepping down and new senior hires stepping into key operating, technology and strategy roles.
EverCommerce’s share price closed at US$8.08 after a mixed stretch, with a 7 day share price return of about 4%, a 30 day move down roughly 12%, and the year to date share price return down about 30%, while the 1 year total shareholder return has fallen a similar 29%. This points to fading momentum as investors reassess growth prospects and risk around the leadership transition and broader execution story.
Track how EverCommerce’s leadership shake-up compares with peers by scanning a curated group of 16 high quality undiscovered gems that the market may not be fully pricing yet.
After a share price that has dropped about 30% year to date while leadership changes ripple through EverCommerce, the real puzzle now is whether most of the easy upside is already gone or still priced ahead of you.
Most Popular Narrative: 38% Undervalued
EverCommerce closed at $8.08 while the most followed narrative anchors fair value near $13.00. The gap between price and story is wide and raises big questions about what the market is missing or dismissing.
Analyst consensus sees embedded payment adoption as a margin lift. However, with only low single-digit percentage penetration at top payment solutions that are growing total payment volume by over 12% year-over-year, there is potential for explosive payments-driven operating leverage. Payments could potentially comprise well above 30% of consolidated revenue over time, which could drive gross margin and EBITDA margin expansion well above current expectations.
See why 0 investors see EverCommerce as 38% undervalued.
Result: Fair Value of $13.00 (UNDERVALUED)
Still, EverCommerce depends heavily on small and medium-sized customers, and tougher credit conditions or slower software consolidation could quickly challenge the bullish payments and margin story.
Find out about the key risks to this EverCommerce narrative.
Another View: EverCommerce On Earnings Multiples
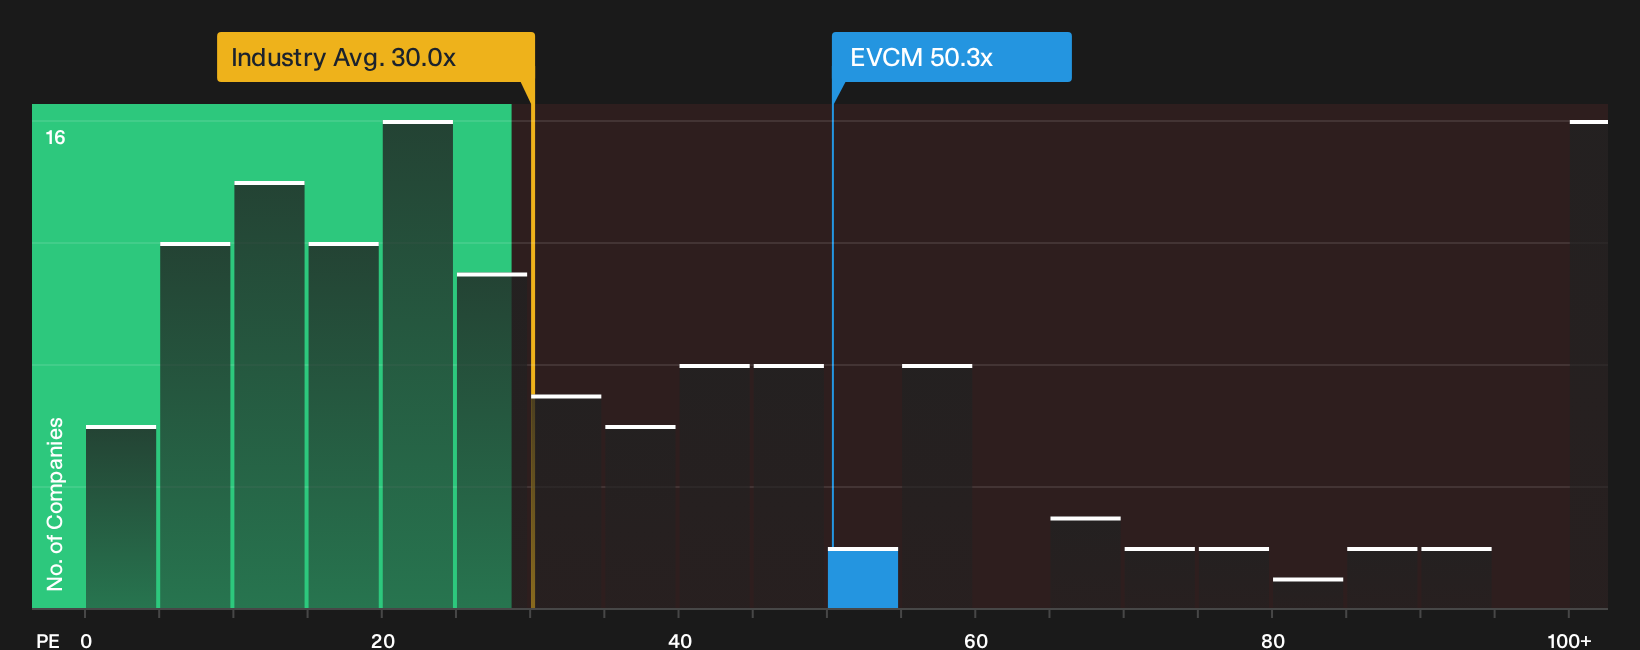
The fair value story around EverCommerce looks different once earnings ratios enter the frame. The stock trades on a P/E of about 50.3x, compared with roughly 30x for the US software group and a fair ratio of 37.8x. That points to a richer pricing profile even with an undervalued cash flow view. The question then becomes which signal you trust more: the narrative or the multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on EverCommerce so far. Consider acting while sentiment is divided and review the full picture yourself by weighing the 3 key rewards and 2 important warning signs.
Looking for more EverCommerce investment ideas?
Do not stop at EverCommerce. Broader context matters, and a few focused screeners can quickly highlight other opportunities that might fit your style and risk comfort.
- Target resilient potential by scanning a 30 resilient stocks with low risk scores that could help you avoid companies with fragile financial profiles when markets turn.
- Hunt for value by reviewing a 32 high quality undervalued stocks that filters for strong fundamentals and share prices that may not fully reflect them yet.
- Stack income potential by checking a 8 dividend fortresses that focuses on higher yielding businesses with consistent payout histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com