


Otter Tail (OTTR) Faces A Renewable Growth Test Following A Fair Value Check
Otter Tail (OTTR) has caught investor attention after recent trading, with the share price at $89.34 and a year-to-date total return of 9.7% helping shape how the utility and industrial hybrid is being assessed.
Recent trading suggests interest in Otter Tail is steady rather than euphoric, with a 1-day share price return of 1.22% and a 7-day gain of 2.20%, offset by a 30-day share price decline of 1.65% as investors reassess risk and growth expectations. Taken together, the 9.69% year to date share price return and 11.18% 1-year total shareholder return point to momentum that is still positive but less explosive than the longer 3-year and 5-year total shareholder returns of 26.53% and 79.61%.
Scan how Otter Tail stacks up against other resilient utilities and infrastructure plays by jumping into our hand picked 30 resilient stocks with low risk scores.
Bulls point to Otter Tail’s mixed utility and industrial footprint, along with its recent positive returns. Bears see a stock that already reflects a lot of good news in its current price. Which story do the valuation numbers lean toward next?
Most Popular Narrative: 1% Undervalued
Otter Tail is priced at $89.34 against a narrative fair value of $90.50, so the story hinges on whether the risks around regulation, capital spending and demand justify only a small valuation gap.
The anticipated phaseout of renewable energy credits and new restrictions under recent federal legislation threaten the economics of Otter Tail's future renewable projects beyond its currently secured solar and wind investments, potentially raising capital requirements and pressuring future earnings growth by reducing the after-tax returns on major rate base expansions.
See why 2 investors see Otter Tail as 1% undervalued.
Result: Fair Value of $90.50 (ABOUT RIGHT)
Still, the story could shift fast if Otter Tail’s projected 9% utility earnings growth or those large potential load additions fail to materialize as expected.
Find out about the key risks to this Otter Tail narrative.
Another View On Otter Tail’s Valuation
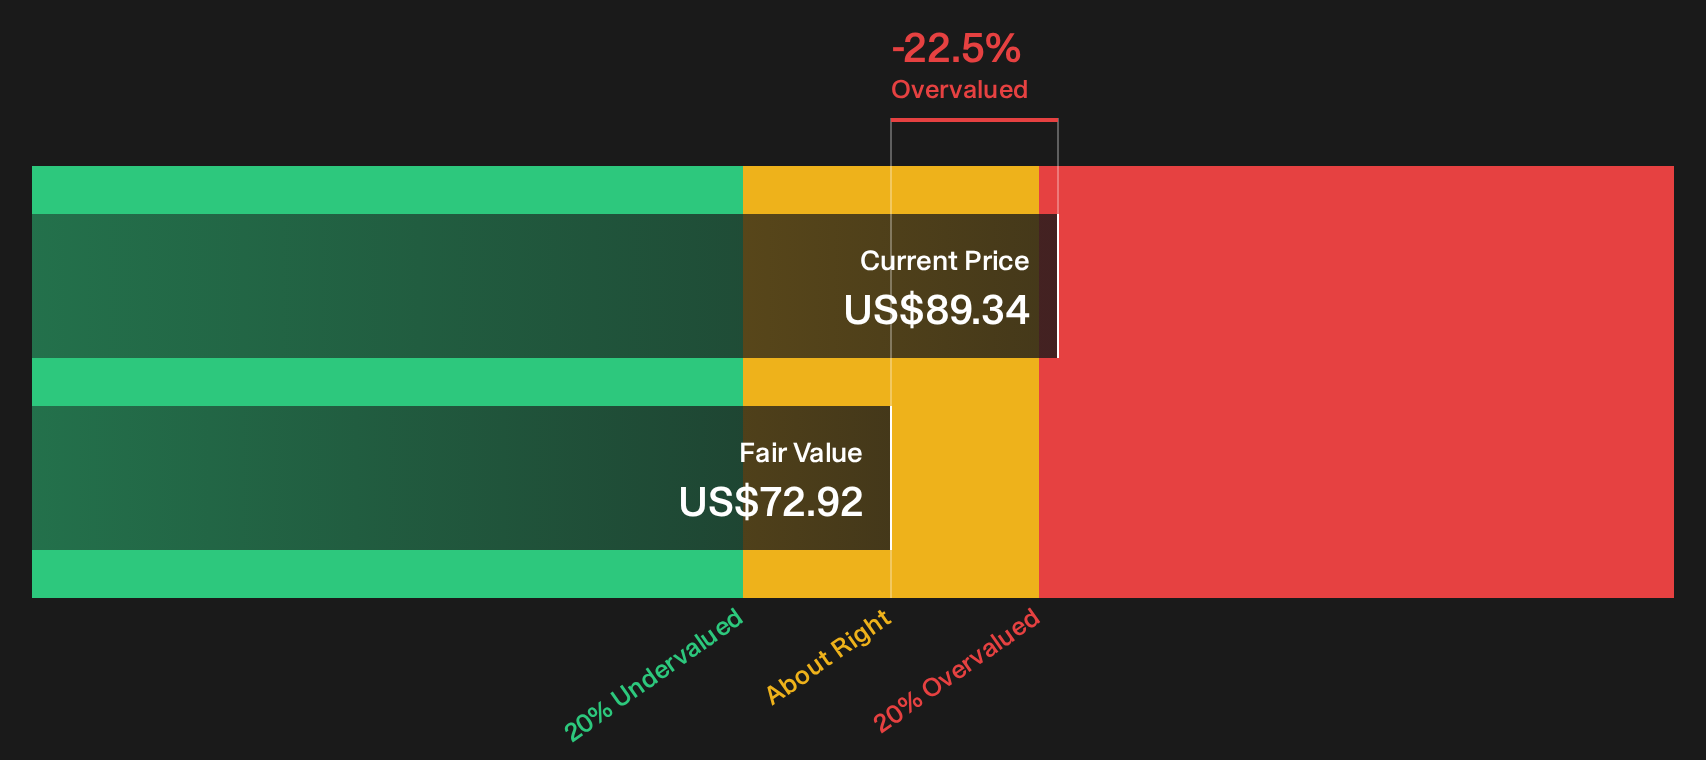
The earlier narrative fair value of $90.50 suggested Otter Tail was roughly fairly priced. The SWS DCF model paints a different picture. On that framework, the stock at $89.34 is trading above an estimated future cash flow value of $72.92, which flags it as expensive rather than cheap.
This gap matters because cash flow driven estimates focus on what Otter Tail may actually earn and return to shareholders over time, not just near term earnings multiples. If cash generation ends up closer to the DCF path than the narrative case, today’s price raises the question of whether it leaves enough room for disappointment or surprise.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Otter Tail for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Otter Tail is clearly split, which is exactly why it helps to move quickly, test the numbers yourself and decide where you land. To gauge both sides of the argument in one place, start with the 1 key reward and 5 important warning signs.
Looking for more investment ideas beyond Otter Tail?
If Otter Tail has you thinking harder about pricing, risk and income, broaden your watchlist now with a few focused stock ideas that match different goals.
- Scan for potential value by targeting companies that combine quality fundamentals with room for re rating through the 16 high quality undiscovered gems.
- Strengthen the defensive side of your portfolio by filtering for resilient businesses using the list of solid balance sheet and fundamentals (24 results).
- Turn income into a more deliberate part of your plan by zeroing in on dependable high yield payers through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com