


FactSet Research Systems (FDS) Could Be 2% Above Fair Value Following Q4 Earnings Focus
FactSet Research Systems (FDS) heads into its fiscal Q4 earnings update with expectations for higher revenue and earnings, while investors focus on client retention, subscription value growth, and management’s guidance for the coming year.
FactSet Research Systems shares trade at US$273.08 after a 30-day share price return that is down 11.6%, although the 90-day share price return is up 16.9%, and the 5-year total shareholder return is down 26.9%. This points to fading longer term momentum despite a recent bounce ahead of earnings and the Marcel Prins board appointment.
Scan beyond FactSet Research Systems and line up other financial data and analytics stocks showing resilient fundamentals using our curated list of solid balance sheet and fundamentals (24 results).
FactSet Research Systems looks like a solid data platform with growing earnings estimates, yet the share price has only just bounced after a longer slide. So is this quality now selling at a fair price or at a premium?
Most Popular Narrative: 2% Overvalued
FactSet Research Systems closed at $273.08, just above the most widely followed fair value estimate of $266.75, which frames a tight valuation debate heading into earnings.
FactSet is integrating new acquisitions like Irwin and LiquidityBook, adding immediate cross-sell opportunities and expanding services across buy-side and banking workflows. The company is also introducing new GenAI products, including Pitch Creator and a conversational API. These offerings are expected to provide additional services that support adoption and ASV growth.
See why 17 investors see FactSet Research Systems as 2% overvalued.
Result: Fair Value of $266.75 (OVERVALUED)
Still, rising technology expenses and pressure on asset management and banking budgets could weaken FactSet Research Systems’ ASV trajectory and squeeze profitability faster than bulls expect.
Find out about the key risks to this FactSet Research Systems narrative.
Another View: FactSet Research Systems Through The P/E Lens
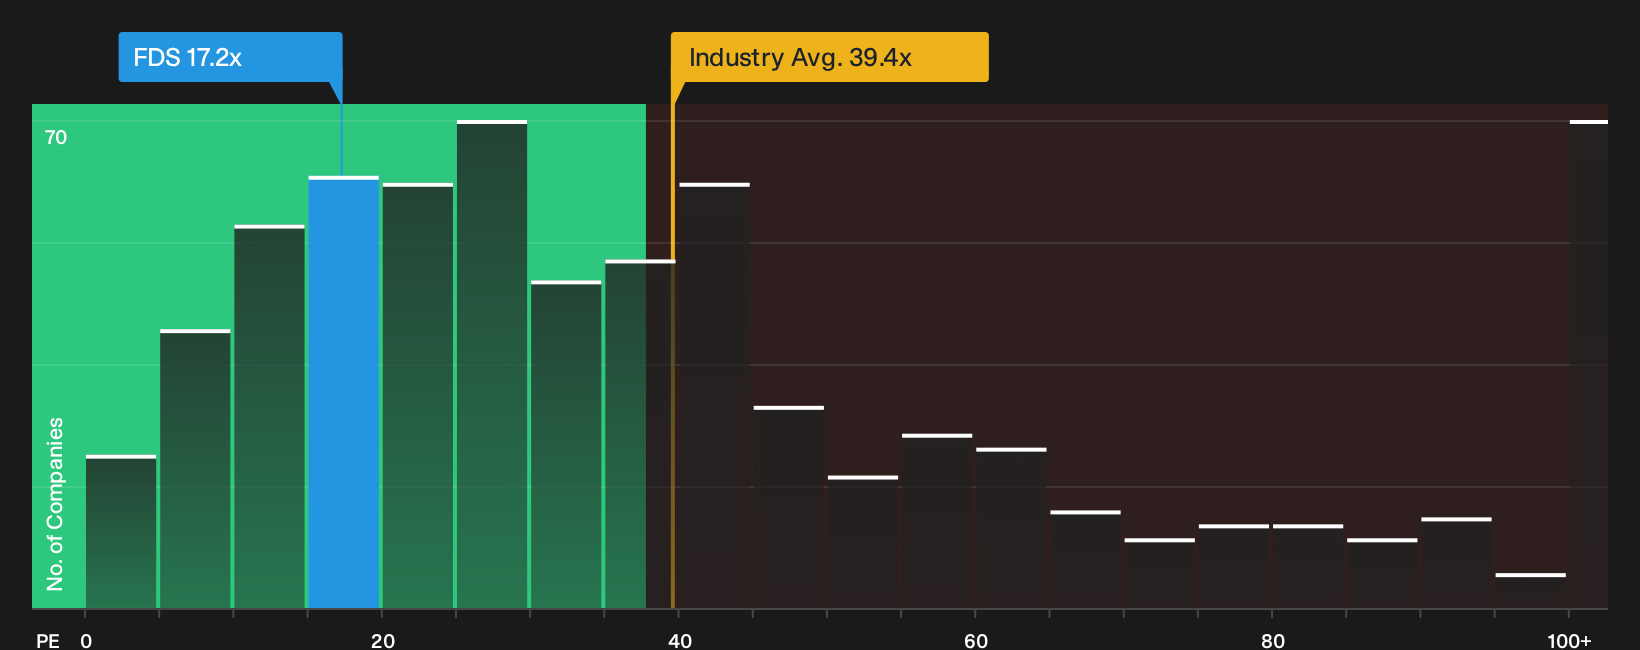
There is a different read on FactSet Research Systems when you look at the P/E. The stock trades on 17.2x earnings, which is well below the US Capital Markets industry at 39.4x and also below the peer average of 20x. It still sits above its own fair ratio of 15.5x, though. That mix suggests there could be upside room if sentiment moves toward the higher peer multiples, but also downside risk if the market shifts back toward the fair ratio instead. The key question is which way it will move first.
For a fuller picture of how this earnings multiple compares with sector and peer benchmarks, take a closer look at the detailed valuation breakdown in our work on FactSet Research Systems, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on FactSet Research Systems valuation and earnings potential are clear, so move quickly to review the full picture and form your own stance with 4 key rewards and 1 important warning sign.
Looking for more FactSet Research Systems style investment ideas?
You have seen how FactSet Research Systems stacks up today, so do not stop here when there are other opportunities that could fit your approach even better.
- Target potential mispricings by scanning a curated group of quality companies trading below their estimated worth through the 32 high quality undervalued stocks.
- Strengthen your portfolio's resilience by filtering for businesses with robust finances using the focused 30 resilient stocks with low risk scores.
- Get ahead of the crowd by zeroing in on underfollowed quality stocks through the specialist 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com