


Cosmo (SWX:CMHC) Faces A Valuation Test As Its Hybrid Story Draws Undervalued Calls
Cosmo (SWX:CMHC) has drawn fresh attention after recent trading left the share price at CHF 55.90. You are now weighing how that level fits with its mixed short and longer term returns.
Recent trading in Cosmo reflects this tension. The 1 day share price return declined 2.44% and the 90 day share price return is down 16.19%. However, the 3 year total shareholder return is up 52.30%, suggesting long term holders have still seen meaningful gains despite the sharp year to date share price fall of 46.96% and a 1 year total shareholder return decline of 9.14% that point to fading momentum.
Compare Cosmo's recent volatility with other healthcare and AI-focused businesses by scanning the hand picked 135 healthcare AI stocks that are already drawing attention for their potential.
Cosmo now trades at CHF 55.90 after a steep year to date slide. The key question is whether that reset already reflects fair value or if patience for a lower entry still makes more sense as valuation gets unpacked next.
Most Popular Narrative: 44.1% Undervalued
Against the last close at CHF 55.90, the most followed narrative for Cosmo points to a markedly higher fair value, framing the recent share price slide as a possible disconnect between pipeline expectations and current trading levels.
Cosmo is a multi-vertical life sciences platform.
• MedTech AI (GI Genius™) with a high-growth SaaS/MedTech multiple
• Dermatology (Winlevi + Clascoterone) with specialty pharma growth characteristics
• GI pharma + royalties (MMX platform) providing stable cash flows
• CDMO acting as a low-multiple stabilizer
Important: market struggles to value a hybrid business model, which can create a mispricing opportunity.
What is behind 84 investors see Cosmo as 44% undervalued.
Result: Fair Value of CHF100.00 (UNDERVALUED)
Still, this undervalued story can break if Cosmo struggles to secure new licensing deals, or if key pipeline trials disappoint and delay expected royalties.
Find out about the key risks to this Cosmo narrative.
Another View On Cosmo's Valuation
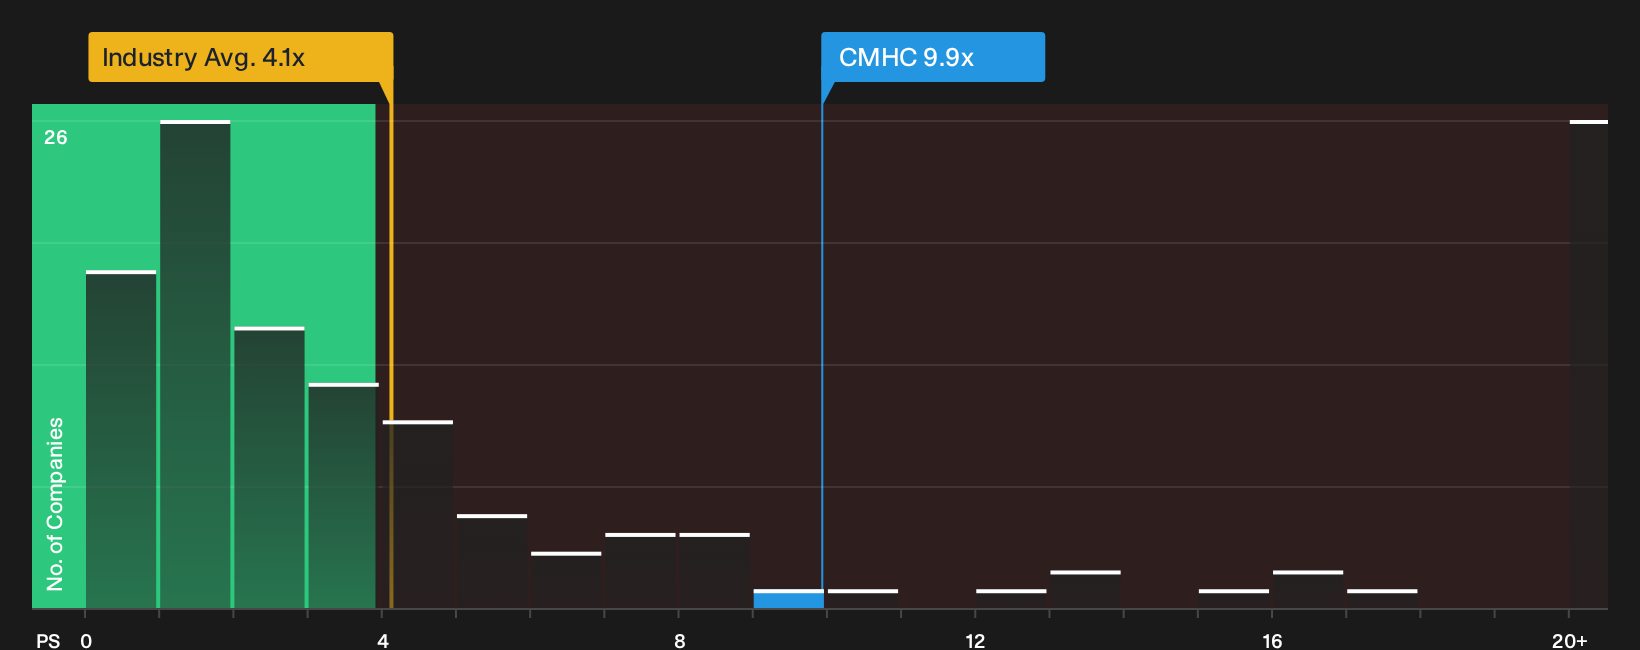
Cosmo screens as deeply discounted on fair value estimates, yet the simple P/S ratio paints a tougher picture. The stock trades on a P/S of 9.9x, which is far above the European pharmaceuticals average of 4.1x and also above a fair ratio estimate of 7.3x that the market could move toward.
Against closer peers on 17.9x P/S, that looks more forgiving, but it still leaves you asking how much valuation risk you are really willing to take if sentiment keeps shifting.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Cosmo is clearly split, with some investors focused on upside potential and others fixating on the downside risk. You can move faster than the crowd by reviewing both sides of that debate yourself, weighing what matters most to your own process, and then checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cosmo?
If Cosmo has sharpened your thinking on risk and reward, widen your opportunity set now with a few focused stock lists before the crowd moves on.
- Target high quality potential bargains by scanning companies on the 184 high quality undervalued stocks that pair solid fundamentals with discounted prices.
- Prioritise resilience by reviewing the 226 resilient stocks with low risk scores and focus on businesses that score well on stability and downside protection.
- Get ahead of the market by checking the 618 high quality undiscovered gems where strong financials meet lower visibility and less competition for ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com