


Does Softer Q2 Change The Bull Case For Progressive (PGR)?
- Progressive reported a slower Q2, with revenue in line with analyst expectations, while broader property and casualty insurers delivered stronger top line results.
- The contrast between Progressive's muted quarter and healthier peer revenue trends highlights potential pressure on its underwriting execution and competitive positioning.
- We will now explore how this softer quarter for Progressive, relative to other property and casualty insurers, could influence its investment narrative.
Compare Progressive's softer Q2 with peers that may be executing more consistently by scanning our curated list of 30 resilient stocks with low risk scores, built to handle tougher insurance cycles.
Progressive Investment Narrative Recap
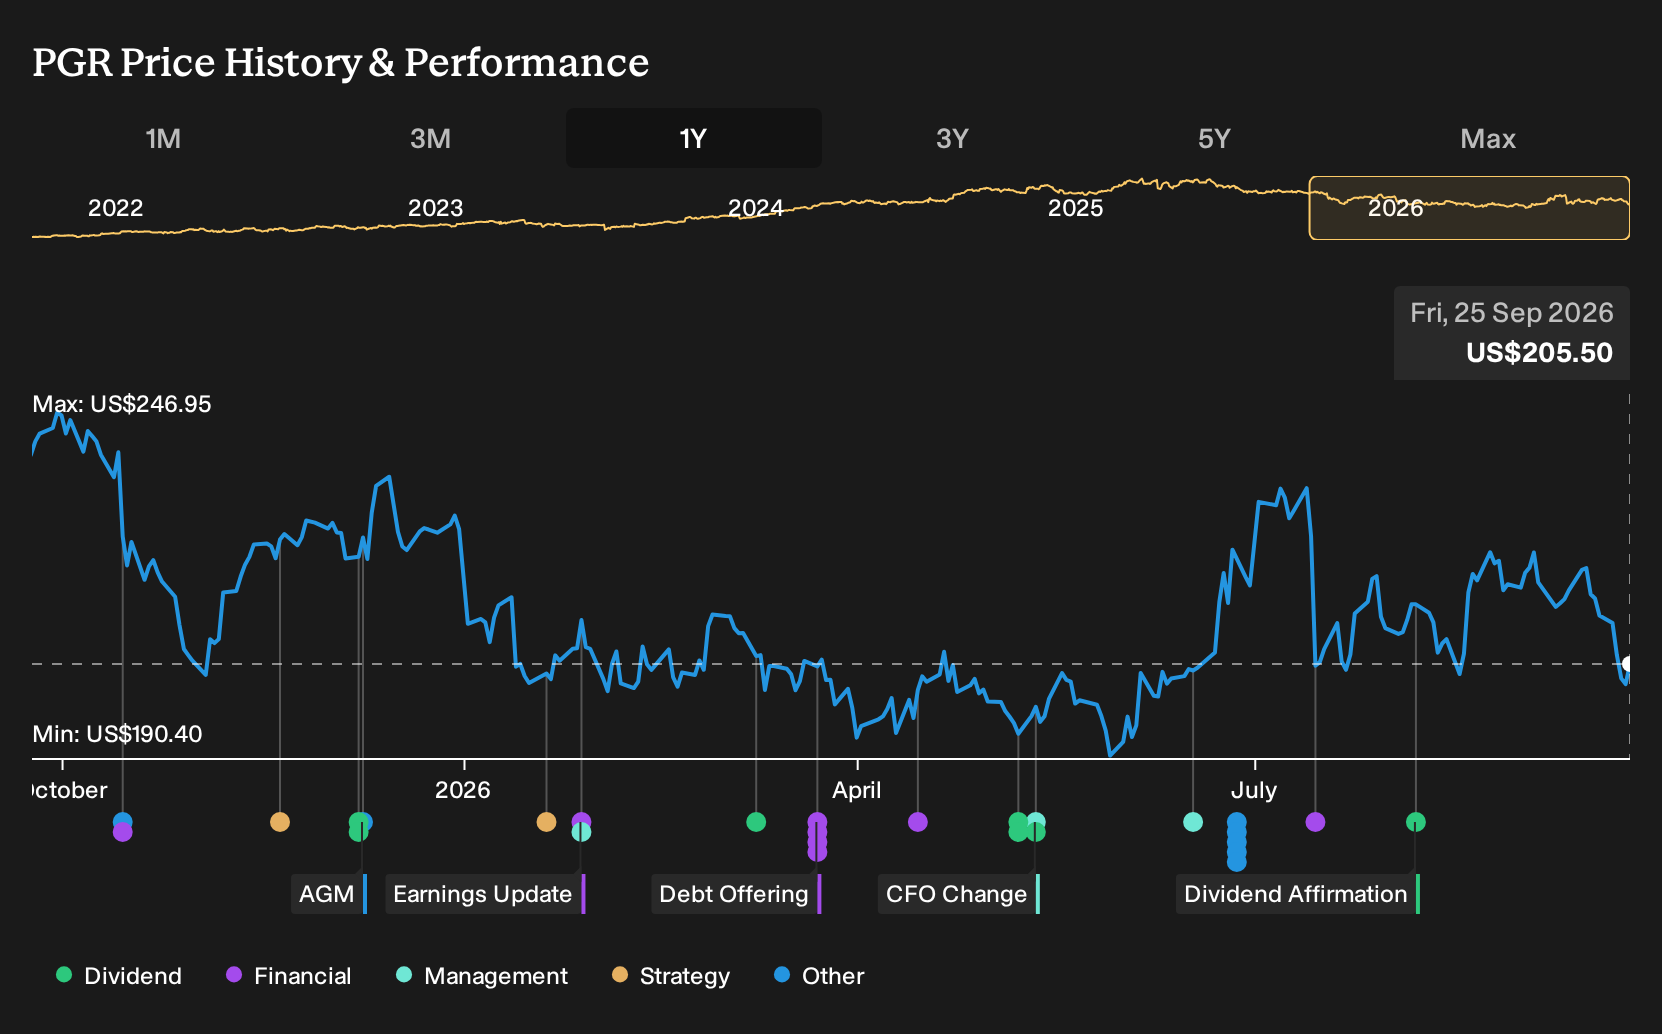
To own Progressive, you need to be comfortable with a business that leans heavily on data driven underwriting and rapid pricing changes to keep its combined ratio under control while the auto market feels more competitive and deflationary. The softer Q2 and 10.6% share price drop since earnings put a spotlight on that execution, but do not on their own rewrite the long term thesis.
Right now the key short term catalyst is whether Progressive can keep claims severity and the combined ratio in check after the recent move from 86.2 to 87.3 and a 31% June 2026 net income decline to US$779 million. The biggest risk is that claims costs or pricing pressure persist, which could keep profitability and sentiment under strain.
With no fresh corporate announcements tied directly to this quarter, the most relevant context is the existing guidance and external expectations around slower revenue and profit trends. Analysts currently see revenue growing around 3.3% per year and earnings declining about 7% annually over the next three years. That frames how this weaker Q2 is being interpreted.
For you as an investor, that backdrop means the Q2 stumble sits on top of a narrative that already bakes in more modest growth and some margin pressure for Progressive. Any future update that shows the firm stabilising its combined ratio, keeping return on equity near the 22.1% forecast, or managing claims inflation more tightly is likely to matter more than the single quarter miss that just hit the stock.
Progressive's narrative projects US$99.0b revenue and US$9.5b earnings by 2029. This assumes 2.9% yearly revenue growth and a US$2.2b decline in earnings from US$11.7b today.
Uncover why Progressive's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Progressive focuses on climate risk rather than just claims inflation. Some of the lowest analysts were already working with softer assumptions, with revenue projected to reach about US$96.9b and earnings around US$8.4b by 2029. You can treat this more cautious, climate-driven narrative as one of several viewpoints to test against the latest Q2 surprise.
Explore 3 other Progressive fair value estimates, including one that suggests it could be worth just $231.38.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Progressive research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Progressive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Progressive's overall financial health at a glance.
Looking For More Investment Ideas Beyond Progressive?
If Progressive's mixed Q2 has you rethinking concentration risk, spreading your research across a few different types of companies can help you pressure test your thesis and stress test your portfolio construction.
- For investors who want quality at a sensible entry point, scan a curated set of 32 high quality undervalued stocks that combine strong fundamentals with more measured pricing.
- If steady income matters to you, focus on companies that prioritise shareholder payouts by reviewing a group of 8 dividend fortresses with higher yield profiles.
- When capital preservation sits high on your list, concentrate on resilience by researching a pre filtered 30 resilient stocks with low risk scores that may hold up better when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com