


Westinghouse Air Brake Technologies (WAB), What Is Behind The Fresh Attention?
Westinghouse Air Brake Technologies (WAB) is back in focus after Wabtec announced a long-term services agreement worth more than US$700 million with La Compagnie du TransGuinéen for the Simandou rail project.
The contract lands as Westinghouse Air Brake Technologies shares trade at US$288.0, with short-term momentum softening after a 1-day decline of 0.77% and a 1-month share price return down 1.45%. At the same time, a 90-day share price gain of 7.34% and a year-to-date share price return of 33.16% point to building longer-term strength, echoed by a 1-year total shareholder return of 47.12% and a 5-year total shareholder return of 234.16%, which indicates that investors have already rewarded the story in a substantial way.
Scan how Westinghouse Air Brake Technologies compares with other rail and industrial infrastructure players by checking out a curated set of 40 power grid technology and infrastructure stocks
Westinghouse Air Brake Technologies now trades just below analyst targets and slightly above one intrinsic value estimate. So where does fair value really sit along that spread after this Simandou contract boost?
Most Popular Narrative: 13% Undervalued
On the most followed view, fair value for Westinghouse Air Brake Technologies sits at $329.58. This is comfortably above the recent $288.0 share price and frames the Simandou win as just one piece of a bigger earnings story already mapped out to 2029.
Sustained global investment in rail infrastructure and modernization across freight and transit, including large international awards in regions such as Australia and Latin America, is feeding into Westinghouse Air Brake Technologies’ multiyear backlog above US$30b and could support more stable revenue and earnings over several years.
See why 21 investors see Westinghouse Air Brake Technologies as 13% undervalued.
Result: Fair Value of $329.58 (UNDERVALUED)
Still, this bullish Westinghouse Air Brake Technologies story can crack if tariffs keep squeezing margins or if weaker modernization activity drags on services revenue longer than expected.
Find out about the key risks to this Westinghouse Air Brake Technologies narrative.
Another View: Valuing Westinghouse Air Brake Technologies On Today’s Multiple
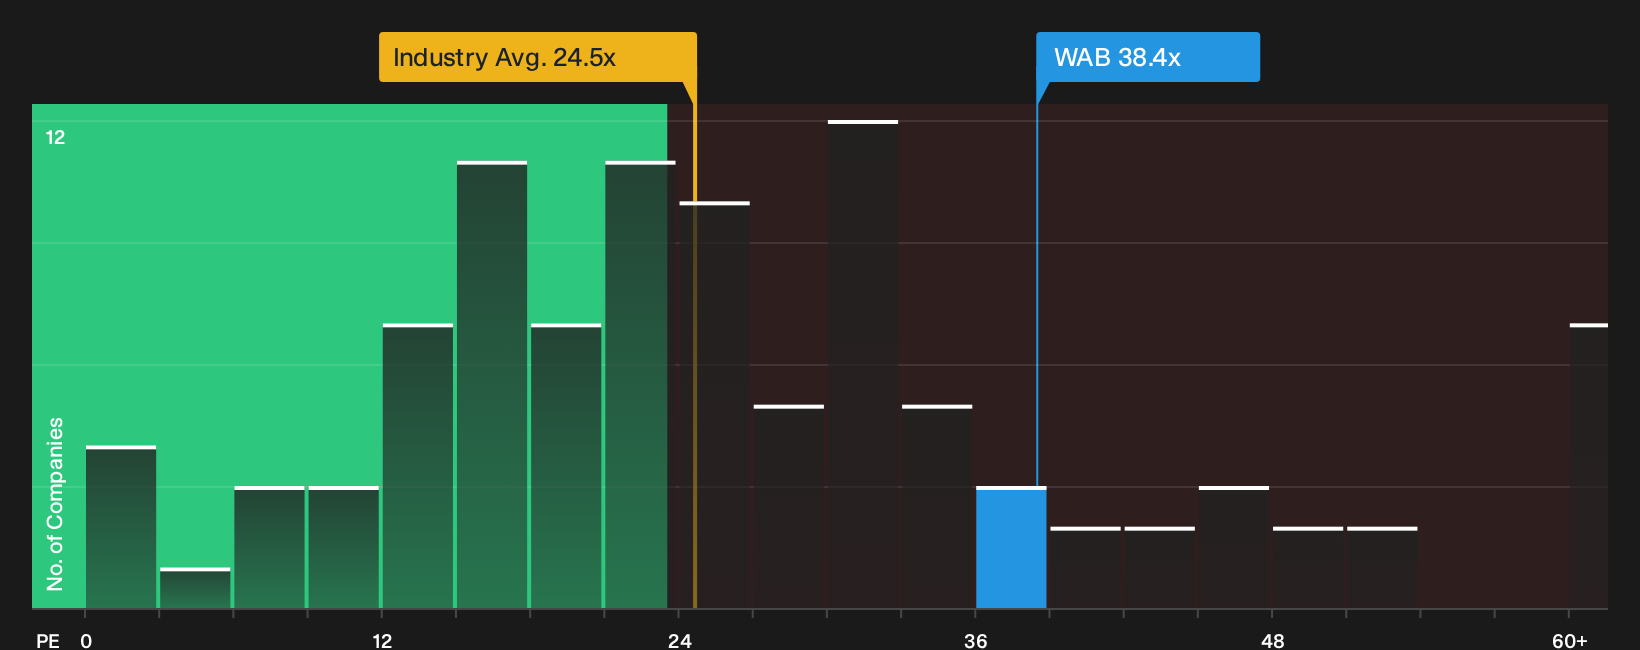
Analysts see Westinghouse Air Brake Technologies as about 13% undervalued, yet the market already prices the stock at a P/E of 38.4x. That is well above the US Machinery industry at 24.5x, the peer average at 20.6x, and even an estimated fair ratio of 31.6x. This raises a simple question: How much optimism are you comfortable paying for?
For investors weighing this richer multiple against the analyst fair value, it helps to break down what the numbers imply for upside, downside, and timing. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism threads through this Westinghouse Air Brake Technologies story, yet real money is made when you test the bullish and cautious angles yourself. Take a closer look at the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Westinghouse Air Brake Technologies?
If Westinghouse Air Brake Technologies sparked your interest, do not stop here. Spread your research across fresh ideas that fit different roles in your portfolio.
- Target potential mispricing by checking out a curated pool of companies that screen as quality yet priced below intrinsic estimates through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing a focused set of stocks offering higher yields with the 8 dividend fortresses.
- Dial down portfolio stress by scanning for companies that combine resilient fundamentals with lower risk profiles using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com