


HP (HPQ) Raised Its Outlook, Is The Upside Already Priced In?
HP (HPQ) is back in focus after third quarter results topped expectations and management raised full year earnings and free cash flow guidance, supported by tariff refunds and growing AI PC shipments.
Despite the stronger outlook, HP’s share price has pulled back over the past week, with a 7 day share price return of 9.01% in the red. However, momentum over longer horizons remains firm, with a 90 day share price return of 38.25% and a 1 year total shareholder return of 23.16%. This suggests that recent earnings and new AI focused product launches, such as the HP Googlebook 14 and ZBook Ultra G3a, are being weighed against shifting expectations around future risks and growth potential.
Scan how other AI focused hardware players are priced and positioned by running HP’s peers against our hand picked 85 AI infrastructure stocks.
After a 38.25% move over 90 days and a pullback even as guidance improved, HP now sits at an awkward crossroads. Is the meaningful upside still ahead, or did most of it already show up in the last quarter’s rally?
Most Popular Narrative: 34% Overvalued
HP last closed at $31.30, while the most followed narrative pegs fair value closer to $23.41, so the story hinges on how durable AI driven gains and margin levers really are from here.
Persistent structural cost reduction initiatives, including manufacturing diversification outside China, AI-enabled automation, and a $2B annualized savings target, are set to drive sustainable improvements in net margins and bottom-line earnings resilience.
HP's focus on responsible innovation and sustainability, exemplified by significant recycled content in devices and advances toward net zero, aligns with growing enterprise and consumer preference for eco-friendly technology, strengthening competitive positioning and supporting revenue and margin growth over the long term.
See why 58 investors see HP as 34% overvalued.
Result: Fair Value of $23.41 (OVERVALUED)
Still, HP’s heavy reliance on mature PC and print categories, along with higher memory costs tied to AI demand, could easily challenge the optimistic fair value story.
Find out about the key risks to this HP narrative.
Another View On HP’s Valuation
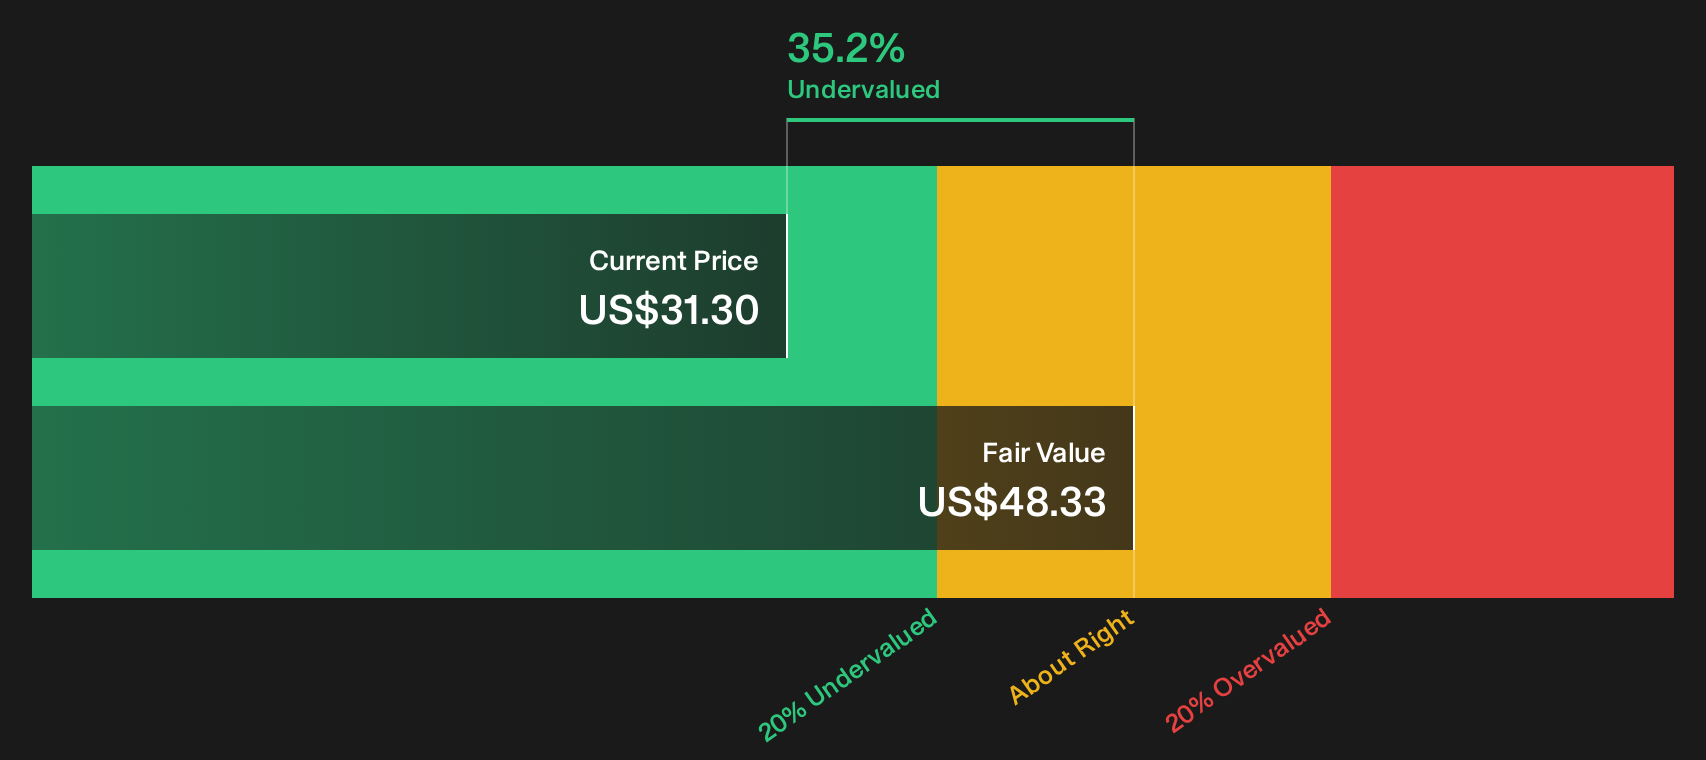
That 34% overvalued narrative clashes sharply with a different lens. Our DCF model, which prices HP off estimated future cash flows, points to a fair value of $48.33 per share. At a last close of $31.30, that implies HP trades at a sizeable discount instead of a premium. Which story do you think fits the risk and growth assumptions better?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around HP and its fair value can be confusing, so move quickly, compare the upside with the weak spots, and weigh both the 4 key rewards and 2 important warning signs.
Hunting For More HP Investment Ideas?
If HP has you thinking harder about risk, value and income, do not stop at one ticker. Put a wider watchlist to work using targeted screeners.
- Target resilient cash generators and keep a margin of safety in focus by running a 32 high quality undervalued stocks.
- Lock in potential income streams by scanning for companies that resemble 8 dividend fortresses.
- Reduce nasty surprises by filtering for businesses that pass balance sheet stress tests using a list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com