


Flywire (FLYW) Could Be 15% Undervalued After Sabrina Farmer Joins The Board
Board appointment puts Flywire’s technology ambitions in focus
Flywire (FLYW) has drawn fresh attention after appointing Sabrina Farmer to its Board of Directors and its Nominating and Corporate Governance Committee, tying the stock story more closely to large scale payment and infrastructure expertise.
Recent trading tells a mixed story for Flywire. The share price is up 25.18% year to date and the 1 year total shareholder return is 27.75%. However, a 30 day share price return of down 7.40% and a 3 year total shareholder return of down 45.44% point to momentum that has cooled in the short term, while longer term holders have seen material value erosion. This board appointment prompts a fresh look at execution risk and growth potential.
Compare Flywire’s board-driven tech focus with other payment and infrastructure plays by scanning our hand picked 85 AI infrastructure stocks now shaping how transactions move at scale.
Flywire now trades at US$17.40, while analyst targets and intrinsic estimates sit meaningfully higher. Is the recent pullback a reasonable discount, or a sign that fair value expectations need trimming?
Most Popular Narrative: 15% Undervalued
On the narrative numbers, Flywire’s fair value runs to about $20.38 using a 7.2% discount rate, compared with the current $17.40 share price. This puts the focus squarely on whether execution can keep matching those growth assumptions.
Ongoing investment in proprietary technology, AI-driven automation, and integration capabilities is yielding significant platform efficiencies (for example, 25% operational cost improvements, 90% automated payment matching, and 40% automated customer service). This underpins Flywire's ability to maintain or increase net margins and deliver stronger earnings leverage as scale increases.
See why 9 investors see Flywire as 15% undervalued.
Result: Fair Value of $20.38 (UNDERVALUED)
Still, the Flywire narrative could be knocked off course if regulatory pressure hits cross border education flows, or if lower margin travel and B2B volumes dilute profitability faster than expected.
Find out about the key risks to this Flywire narrative.
Another view on Flywire’s valuation
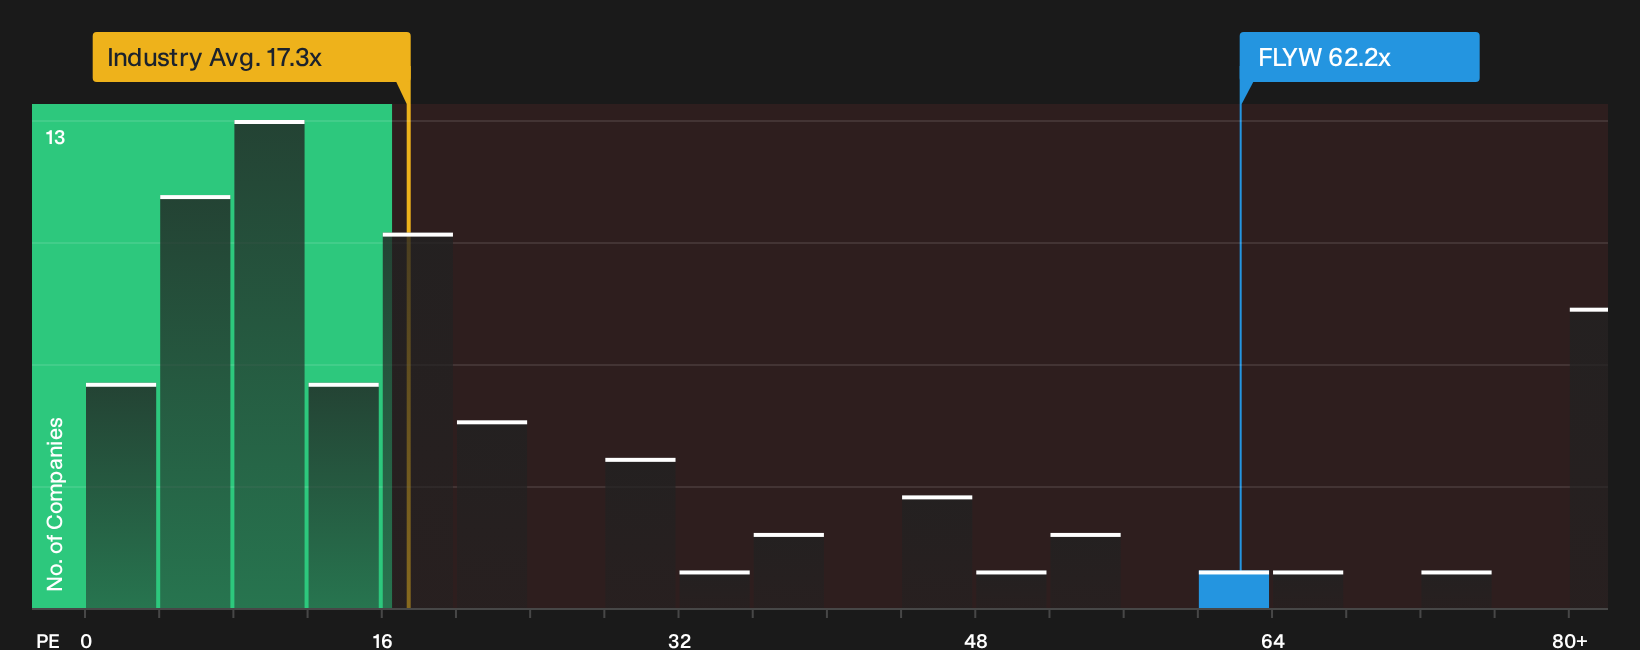
On a simple earnings lens, Flywire looks anything but cheap. The stock trades on a P/E of 62.2x, while the US Diversified Financial industry sits around 17.3x and similar peers average 34.1x. The fair ratio estimate of 24.8x implies a lot of optimism already reflected in the price.
This gap suggests that even with strong growth forecasts and the board’s technology focus, investors are paying a premium that leaves less room for error if expectations on margins or execution slip.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Flywire can feel messy, so move fast and review the full risk and reward snapshot for yourself by checking 4 key rewards and 1 important warning sign.
Looking for more Flywire-sized investment ideas?
If Flywire has sharpened your thinking, now is the moment to widen your watchlist and line up a few fresh contenders before the next move.
- Target resilient compounding by reviewing strong cash generators in the 32 high quality undervalued stocks that also show disciplined balance sheet management.
- Prioritise staying power and sleep-at-night holdings by filtering for companies in the 30 resilient stocks with low risk scores that score well on stability and financial strength.
- Hunt for tomorrow’s potential standouts by scanning the 16 high quality undiscovered gems with quality fundamentals that have not yet attracted broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com