


How Investors May Respond To Hecla Mining (HL) $500 Million Credit Facility
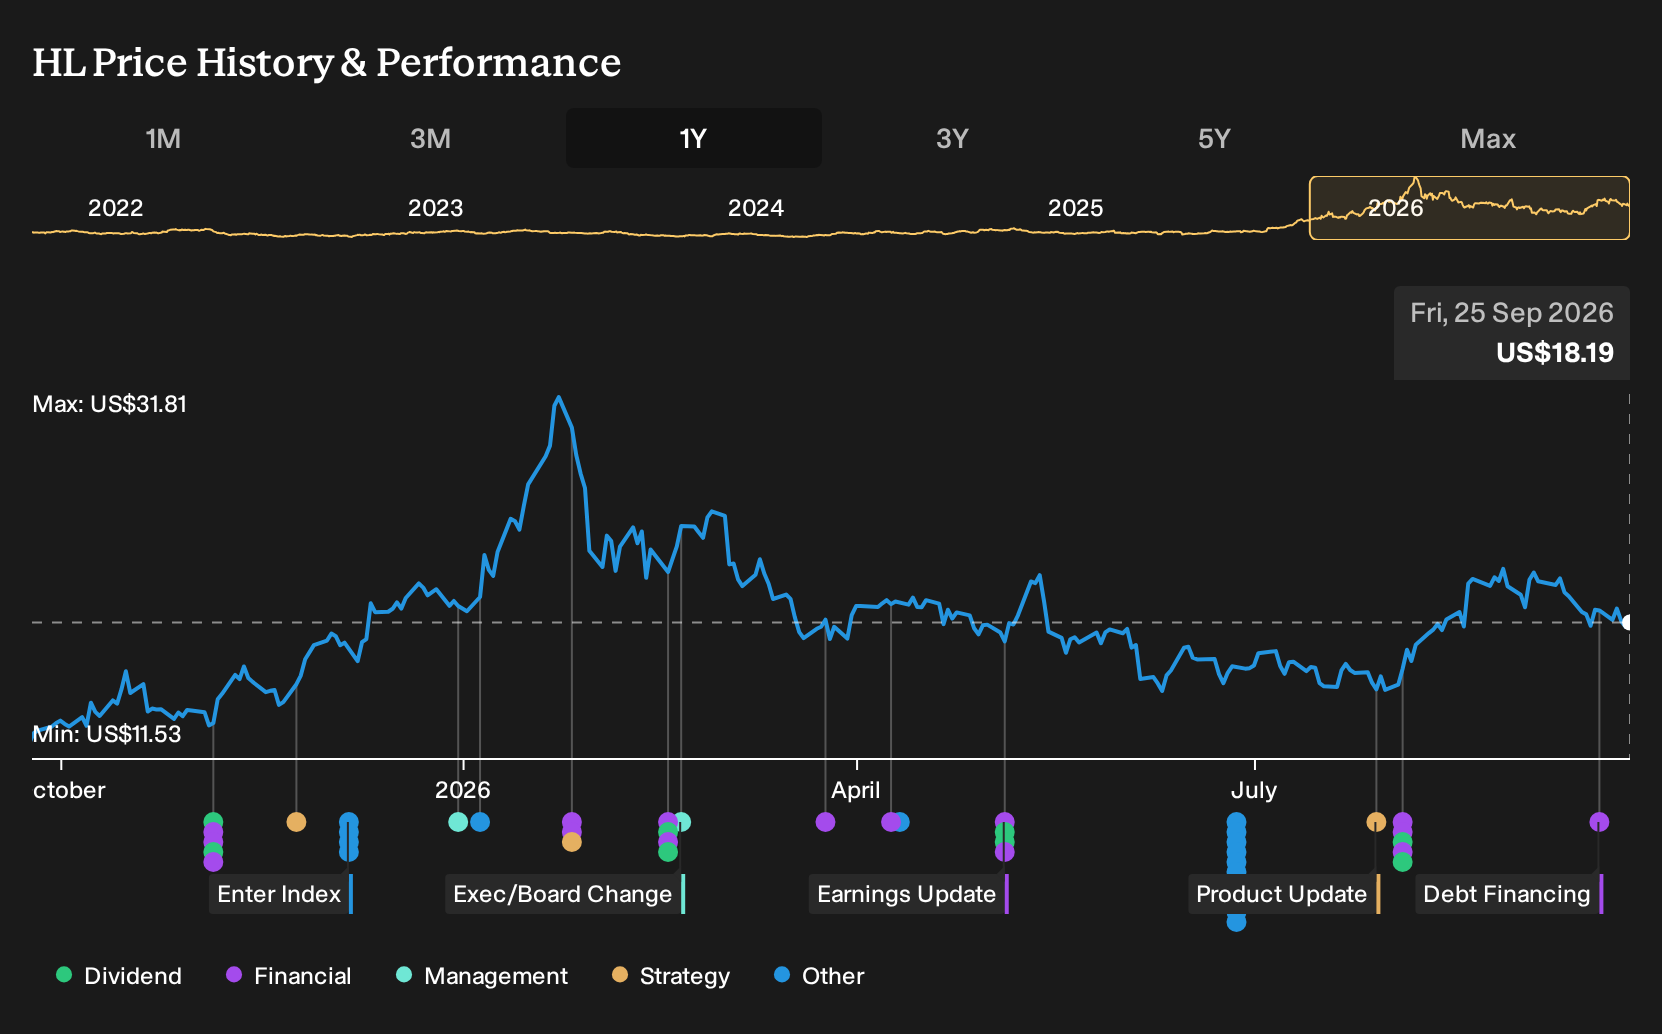
- Hecla Mining entered into a new Credit Agreement providing a US$500 million senior secured revolving credit facility, with the option to increase commitments by up to US$100 million and a maturity currently set for September 2030.
- The facility replaces the prior agreement and shifts collateral primarily to equity pledges tied to Greens Creek subsidiaries. This changes how Hecla Mining manages funding access, asset security, and covenant obligations across its operating portfolio.
- The next area of focus will be how this larger revolving facility could influence Hecla Mining's investment narrative around funding flexibility.
Scan how Hecla Mining's new credit headroom compares with peers by reviewing list of solid balance sheet and fundamentals (24 results), which could also be positioning for their next funding pivot.
Hecla Mining Investment Narrative Recap
To own Hecla Mining, you need to be comfortable tying your capital to a silver heavy producer that leans on long lived assets like Greens Creek, Lucky Friday and Keno Hill while managing declining grades and mine life at places such as Casa Berardi. The new US$500 million revolving facility mostly reinforces access to liquidity rather than changing this core production story.
In the near term, the key swing factor is execution on throughput, cost control and capital spending as Keno Hill ramps and technology projects absorb cash. The larger revolver modestly eases funding pressure around those projects. The bigger risk still sits with rising capital needs, potential permitting delays and any dip in silver pricing that tightens free cash flow.
The fresh credit agreement is the clearest recent disclosure and matters because it touches both funding risk and growth options. A committed US$500 million line, plus potential US$100 million of incremental commitments, gives Hecla Mining more room to time spending on mine development, tailings infrastructure and automation rather than relying solely on internal cash generation or equity issuance.
That flexibility interacts directly with existing catalysts. Keno Hill throughput plans, cost improvements at Greens Creek and Lucky Friday, and potential deleveraging moves all rely on stable financing. Covenants around net leverage and interest coverage now sit in the background as guardrails. If operations or silver prices soften, those constraints could quickly become as important to watch as production guidance.
Hecla Mining's narrative projects US$1.5b revenue and US$539.3 million earnings by 2029, based on analyst consensus. That outlook assumes revenue declines of 4.6% per year and an earnings decrease of about US$13.2 million from current earnings of US$552.5 million.
Uncover why Hecla Mining's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on sector consolidation rather than funding risk. They see Hecla Mining as a potential buyer of stressed assets, backing that view with forecasts of about US$1.7b in revenue and US$928.3 million in earnings by 2029. Those estimates were set before this new credit facility, so opinions may evolve from here.
Explore 4 other Hecla Mining fair value estimates, including one that suggests as much as 76% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Hecla Mining research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Hecla Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Hecla Mining's overall financial health at a glance.
Looking For More Ideas Beyond Hecla Mining?
If you want to pressure test Hecla Mining against other opportunities, using the Simply Wall St Screener can help you build a watchlist that matches your own risk, income, and value preferences rather than relying on a single story.
- For investors hunting for mispriced value with stronger quality markers, consider scanning our 32 high quality undervalued stocks that already clear tough cash flow and balance sheet filters.
- If capital protection and steadier profiles matter more to you than big swings, narrow your search to companies in the 30 resilient stocks with low risk scores and see which ones line up with your risk tolerance.
- Those looking for earlier stage opportunities with solid underlying metrics can work through our 6 elite penny stocks with strong financials to spot smaller businesses that still meet basic financial checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com