


Is Aker (OB:AKER) Still Undervalued On OBX Index Inclusion?
Aker (OB:AKER) has been added to the Oslo OBX Total Return Index, drawing fresh attention from investors who track this Norwegian benchmark and funds that mirror its composition.
Aker’s share price has eased in the short term, with a 7-day share price return of 7.19% and a 30-day share price return of 5.98%. However, the 90-day share price return of 27.96% and year-to-date gain of 85.62% suggest that momentum has been strong. At the same time, total shareholder return of 98% over one year and 172.08% over three years points to long-running gains that frame today’s NOK1,446.0 share price and the index inclusion as part of a broader rerating of the company’s prospects and perceived risk profile.
Scan for other potential index beneficiaries by comparing Aker with hand picked 185 high quality undervalued stocks that also show strong recent momentum and institutional interest.
Aker’s surge into the OBX has already rewarded existing holders. The live question now is whether today’s NOK1,446 price still leaves meaningful upside, or if most of the easy gains are already behind the stock.
Most Popular Narrative: 20% Undervalued
Aker trades at NOK1,446 while the leading valuation storyline, according to RS77, pins fair value closer to NOK1,800 per share. That gap is where the current debate sits, because the thesis leans heavily on how the group’s tech exposure might reshape its balance sheet and perceived risk.
Key Assumptions & Valuation Logic: Net Asset Value (NAV) Revaluation: Baseline Q2 2026 NAV of NOK 1,429 per share is adjusted upward to reflect the implied market valuation of AI infrastructure provider Nscale at a target IPO valuation of $25B (~NOK 262.5B). Nscale Ownership Contribution: Aker’s 22.7% stake in Nscale is valued at ~NOK 59.6B (~NOK 802/share). Factoring in existing carrying values, this delivers a net NAV lift of ~NOK 370 per share, establishing an updated intrinsic NAV of NOK 1,799 (~NOK 1,800).
See why 5 investors see Aker as 20% undervalued.
Result: Fair Value of NOK1,800 (UNDERVALUED)
Still, the Aker story leans heavily on Nscale’s future IPO outcome and assumes the current NAV discount narrows. Both of these factors could easily break the thesis.
Find out about the key risks to this Aker narrative.
Another View: Aker And Cash Flow Value
The popular narrative pegs Aker at around NOK1,800 per share based on asset values and Nscale. A different lens tells a very different story. The SWS DCF model estimates future cash flows support a value near NOK51.01, which points to the current NOK1,446 price looking expensive against that framework.
That kind of gap leaves you weighing a simple question: Are the assets and optionality so attractive that they outweigh what the DCF is saying, or is the enthusiasm already running ahead of the underlying cash generation potential?
Look into how the SWS DCF model arrives at its fair value.
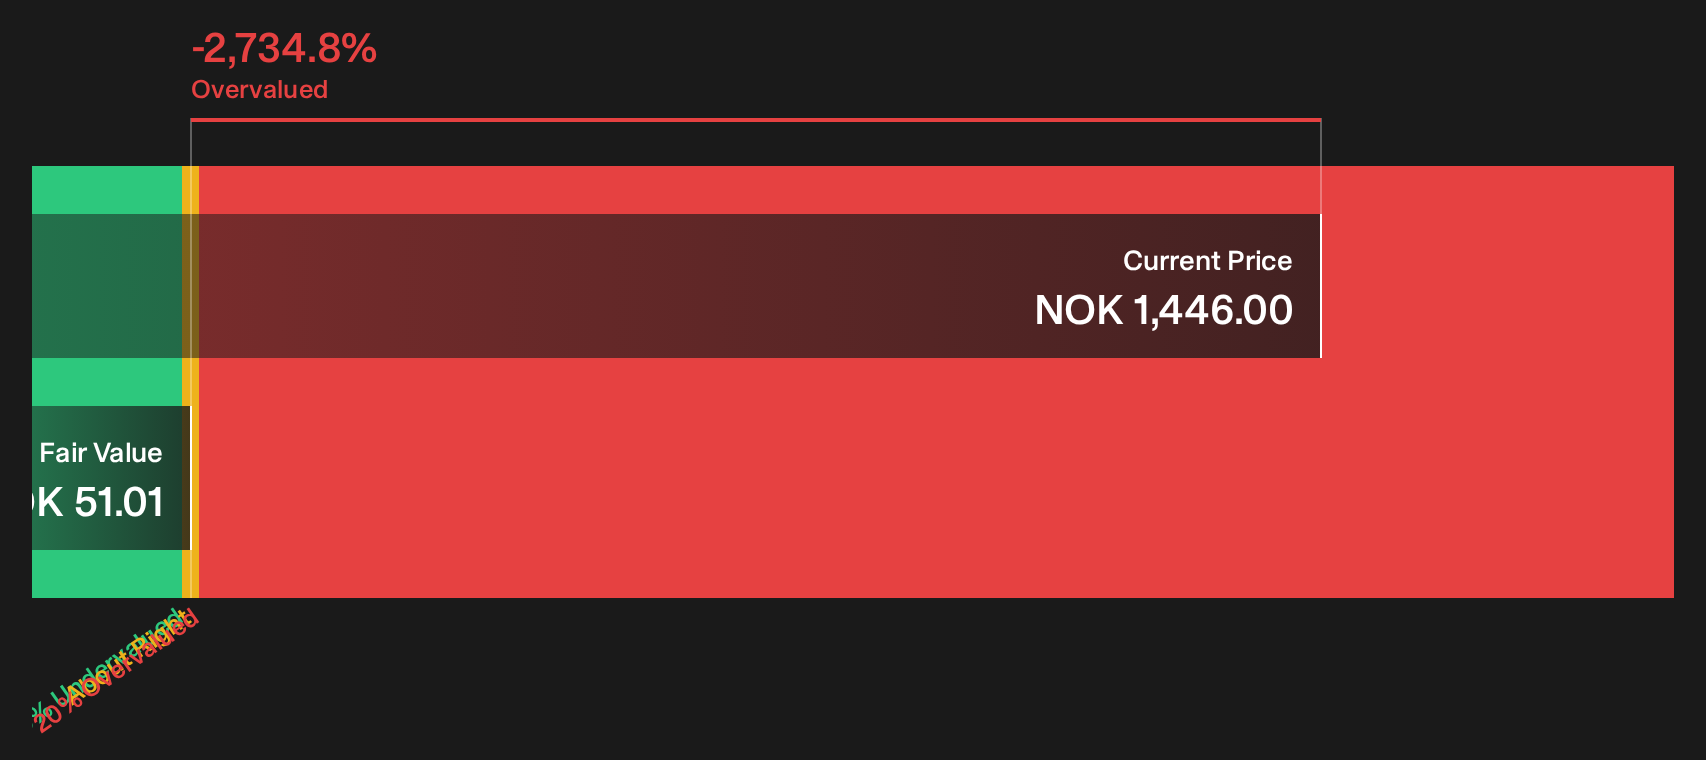
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aker for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Aker is split between rich upside and real pressure points. Consider moving quickly, reviewing the full data, and weighing both the 2 key rewards and 3 important warning signs.
Looking for more Aker investment ideas?
If you want broader context around Aker, use a few high quality filters to surface other opportunities before the market moves on without you.
- Target resilient payers and stress test your income plans with 159 dividend fortresses that still clear basic quality and payout checks.
- Focus on financial strength by scanning a list of solid balance sheet and fundamentals (201 results) so you are not caught out by weak leverage or thin liquidity.
- Hunt for tomorrow's potential leaders using a curated pool of 618 high quality undiscovered gems before attention and liquidity fully arrive.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com