


Unicaja Banco (BME:UNI) Could Be 18% Overvalued After FTSE All World Inclusion
Unicaja Banco (BME:UNI) has been added to the FTSE All-World Index, bringing the Spanish retail lender onto the radar of global index-tracking funds and a broader base of international investors.
At a share price of €3.626, Unicaja Banco has built clear momentum, with a 90-day share price return of 17.73% and a year-to-date share price return of 28.04%. The 1-year total shareholder return of 64.65% and very large 5-year total shareholder return indicate that recent buying interest around the FTSE All-World inclusion is building on an already strong longer term track record in the market.
Scan how Unicaja Banco compares to other fast moving financials by running the hand picked 185 high quality undervalued stocks, which couples solid balance sheets with clear upside potential signals.
After a surge like this and a fresh seat in the FTSE All-World Index, the debate around Unicaja Banco is simple: Is most of the gain already banked, or is pricing still catching up to fundamentals?
Most Popular Narrative: 18% Overvalued
Analysts following Unicaja Banco see fair value at €3.06, which sits below the recent close of €3.626. As a result, the current rally is being measured against a narrative that already reflects relatively optimistic earnings assumptions and a higher starting point than earlier research rounds.
The analysts have a consensus price target of €3.06 for Unicaja Banco based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €3.6, and the most bearish reporting a price target of just €2.6.
See why 2 investors see Unicaja Banco as 18% overvalued.
Result: Fair Value of €3.06 (OVERVALUED)
Still, the overvaluation story can crack if Unicaja Banco keeps shrinking non performing assets and fee income from mutual funds and insurance continues to build.
Find out about the key risks to this Unicaja Banco narrative.
Another View: What Unicaja Banco’s P/E Is Really Pricing In
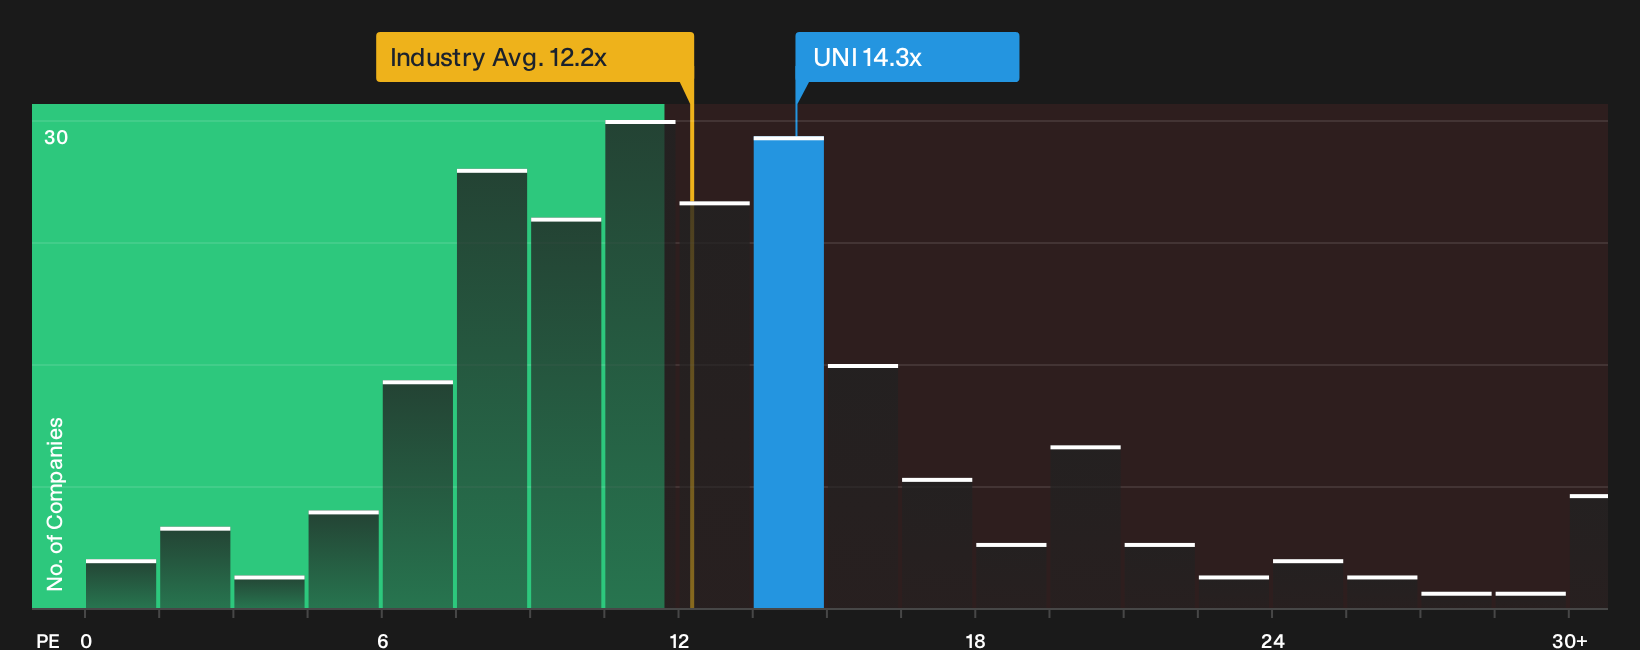
The first narrative casts Unicaja Banco as 18% overvalued against analyst targets, yet the plain P/E story is less one sided. The shares trade on 14.3x earnings compared with a 15.5x peer average, but above European banks at 12.2x and the fair ratio of 12.4x.
That mix means investors pay less than close peers, but more than both the wider sector and the level our fair ratio suggests the multiple could drift toward if expectations cool. Is that a margin of safety or a valuation risk you are comfortable carrying?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment split between overvaluation worries and a strong past return profile, consider acting promptly and testing the story against your own checklist. To weigh both the potential upsides and the concerns in one place, start with the 3 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Unicaja Banco?
If Unicaja Banco has you rethinking what is possible for your portfolio, do not stop here. The real edge comes from lining up a smarter watchlist.
- Target strong cash generators with room to rerate by scanning a focused shortlist of 185 high quality undervalued stocks that pair solid balance sheets with clear upside potential signals.
- Build a steadier income stream by checking out 159 dividend fortresses that aim to combine high yields with resilient underlying businesses.
- Dial down portfolio stress and concentrate on resilience by reviewing 226 resilient stocks with low risk scores that score well on financial strength and risk controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com