


What Mattel (MAT)'s Bluey Licensing Deal Means For Shareholders
- Mattel reshaped its EMEA Consumer Products unit into five category pillars and rolled out new Thomas & Friends content and toys, alongside a multi year Bluey licensing deal spanning Barbie, Hot Wheels, Fisher Price, Polly Pocket and UNO.
- The combined push into refreshed kids content and brand collaborations suggests Mattel is leaning harder into high margin IP and consumer products licensing across regions.
- We will now look at how Mattel’s IP led Bluey collaboration could influence the existing investment narrative around brand monetisation.
Mattel Investment Narrative Recap
To stay invested in Mattel, you need to believe the shift toward IP led play, content and licensing can offset uneven box office driven demand and recent earnings pressure. The current story is about turning strong brands like Barbie, Hot Wheels and Thomas & Friends into broader entertainment ecosystems while keeping the Optimizing for Profitable Growth program on track.
In the short term, the key swing factor is how effectively Mattel converts this IP into higher margin consumer products without letting debt levels and cost inflation eat into profitability. The new EMEA structure looks incremental rather than transformational, so the bigger risk remains execution on margin targets while revenue growth expectations stay modest.
The Bluey partnership with BBC Studios is the clearest operational link to this consumer products reorganization. It connects a fast growing preschool franchise to five Mattel pillars at once: Barbie, Hot Wheels, Fisher Price, UNO and others. This could deepen character based play patterns and give the refreshed EMEA licensing team a high profile test case.
As a potential catalyst, Bluey gives Mattel more exposure to streaming led kids hits, not just theatrical releases and adult collectors. The opportunity is broader reach and more consistent demand, while the risk is over indexing to a single preschool property or stretching partner terms. Execution on rollout timing, product quality and retailer support will matter more than headlines in this context.
What The Mattel IP Push Implies For The Numbers
Mattel's narrative projects US$6.2b revenue and US$463.7m earnings by 2029. This implies 4.0% yearly top line growth and an earnings increase of about US$36.3m from the current US$427.4m.
Uncover why Mattel's fair value indicates a 37% potential upside to its current price, which could narrow quickly.
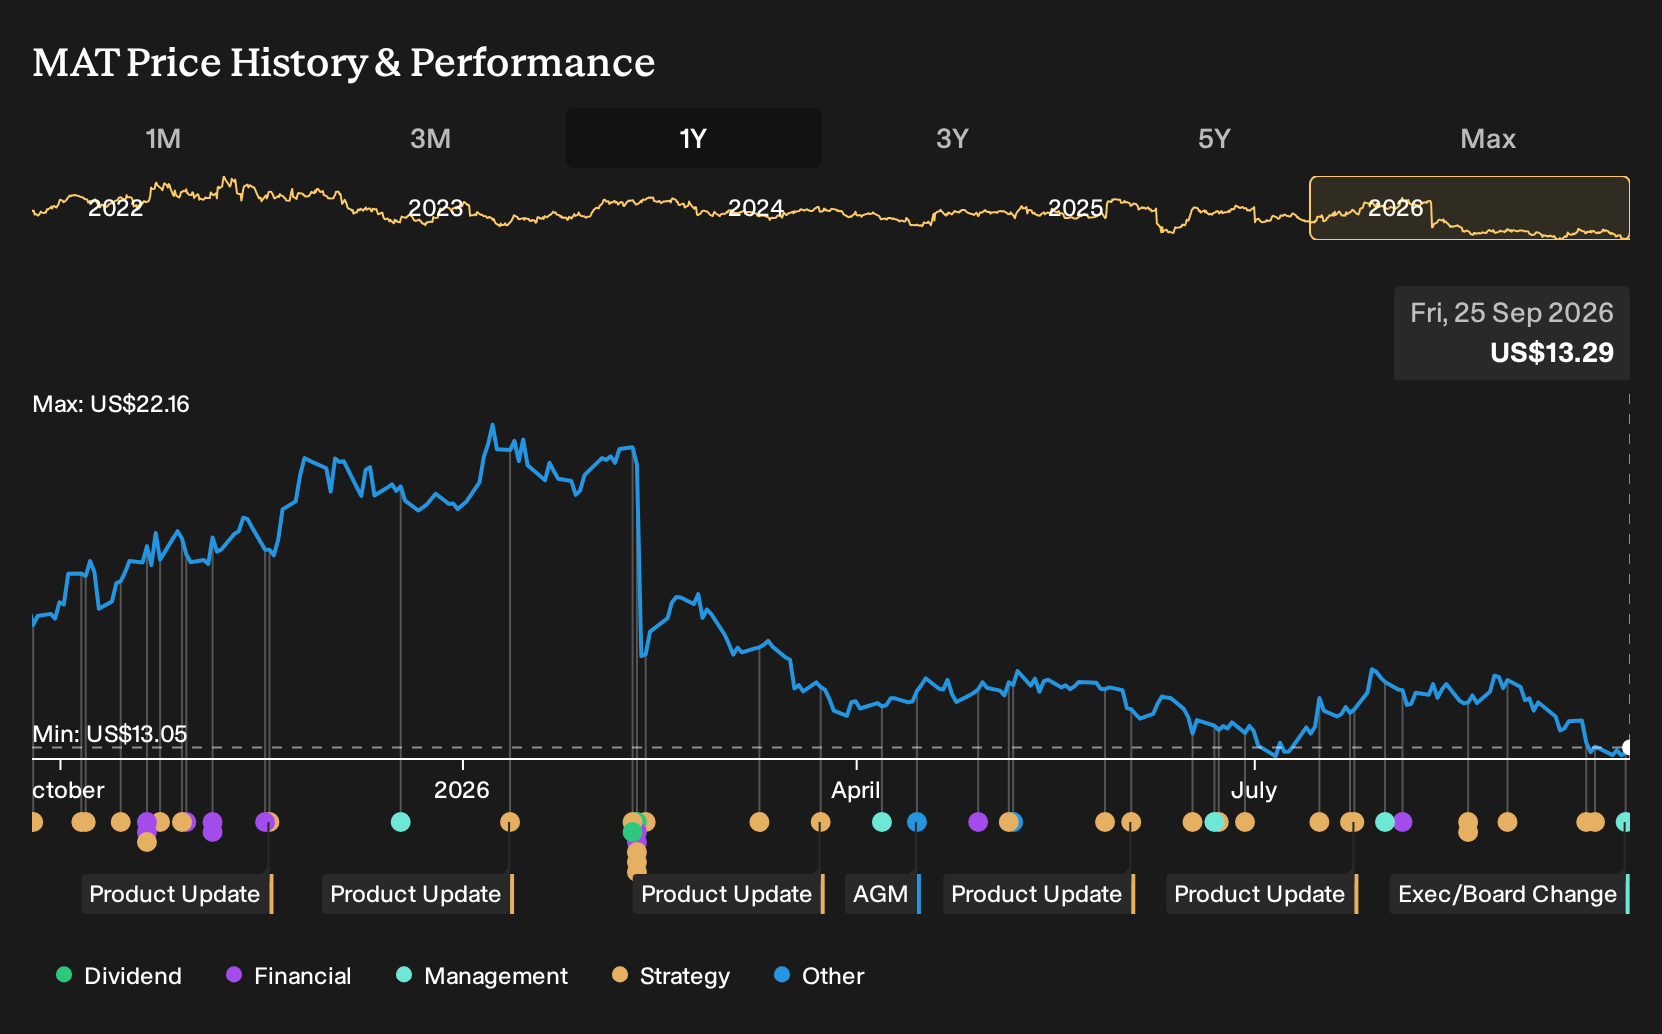
Exploring Other Perspectives
One contrasting angle is the bearish worry that Mattel’s IP push cannot fully offset weaker demand for traditional toys. The lowest analysts were pencilling in about US$5.8b of revenue and US$385.4m in earnings by 2029 before this news. That is a much harsher script. Use this Bluey and EMEA shift as a cue to compare both stories for yourself.
Explore 3 other Mattel fair value estimates, including one that suggests it could be worth just $18.15!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mattel research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Mattel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mattel's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mattel?
If the Mattel story has you thinking about where else brand power, solid balance sheets, or income potential might show up, the Simply Wall St Screener can help you cast a wider net without getting lost in tickers.
- For investors who care most about financial resilience, review a list of solid balance sheet and fundamentals (24 results) that puts balance sheet strength and solid fundamentals front and centre.
- If income is your priority, consider a 8 dividend fortresses that focuses on companies with yields above 5% paired with an emphasis on stability.
- Curious about under followed opportunities, scan a 16 high quality undiscovered gems that filters for quality fundamentals where the crowd is not yet paying full attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com