


How Raised Sales Guidance At Dollarama (TSX:DOL) Has Changed Its Investment Story
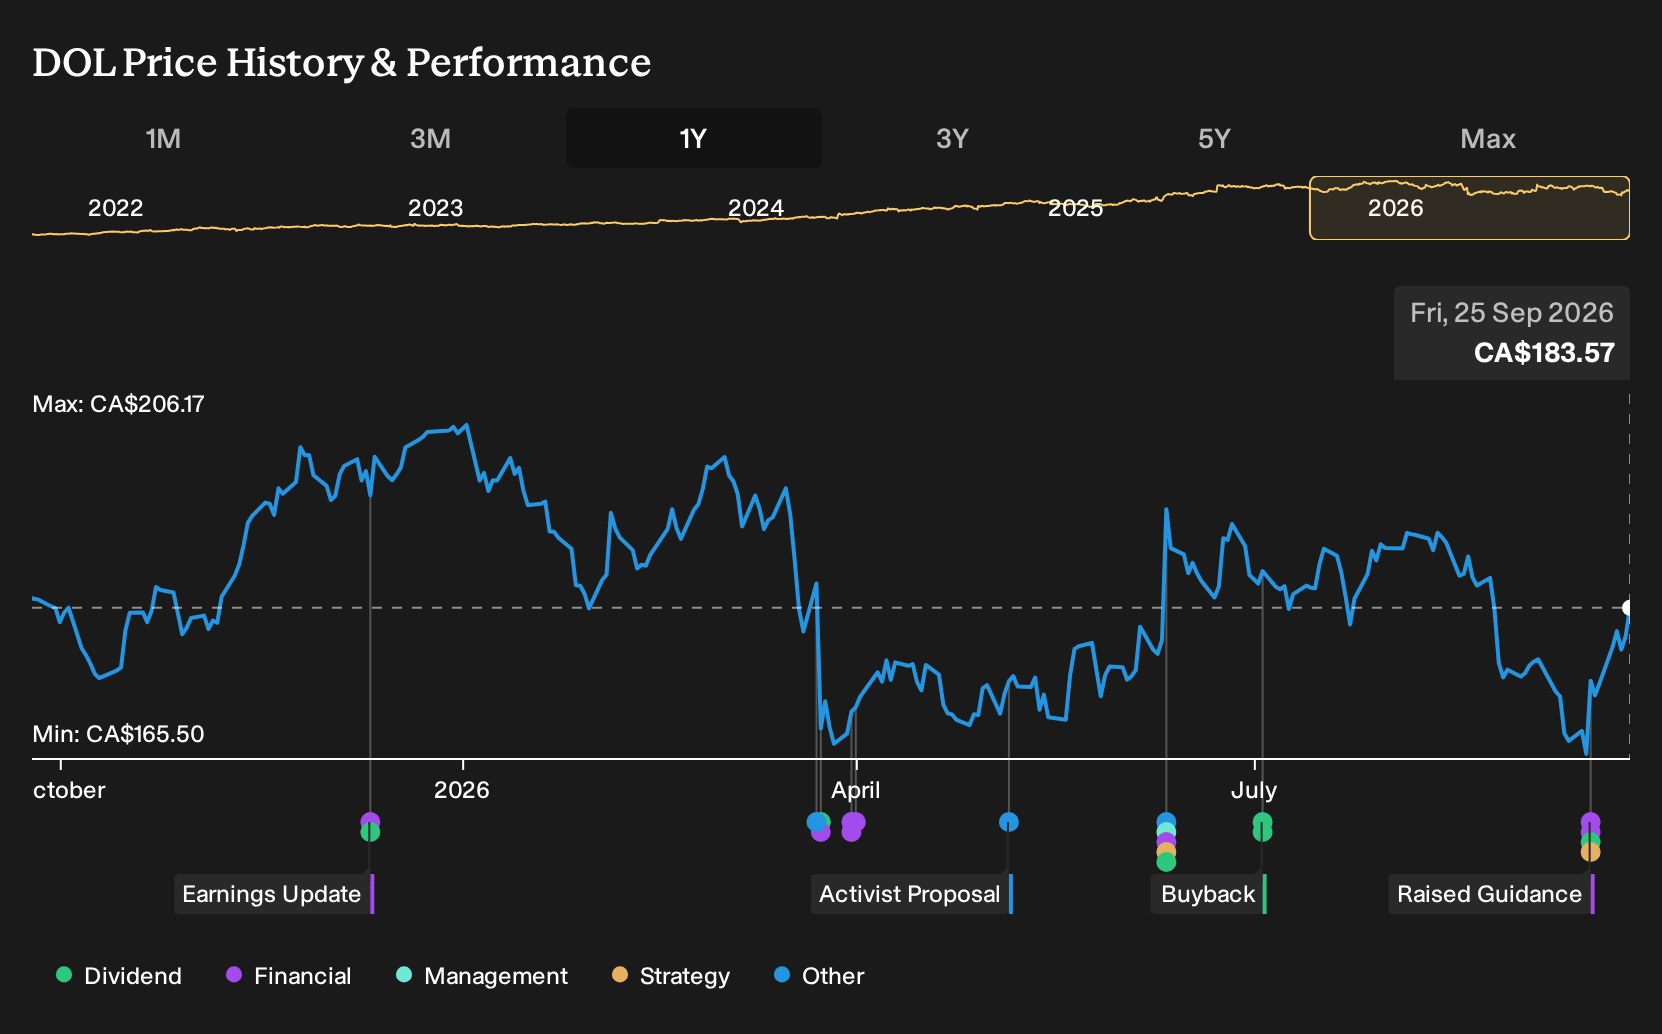
- Dollarama raised its fiscal 2027 same store sales guidance to 4% to 4.5%, reported higher Q2 and year to date earnings, reaffirmed its dividend, and lifted its net new store openings outlook to 65 to 75 locations.
- The combination of stronger sales trends, an expanding store footprint, and ongoing capital returns through dividends and buybacks highlights how Dollarama is trying to balance growth investment with returning cash to shareholders.
- We will look at how Dollarama's higher same store sales guidance reshapes the existing investment narrative around expansion and efficiency.
Scan how Dollarama's upgraded guidance and capital returns compare with peers by reviewing our hand picked list of 5 high quality undervalued stocks with resilient balance sheets and disciplined cash deployment.
Dollarama Investment Narrative Recap
To own Dollarama, you need to believe its discount format can keep pulling in value focused shoppers, while an expanding Canadian and international footprint stays productive. The higher fiscal 2027 same store sales guidance to 4% to 4.5% reinforces that view in the near term and supports the current store build out plans.
The key short term swing factor is whether traffic and basket size hold up as more locations open and consumers remain price sensitive. The biggest operational risk is that rapid expansion in Canada, Mexico and Australia runs into saturation or cost pressure, which could squeeze margins even if reported sales remain solid.
The most relevant recent update here is the Q2 2026 result. Dollarama reported quarterly sales of CA$2,026.65 million and net income of CA$349.32 million, with basic EPS of CA$1.29 from continuing operations. For the first half, sales were CA$3,872.73 million and net income was CA$651.59 million, with EPS of about CA$2.40.
Those figures give a clearer read on how the higher same store sales guidance and the plan to open 65 to 75 net new stores in fiscal 2027 compare with recent execution. In the near term, consistent transaction growth and disciplined costs are important, while any sign of margin strain or weaker unit economics would quickly refocus attention on expansion risk.
How Dollarama's Forecasts Frame The Expansion Story
Analysts sketch a fairly clear roadmap for Dollarama. Revenue is projected to grow by 10.9% a year over the next three years, with profit margins expected to ease from 18.9% today to 17.5% by around 2028 as the network scales into Mexico and Australia. On current estimates, earnings are seen at about CA$1.6b by 2028 compared with roughly CA$1.3b today, which implies an increase of about CA$300m in profit even with some margin compression.
Those forecasts also assume a shrinking share count, with analysts expecting shares outstanding to decline by about 1.97% each year for the next three years. That mix of top line expansion, slightly lower margins and fewer shares underpins forecast earnings per share of CA$5.97 by 2028. For anyone tracking the thesis, the key question is whether Dollarama can keep pushing revenue higher at a double digit clip while also absorbing higher wages, integration costs and store build out spending without letting profitability erode faster than expected.
Dollarama's narrative projects CA$9.1b revenue and CA$1.6b earnings by 2028. This assumes 10.9% yearly revenue growth and an earnings increase of about CA$300m from CA$1.3b today.
Uncover why Dollarama's fair value points to a 15% potential upside to its current price before the discount window narrows.
Exploring Other Perspectives
One alternate view on Dollarama leans hard into e commerce risk. Those analysts worry online shopping could cap store traffic and keep same store sales muted, even with higher 2027 guidance. Before this update, the most pessimistic forecasts still had revenue reaching about CA$9.5b and earnings near CA$1.8b by 2029. That is a very different story from consensus. It shows how far opinions can spread and why you might want to compare several narratives before deciding how this fresh guidance and buyback activity could reshape expectations.
Explore 5 other Dollarama fair value estimates, including one that suggests as much as 8% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Dollarama research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dollarama. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Dollarama's overall financial health at a glance.
Looking For More Dollarama Style Ideas?
If the Dollarama story has you thinking about what else might fit your watchlist, it can help to scan a wider field of stocks with similar qualities around value, resilience, or income. The Simply Wall St Screener lets you filter for those traits directly so you are not relying on headlines alone.
- For investors who want quality at a reasonable price, review a curated pool of 5 high quality undervalued stocks that combine fundamentals with appealing valuations.
- If capital preservation matters most, focus on businesses flagged as 8 resilient stocks with low risk scores where balance sheet strength and more stable risk scores take priority.
- For anyone hunting beyond the usual tickers, scan a 9 high quality undiscovered gems that pair solid financial profiles with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com