


3 UK M&A Advisory Stocks Exposed To The Takeover Rush
UK dealmaking has snapped back to life, with a surge in overseas and private equity buyers hunting what they see as undervalued London-listed companies. That wave of bids is reshaping where fees, premiums and risks land. If you care about where the next £1b in advisory and takeover activity might flow, this article walks through three UK M&A advisory and dealmaking stocks that are exposed to the latest takeover rush.
The three stocks below are just a sample of what UK M&A advisory and dealmaking exposure can look like on the market, and the full screen surfaced 20 more companies with equally detailed stories that are not covered here. To go deeper into this space, identify your own angles and analyze potential high-conviction ideas, head straight into the UK M&A Advisory and Dealmaking Firms screener.
Gateley (Holdings) (AIM:GTLY)
Gateley (Holdings) plugs directly into the UK M&A advisory theme as a quoted commercial law and consultancy group that earns a large share of its income from deal-related corporate, property and business services work for buyers, sellers and their lenders.
Gateley (Holdings) runs a broad professional services platform across corporate, property, people and business services. Most revenue comes from property at about £100.6 million, followed by corporate at £40.4 million, business services at £34.8 million and people at £18.5 million, and the group carries a market value of roughly £97.5 million.
Although continued investment in complex international dispute resolution, restructuring advisory and cross-border corporate work positions Gateley to benefit from rising demand for specialist advice in an uncertain economic and regulatory environment, sustained macro volatility could limit transactional volumes and constrain the pace of revenue growth.
What happens to Gateley (Holdings)'s earnings profile if one unseen pressure quietly shifts how much of that advisory effort converts into paid fees?
If that fee conversion risk matters to you, read the full narrative for Gateley (Holdings) for how Gateley (Holdings) could react if dealmaking accelerates again.

Catella (OM:CAT B)
Catella plugs into the UK M&A advisory theme through its real estate corporate finance arm, which sits alongside a larger investment management operation focused on European property assets and funds.
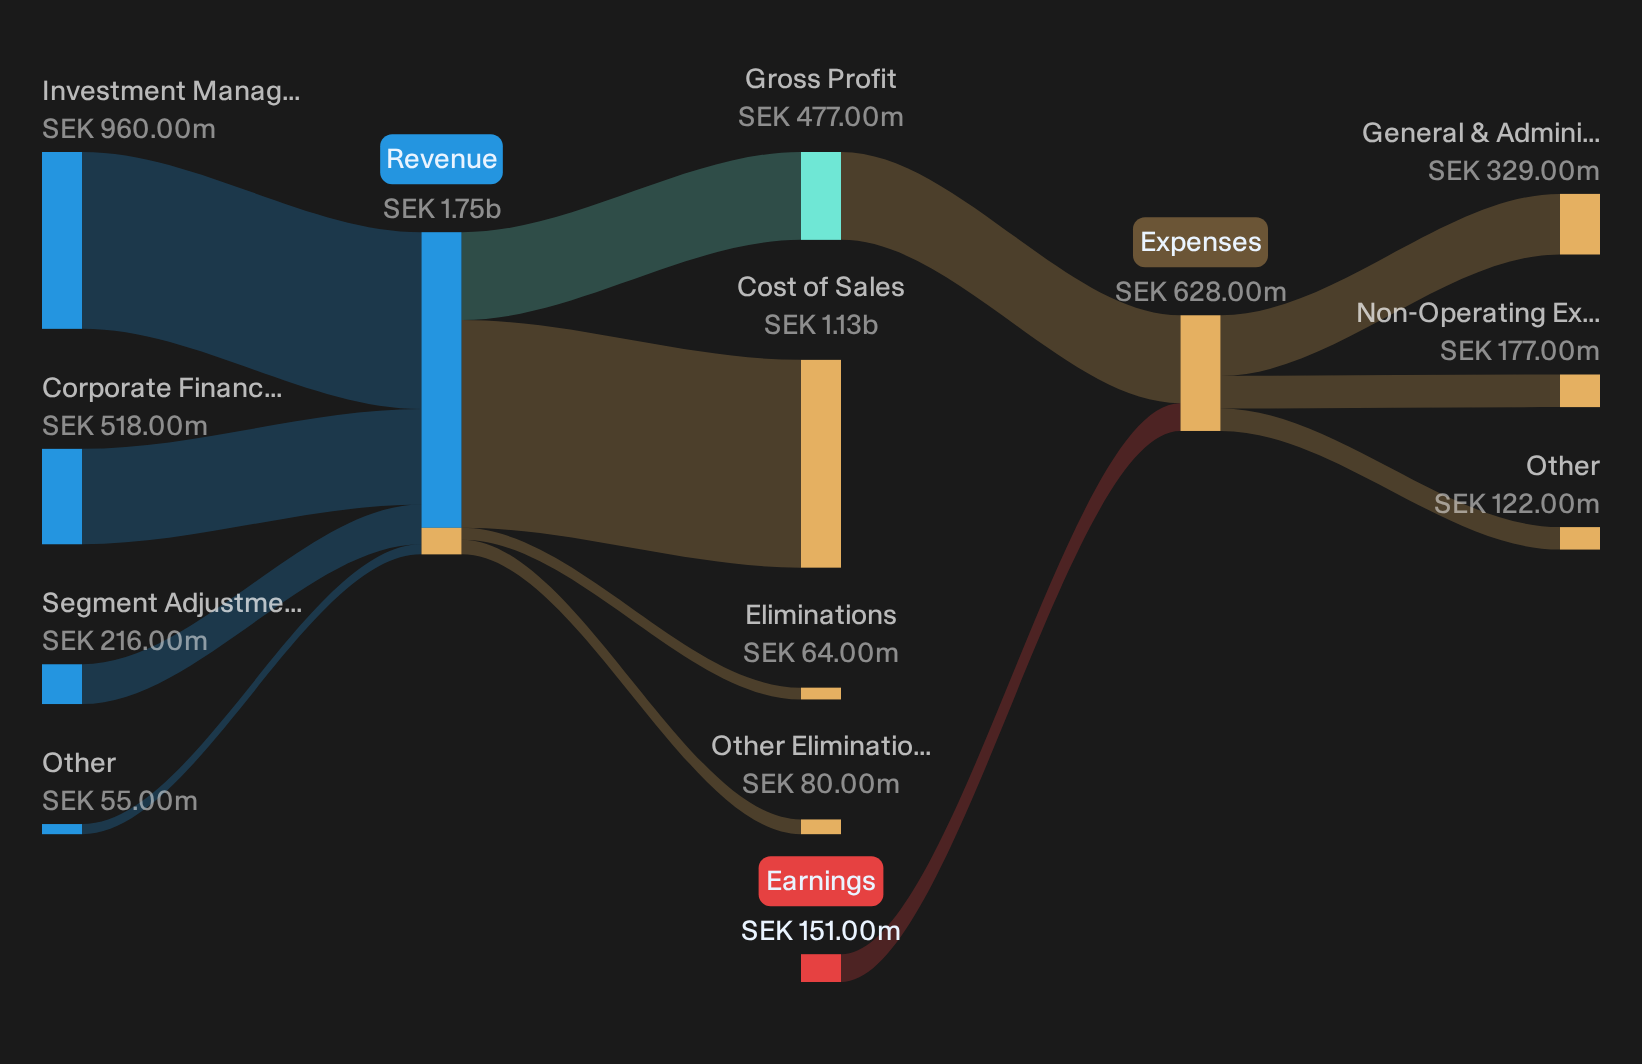
Catella runs a pan European real estate platform, earning about SEK960 million from Investment Management and SEK518 million from Corporate Finance, with smaller Other and adjustment items, and carries a market value of roughly SEK1.6 billion.
For investors watching UK related dealmaking, Catella offers a way to gain exposure to real estate transaction flows through a mix of advisory fees and fund management charges rather than pure investment banking risk.
Refocusing principal investments into seed and co investments alongside majority capital partners is intended to use the strong balance sheet to grow AUM and fixed fee income, which can support more stable revenue and earnings over time.
The real test for Catella is how that balance between transactional fees and recurring income holds up if a shift in real estate volumes persists.
If that balance looks important to your thesis, read the full narrative for Catella to see how Catella could benefit if volumes recover and fees accelerate.
FRP Advisory Group (AIM:FRP)
FRP Advisory Group is a London based business advisory firm tied into the UK M&A theme through its corporate finance and special situations work, generating £177 million from specialist advisory services and carrying a market value of about £283 million.
FRP Advisory Group provides focused exposure to UK advisory and deal activity, with earnings linked to restructurings, M&A and special situations that tend to vary with levels of corporate activity. A key consideration is how margins might be affected if there is any pressure on deal volumes or pricing.
Margin pressure is only half the story, so use the analysis report for FRP Advisory Group to see where FRP Advisory Group’s advisory mix could surprise next.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout setups, early momentum and under the radar stories can get caught quickly once attention hits. Scan them while it matters and get in early.
- Spot cash generative companies with room to move by running the list of solid balance sheet and fundamentals (10 results) before others price in those resilient balance sheets.
- Track where structural themes meet strong cash flows by scanning the 5 high quality undiscovered gems while these quieter opportunities are still flying below most radars.
- Review the 1 dividend fortresses to explore dividend-focused ideas before yield hunters crowd in and potentially affect those distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com