


Is ASM International (ENXTAM:ASM) A Bargain Following Its XP8 Vertos Launch?
ASM International (ENXTAM:ASM) has put its XP8 Vertos Flowable Carbon front and center, introducing what it calls the market's first PECVD flowable carbon film targeted at advanced semiconductor manufacturing.
That PECVD breakthrough lands at a time when ASM International’s share price has climbed to €844.6, with a 1-day share price return of 1.37% and a 7-day gain of 3.78% that hint at renewed momentum after a 90-day decline of 13.09%. A 71.99% 1-year total shareholder return and 165.79% 5-year total shareholder return highlight the long-run rewards for investors who stayed on board.
Compare ASM International’s PECVD push with other chip equipment plays by scanning our hand picked 85 AI infrastructure stocks that could also benefit from heavier compute and fabrication demand.
ASM International has bounced hard off recent weakness, yet the shares still trade well below analyst targets and an estimated fair value premium. Is that a simple opportunity, or is the discount the market’s way of flagging risk?
Most Popular Narrative: 25% Undervalued
The most followed narrative on ASM International pegs fair value at about €1,125.89, comfortably above the last close at €844.6. This frames the current price as a discount that leans on very specific growth drivers.
The ramp-up of advanced nodes (2nm and 1.4nm gate-all-around) in logic/foundry, driven by accelerating AI and high-performance computing needs, is structurally expanding ASM International's served available market and increasing deposition intensity, directly supporting above-industry revenue growth and resilient orders.
See why 67 investors see ASM International as 25% undervalued.
Result: Fair Value of €1,125.89 (UNDERVALUED)
Still, ASM International’s heavy reliance on a small group of advanced-node customers, combined with the uncertainty around China related export controls, could quickly undermine that undervalued thesis.
Find out about the key risks to this ASM International narrative.
Another View on ASM International’s Valuation
The DCF model used in the earlier fair value narrative presents ASM International as attractively priced. A second lens tells a different story. The SWS DCF model points to a value of about €550.74 per share, which is well below the current €844.6 price and implies the stock screens as overvalued on that cash flow framework. If one model indicates a discount and another indicates a premium, which set of assumptions should be trusted more?
Before relying on either view too heavily, it is worth seeing how that cash flow approach is built in practice, step by step, inside the Look into how the SWS DCF model arrives at its fair value..
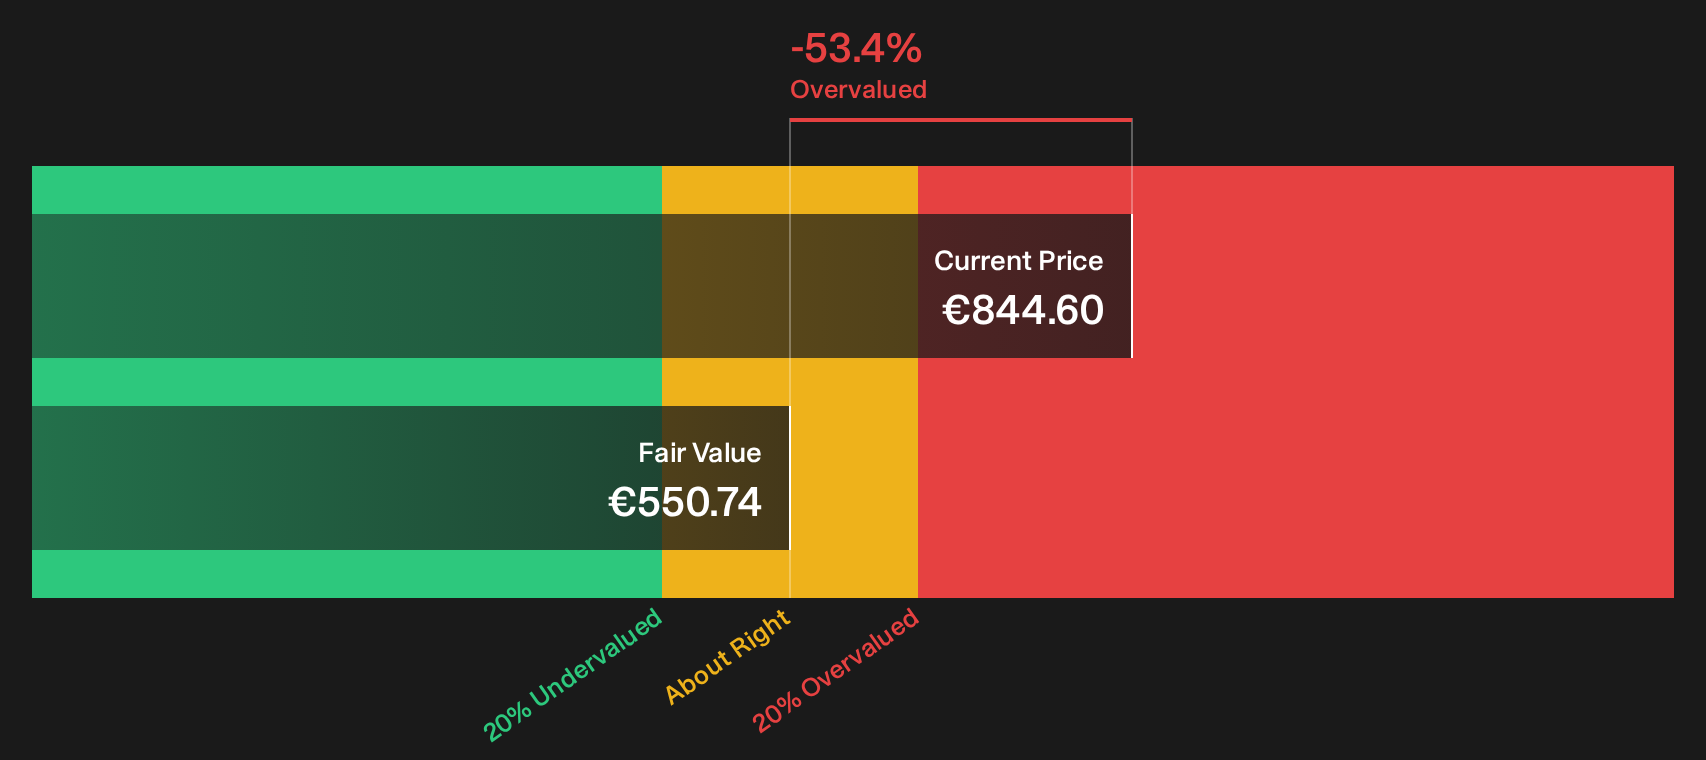
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASM International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seen enough optimism and concern around ASM International to feel conflicted about the next move? Act while the data is fresh in your mind and weigh both sides using the 4 key rewards and 1 important warning sign.
Looking for more ASM International investment ideas?
If ASM International has your attention, do not stop here. Use the Simply Wall Street Screener to uncover fresh opportunities that could round out your portfolio.
- Target higher potential by scanning a curated pool of quality opportunities through the 618 high quality undiscovered gems.
- Strengthen portfolio durability by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (201 results).
- Dial down portfolio risk and seek steadier rides across cycles with the 226 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com