


How Investors May Respond To StoneCo (STNE) Credit Expansion Plans
- StoneCo recently presented at the J. Safra Investment Conference 2026 in São Paulo, highlighting its integrated financial ecosystem and progress in micro, small, and medium-sized business payments and credit after an operational turnaround.
- Management’s emphasis on scaling the credit operation within this MSMB ecosystem, even with Brazil’s tougher backdrop, underlines how StoneCo is focusing on higher-risk, higher-reward lending to deepen merchant relationships.
- We will look at how this push to expand StoneCo's MSMB credit business reshapes the existing investment narrative investors have been tracking.
Scan beyond StoneCo and see how other merchant focused lenders are positioned by running our curated screener of 32 high quality undervalued stocks with resilient balance sheets and disciplined risk profiles.
StoneCo Investment Narrative Recap
To own StoneCo, you need to believe its MSMB ecosystem in Brazil can keep deepening client relationships through payments, banking, and higher risk credit while still controlling funding and loss costs. The key short term swing factor is how fast management scales the loan book without letting provisions erode the current net margin profile and the quality of earnings.
The recent conference commentary mainly reinforces that existing path rather than changing it. The biggest near term risk still sits in credit quality and funding, especially with interest payments not well covered by earnings and no customer deposits. Any rapid portfolio expansion could quickly pressure returns if the macro backdrop stays tough.
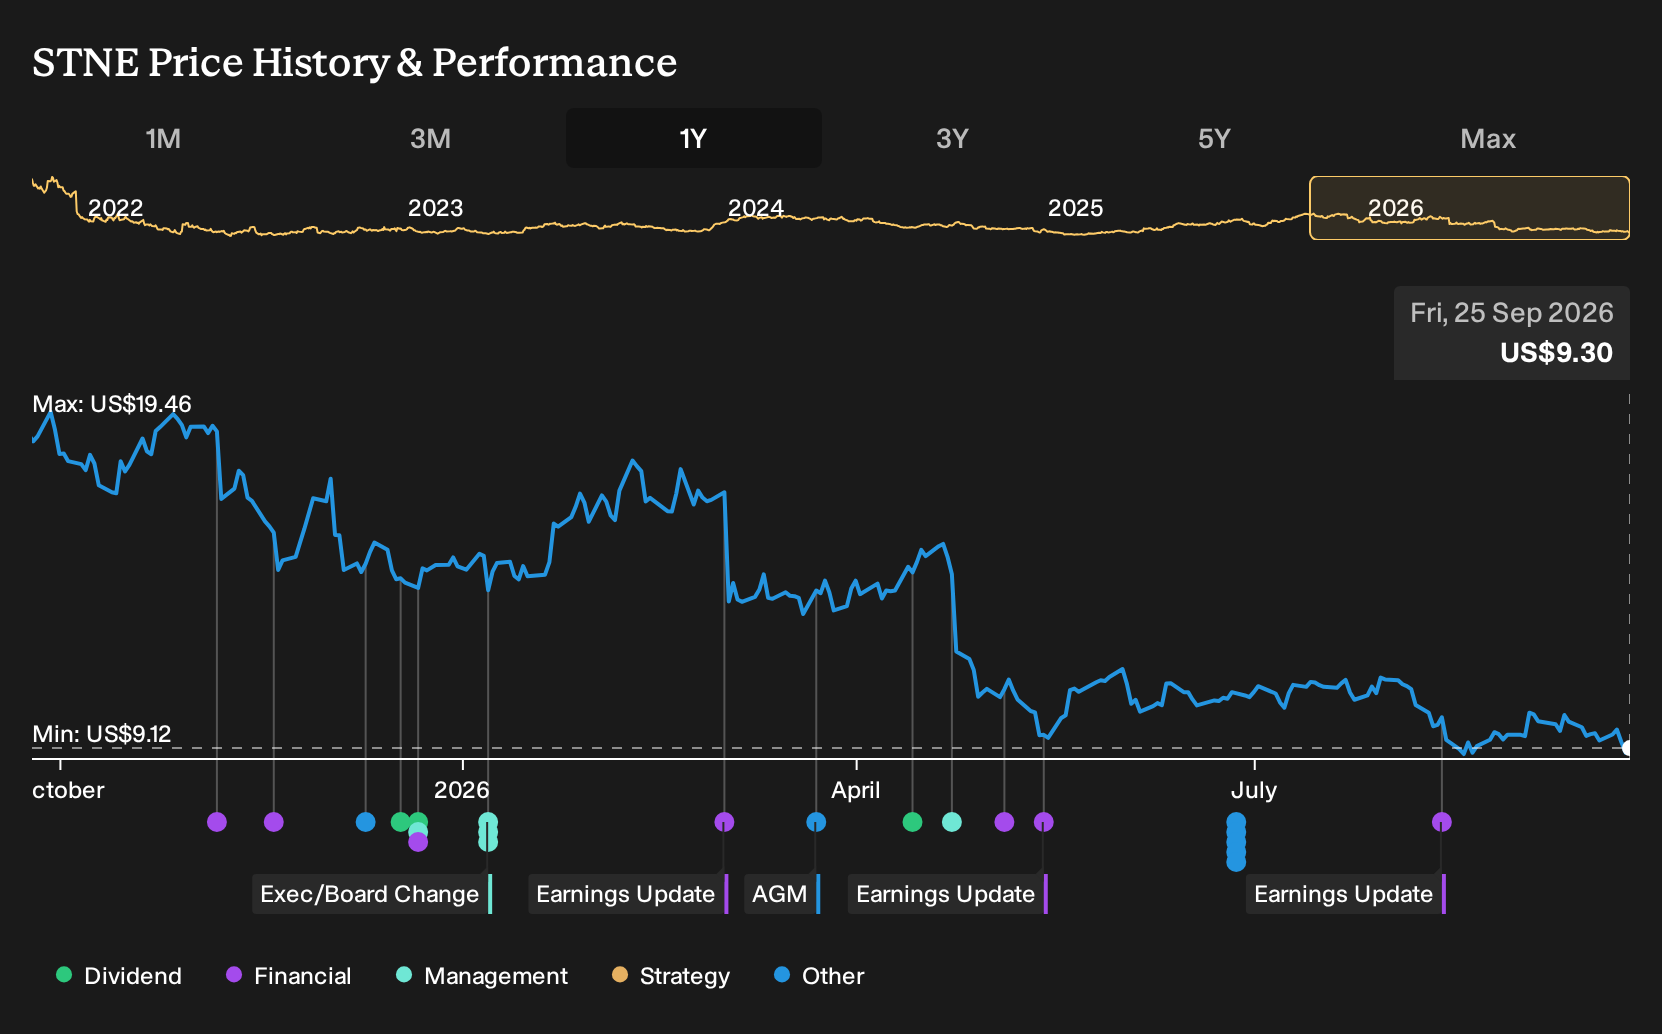
The options activity around the October 16, 2026 call with elevated implied volatility ties directly back to this operating uncertainty. Traders appear focused on a potential sharp move in response to how the market digests StoneCo updates on credit expansion, MSMB payment trends, and any fresh commentary on provisions or funding costs through the rest of 2026.
For you as an investor, the more important point is not the options pricing itself but what it suggests about sensitivity to execution on this credit pivot. Mixed analyst expectations on future earnings, combined with strong recent profit growth and a low P/E multiple, mean that any new data point on TPV momentum or loss behavior in the MSMB loan book could quickly reset sentiment in either direction.
StoneCo's narrative projects R$17.4b revenue and R$2.8b earnings by 2029. This assumes 8.7% yearly revenue growth and a R$0.7b earnings decline from R$3.5b today.
Uncover how StoneCo's fair value indicates a 64% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One big disagreement sits around disruption risk from digital currencies. The lowest analysts lean into this, assuming slower revenue at R$14.9b and earnings closer to R$2.0b by 2029, versus consensus at R$17.4b and R$2.8b. Both views predate StoneCo’s conference update, so you should expect narratives to evolve.
Explore 4 other StoneCo fair value estimates, including one that indicates there could be up to 14% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your StoneCo research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for StoneCo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StoneCo's overall financial health at a glance.
Looking For More Investment Ideas Beyond StoneCo?
Once you have a view on StoneCo, it can help to compare it with other opportunities that share similar qualities or offer a different risk profile altogether.
- For investors who want income to be front and center, scan companies that combine yield with staying power through 8 dividend fortresses.
- If capital preservation matters more than chasing every rally, filter for steadier performers using the 30 resilient stocks with low risk scores.
- When you are hunting for quality that the wider market has not fully focused on yet, start with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com