


Does Strong Buy Rating Change The Bull Case For Owens Corning Stock?
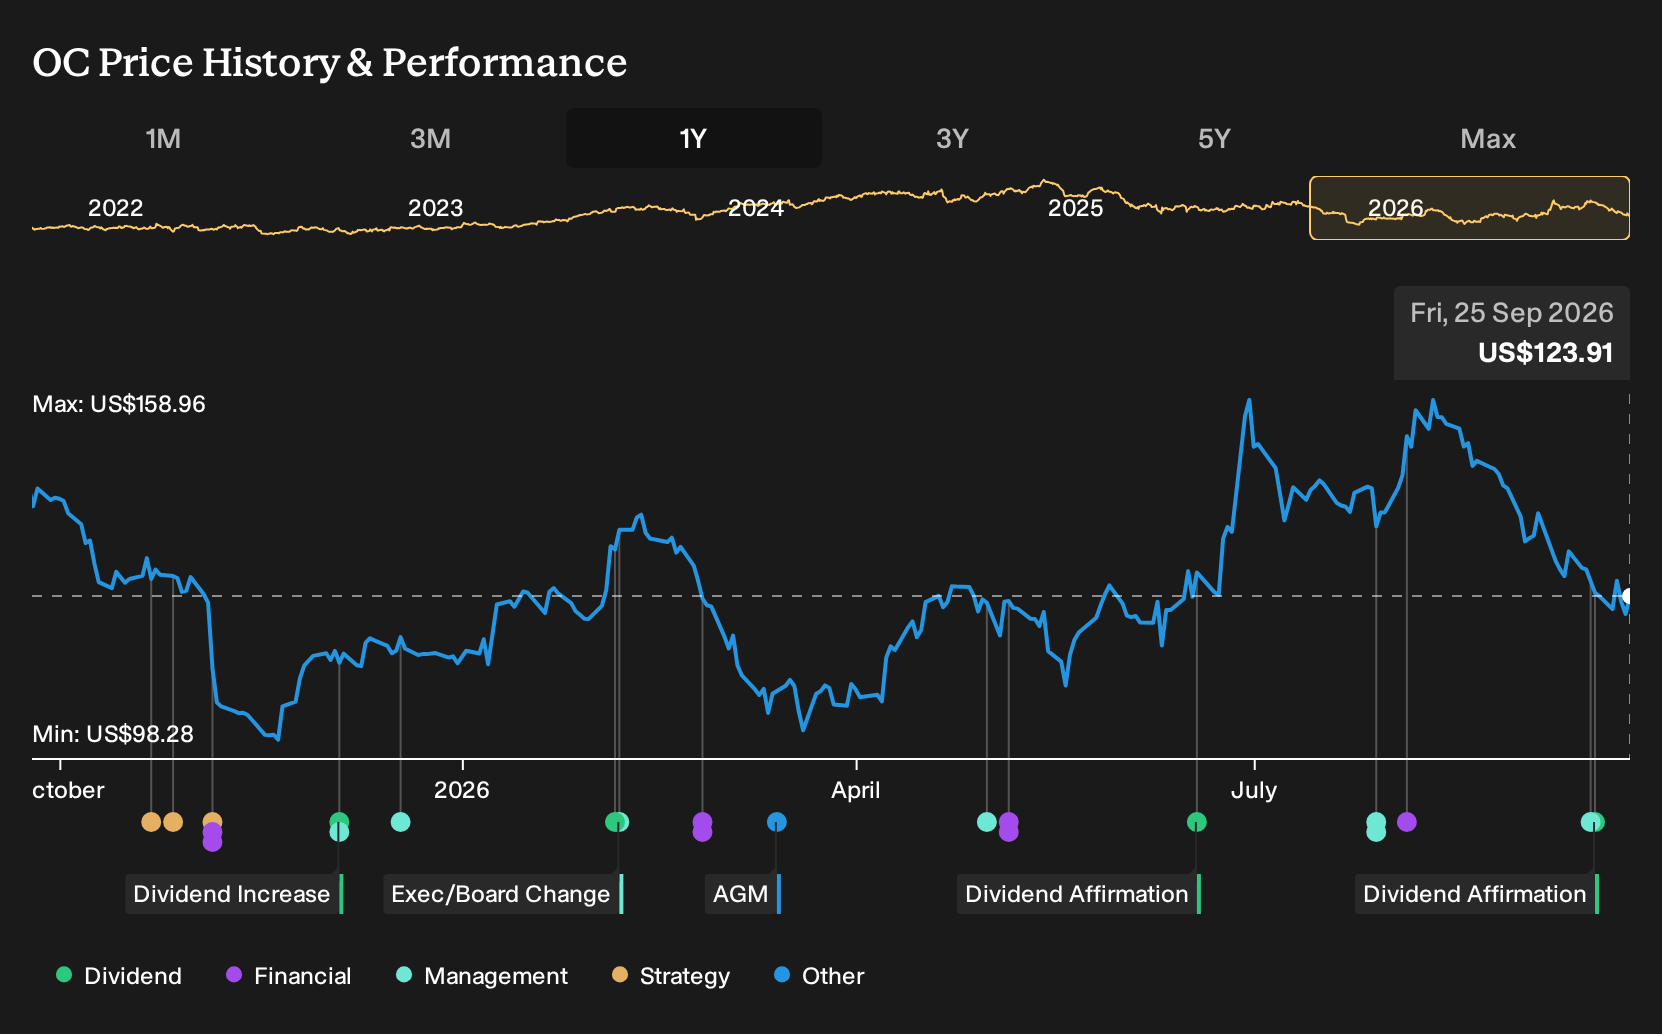
- Owens Corning announced a quarterly cash dividend of US$0.79 per share, payable on November 5, 2026, and recently added former Freddie Mac CEO Michael DeVito to its Board, with roles on the Audit and Finance and Technology Committees.
- The dividend affirmation and the appointment of a director with deep housing finance and home lending experience highlight management’s focus on capital discipline and oversight as the business faces expectations for lower near term earnings and revenue.
- We will look at how Owens Corning’s investment narrative is shaped by the affirmed dividend, as analysts still expect softer near term earnings.
Owens Corning Investment Narrative Recap
Owens Corning appeals to investors who believe in long term demand for energy efficient roofing, insulation, and doors, even as near term housing and renovation cycles stay choppy. The business leans heavily on North American repair and remodel activity and on premium products. That creates a clear story but also concentrates exposure.
The key short term swing factor is how pricing and volumes hold up in insulation and roofing while markets work through excess capacity and softer housing starts. The recently affirmed dividend does not change that core risk in a material way. It mainly underscores management’s confidence in current cash generation.
Among the recent updates, the dividend declaration to US$0.79 per share feels most relevant to the near term thesis. It points to an emphasis on returning cash even while earnings and revenue are expected to be softer in the coming quarter. For you, the question is whether that payout fits with your risk tolerance.
Owens Corning carries a high level of debt and the dividend is not well covered by current earnings, while the business is still unprofitable. That combination raises execution stakes around cost control, pricing discipline, and capacity utilization. If those levers do not deliver as planned, the board may have less flexibility around future capital returns.
Owens Corning's current consensus story points to revenues of US$11.0b and earnings of US$1.9b by 2029. These figures are built on analysts’ assumption of 3.7% yearly revenue growth and an earnings swing of roughly US$2.3b from a loss of US$429.0m today to those forecast earnings.
Uncover why Owens Corning's fair value indicates a 42% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Owens Corning, the real swing factor in the alternate story is slower volume recovery. The most cautious analysts were only penciling in about US$11.0b of revenue and US$1.7b of earnings by 2029 before this dividend and board news. This reflects a much more restrained outlook that could shift once these updates filter into their models.
Explore 3 other Owens Corning fair value estimates, including one that suggests it could be worth just $145.03.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Owens Corning research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Owens Corning. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Owens Corning's overall financial health at a glance.
Looking for more investment ideas beyond Owens Corning?
Once you have formed a view on Owens Corning, it can help to compare it with other opportunities that fit your income, risk, and quality preferences. The Simply Wall St Screener can surface a range of different profiles so you can build a shortlist that matches how you like to invest.
- If you want income with staying power, start with companies that combine yield with balance sheet resilience by reviewing the 8 dividend fortresses.
- If your focus is on quality at a reasonable price, narrow in on financially strong businesses trading below intrinsic estimates through the 32 high quality undervalued stocks.
- If you prefer to keep risk in check, build a watchlist from companies with steadier fundamentals and fewer red flags using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com