


Is Emerson Electric (EMR) Fully Valued On Its New Qatar Service Center Plan?
Emerson Electric (EMR) just put a spotlight on the Middle East and Africa by committing to a new 3,500-square-meter automation service center in Qatar, tying operational investment directly to its current stock story.
Emerson Electric is already trading at US$158.23, and that share price move sits on top of a 16.5% year to date share price return and a 24.97% total shareholder return over the past year. The new Qatar service center adds another clear catalyst to a multi year total shareholder return of 72.73% that suggests momentum is still building rather than fading.
Scan for other industrial and automation stocks that are showing similar regional expansion momentum by jumping into our hand picked 40 power grid technology and infrastructure stocks.
Bulls argue Emerson Electric’s Qatar build out justifies a premium. Bears see a mature industrial paying up for growth that may already be reflected in the current P/E. The numbers will show which side has more support.
Most Popular Narrative: 7.9% Undervalued
On this view, Emerson Electric’s fair value of $171.81 sits above the last close at $158.23. The narrative focuses on whether long cycle automation demand and software economics can close that gap over time.
The accelerating adoption of digital automation and artificial intelligence solutions in global industrial markets is fueling strong demand for Emerson's advanced software platforms and AI-enabled products, such as Ovation 4.0 and Nigel AI adviser, which is resulting in robust order growth and positions the company for sustained revenue expansion.
Find out how 53 investors see Emerson Electric as 8% undervalued.
Result: Fair Value of $171.81 (UNDERVALUED)
Still, if LNG and power contracts slow or software integrations underperform, Emerson Electric’s premium P/E narrative could quickly look stretched.
Find out about the key risks to this Emerson Electric narrative.
Another View: Cash Flow Model Paints Emerson Electric As Expensive
The earlier narrative framed Emerson Electric as roughly 7.9% undervalued using analyst targets and earnings based assumptions. A different lens tells a very different story.
Simply Wall St's DCF model, which focuses on projected cash flows rather than P/E, estimates a future cash flow value of $80.25 per share. Emerson Electric is trading at $158.23, so the stock price is roughly double that estimate, which points to a meaningful valuation gap that buyers and holders both need to weigh.
If earnings based fair value and cash flow based value are this far apart, the key question for any investor is simple: which set of assumptions feels closer to how Emerson Electric will actually convert its projects and software pipeline into cash over time?
Look into how the SWS DCF model arrives at its fair value.
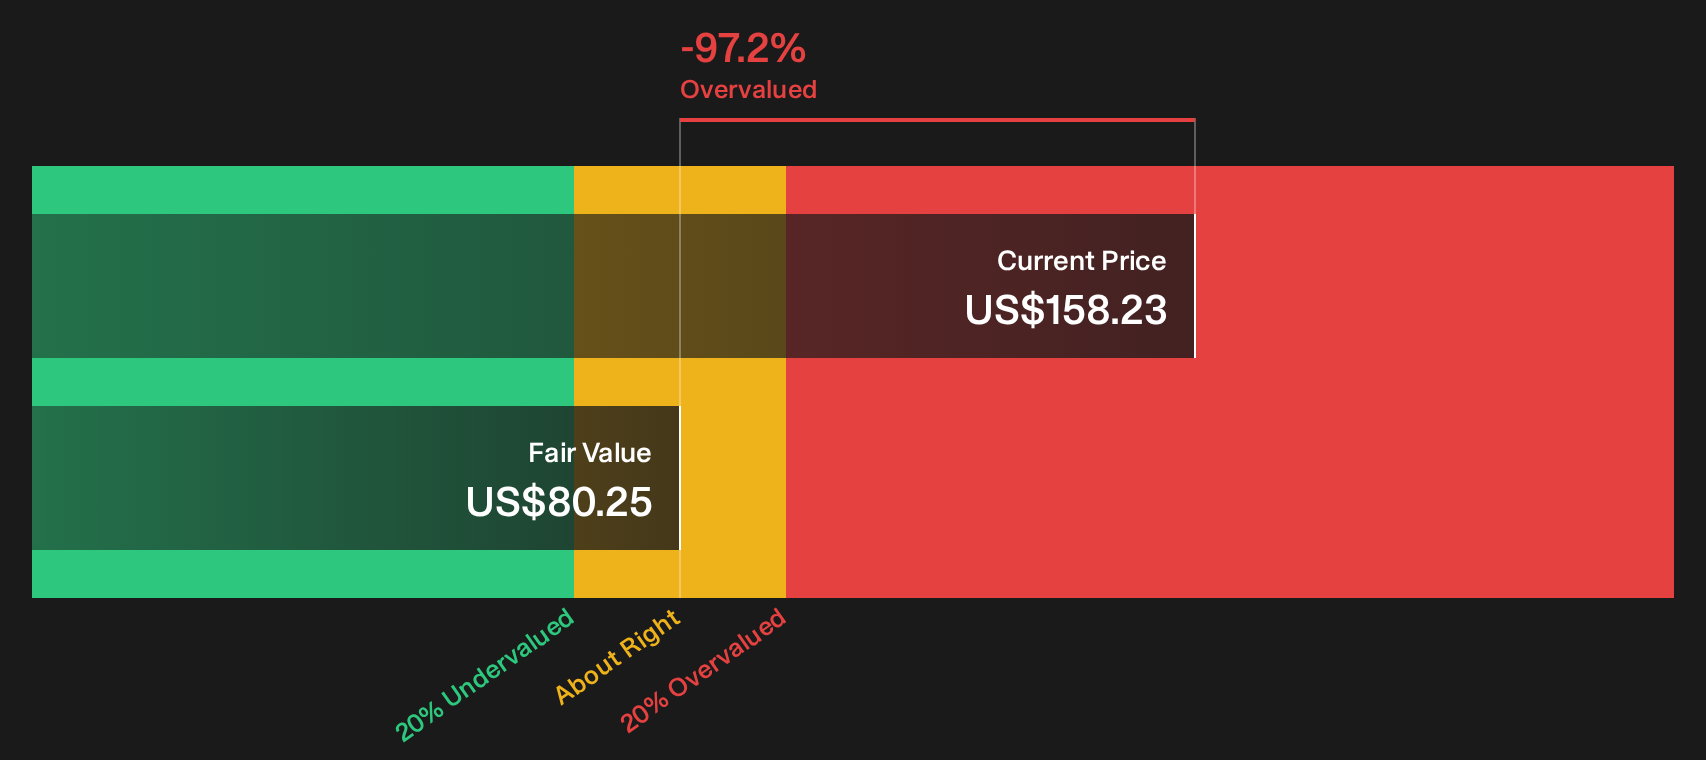
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Emerson Electric for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of conflicting signals around Emerson Electric here, so move quickly to review the underlying data, stress test your own assumptions, and weigh both upside and downside using our breakdown of 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Emerson Electric?
Do not stop with Emerson Electric when there are other potential opportunities to review. Use the Simply Wall St screener to pressure test your next move.
- Target steady income by reviewing companies that feature 8 dividend fortresses for investors who want yield with substance behind it.
- Pursue quality at a fair entry point by scanning our 32 high quality undervalued stocks backed by strong fundamentals and healthier balance sheets.
- Spot opportunities the crowd has not fully focused on yet by working through our 16 high quality undiscovered gems
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com