


New CFO Hire Might Change The Case For Investing In Pentair Stock (PNR)
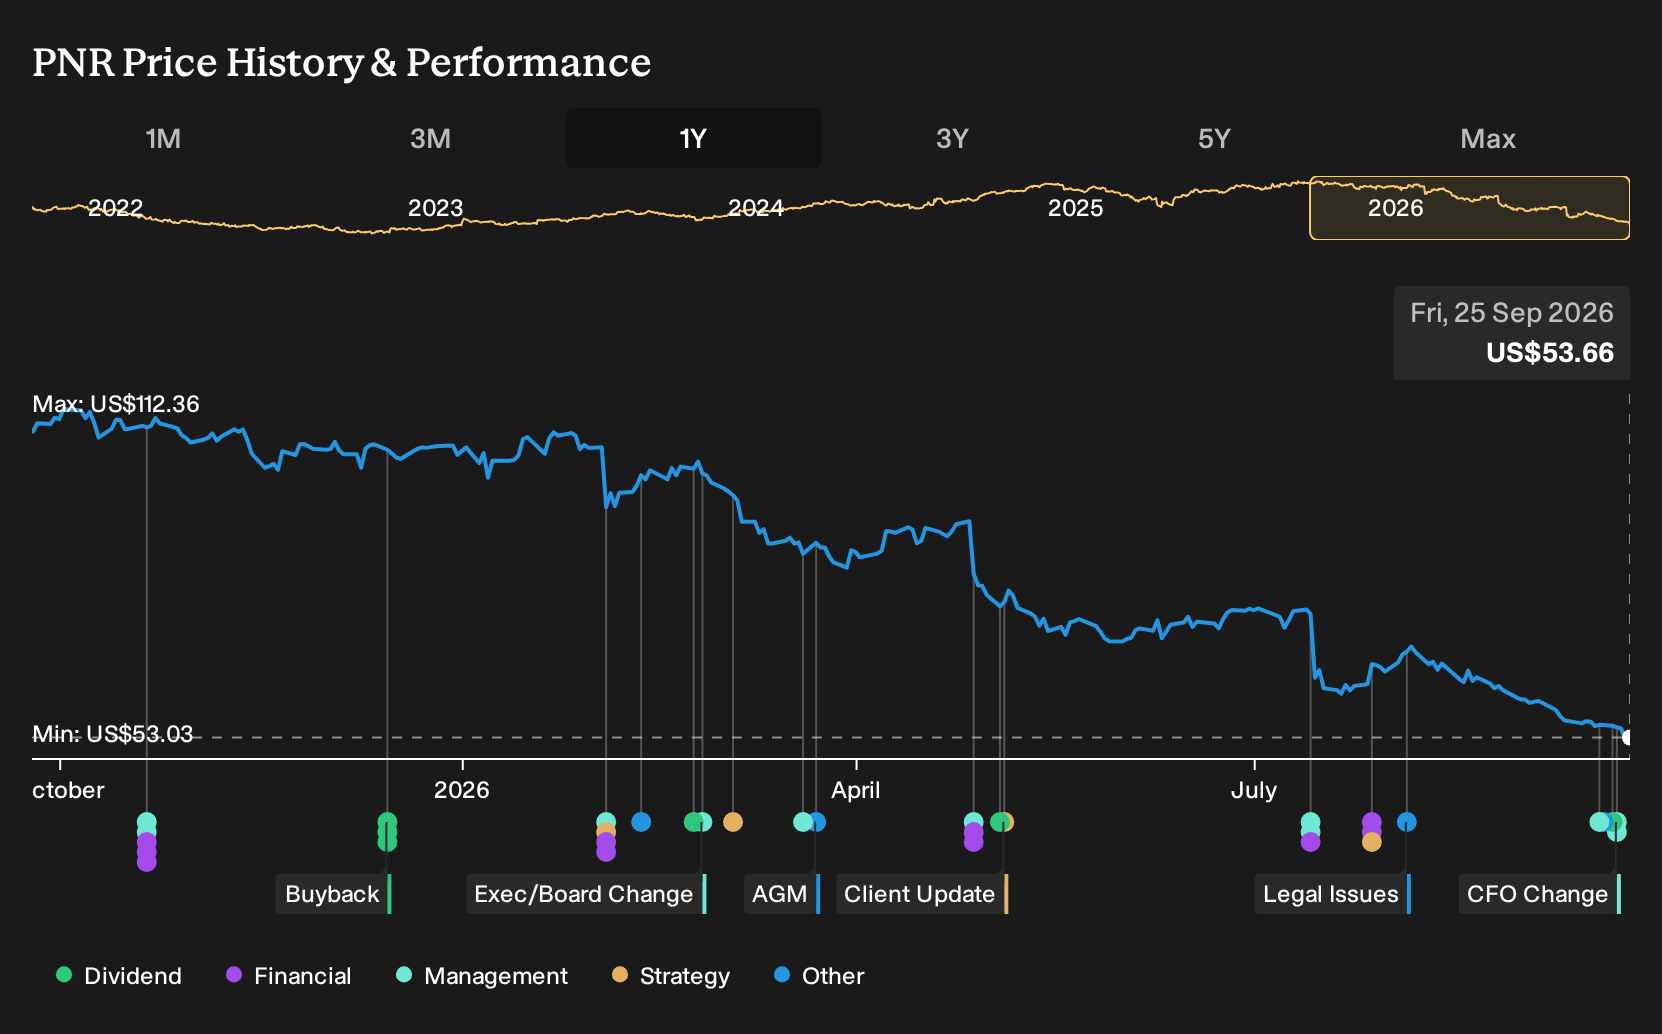
- Pentair announced that Robert W. Hau, 60, will become Chief Financial Officer and Executive Vice President on November 1, 2026. This will follow a transition from interim CFO Bob Fishman and build on Hau’s recent appointment as Senior Vice President, Finance.
- The hire brings Pentair a finance leader with CFO experience at Fiserv, TE Connectivity, Lennox International, and Honeywell’s aerospace division. This may matter for how the business funds portfolio reshaping, the Taco acquisition, and cash flow priorities.
- We will now look at how Pentair's investment narrative could be influenced by Hau's appointment as Chief Financial Officer.
Compare Pentair's setup with a curated group of potential undervalued opportunities by scanning the 32 high quality undervalued stocks that may also be wrestling with leadership changes and index moves.
Pentair Investment Narrative Recap
For an investor to stay with Pentair, the core belief is that its water technologies, HVAC and data center exposure, and margin tools can offset the Pool segment’s volatility and the hit from July’s guidance cut. The short term hinge point is whether Pool stabilises after channel destocking so earnings and confidence in guidance stop resetting.
The biggest near term risk still sits in Pool and in the legal and reputational overhang from securities class actions tied to the guidance change. Hau’s arrival as CFO looks important for tighter capital deployment around Taco and cash conversion, although the appointment alone does not change the operational risk profile.
The most relevant recent update alongside the CFO news is Pentair’s decision to maintain its regular quarterly dividend of US$0.27 per share, payable on 6 November 2026. That indicates management is keeping a cash return in place even as shares have fallen sharply over the past year and the business absorbs Pool weakness.
For you as a shareholder, the payout sits against legal claims, high debt, index removal and heavier investment around Taco and Flow. The key question is whether Pentair can keep funding the dividend while executing on HVAC and data center initiatives and absorbing any litigation or Pool related shocks without stretching the balance sheet too far.
Pentair's narrative projects US$4.5b revenue and US$899.7m earnings by 2029. This assumes 3.9% yearly revenue growth and an earnings increase of about US$264m from US$635.5m today.
Uncover why Pentair's fair value indicates a 44% potential upside to its current price before momentum narrows that difference.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Pentair’s transformation savings as the swing factor. Before this CFO news, they were pencilling in revenue of about US$4.6b and earnings near US$992.2m by 2029. That is far above the baseline view. Use this spread to test your own stance and explore alternative narratives.
Explore 4 other Pentair fair value estimates, including one that suggests there may be as much as 81% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Pentair research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pentair. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pentair's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pentair?
If the Pentair story has sharpened your view on risk, rewards and leadership change, it can be useful to set it alongside other opportunities that share similar qualities or contrasts. The Simply Wall St Screener helps you do that quickly, using filters that highlight different types of stocks so you can pressure test your thesis instead of relying on a single case study.
- For investors who care most about balance sheet strength and fundamentals, start with a list of solid balance sheet and fundamentals (24 results). It can act as a quality anchor for your watchlist.
- If income is your priority, compare Pentair’s payout profile with a 8 dividend fortresses. This screens for higher yielding companies with resilient shareholder returns.
- To widen the opportunity set beyond well known tickers, scan a 16 high quality undiscovered gems. It focuses on under the radar businesses with strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com