


AMETEK (AME) Could Be 10% Undervalued As FARO INSIGHT Launches Rovi I.1
AMETEK (AME) has moved into focus after Manifold Tech Limited agreed to work with its FARO INSIGHT unit on Rovi i.1, a mobile reality capture tool for field use.
AMETEK shares have been climbing, with a 7 day share price return of 5.51% and a year to date gain of 19.89%. Total shareholder return over 1 and 5 years sits at 35.35% and 107.28% respectively, suggesting momentum has been building around the story.
Scan for other AMETEK style industrials riding similar tech partnerships by checking the hand picked 40 power grid technology and infrastructure stocks in the same broader infrastructure and hardware space.
Bulls view AMETEK as a high-quality industrial company benefiting from technology partnerships at a fair entry point. Bears see a crowded premium and elevated sentiment. Which case do the current valuation markers appear to support next?
Most Popular Narrative: 10% Undervalued
AMETEK last closed at $250.74 while the most widely followed narrative framework points to a fair value of about $278.33 using a 9.5% discount rate. That gap puts the focus squarely on whether the growth platforms that matter most can deliver enough cash generation to close it.
Growing exposure to AI driven semiconductor and data center infrastructure, supported by strong orders and design wins in optics, metrology, embedded computing and power simulation, is expected to support multi-year revenue growth and earnings from these higher value instrumentation and electronics platforms.
See why 17 investors see AMETEK as 10% undervalued.
Result: Fair Value of $278.33 (UNDERVALUED)
Still, if AMETEK struggles to integrate acquisitions like Indicor, or if investors cool on premium P/E multiples for industrials, that bullish fair value narrative could fade fast.
Find out about the key risks to this AMETEK narrative.
Another View: AMETEK On Earnings Multiples
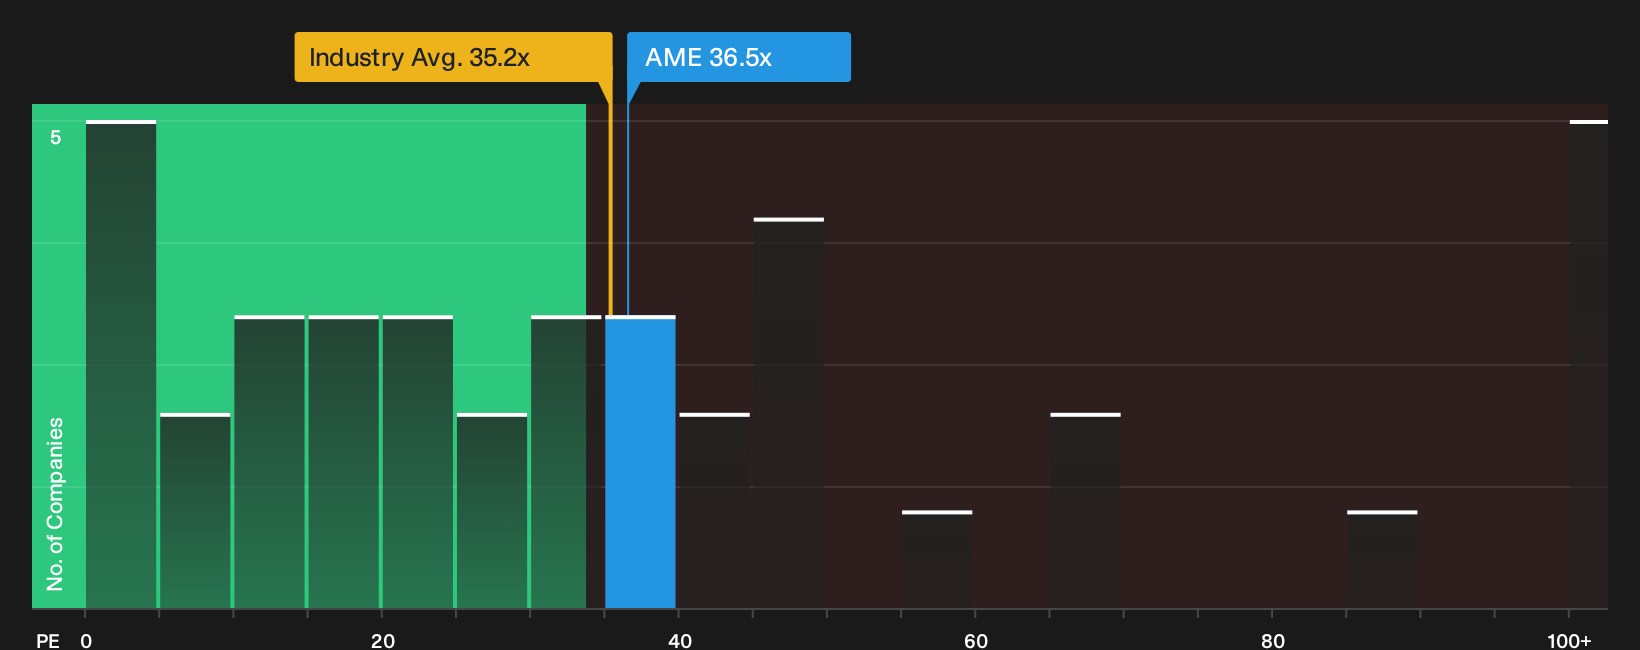
The AMETEK fair value story built around a $278.33 target looks supportive, yet the simple earnings multiple tells a sharper story. The stock trades on a P/E of 36.5x, above the US Electrical industry on 35.2x and the fair ratio of 27.7x, which points to valuation risk if sentiment cools.
Against peer companies on 39.5x, AMETEK screens cheaper on this metric. Investors weighing upside versus downside need to decide which reference point carries more weight if growth or enthusiasm fades first.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around AMETEK is split. Move quickly to review the underlying data, weigh the upside case, and test the 2 key rewards.
Looking for more AMETEK style investment ideas?
If AMETEK has your attention, do not stop here. Fresh opportunities keep moving, and you risk missing them if you only track one ticker.
- Target quality at a discount by scanning the 32 high quality undervalued stocks that pair stronger fundamentals with prices that still trail their underlying business strength.
- Lock in cash flow potential by reviewing the 8 dividend fortresses that combine higher yields with an emphasis on resilience and income consistency.
- Prioritise resilience over drama by focusing on the 30 resilient stocks with low risk scores designed to surface businesses with steadier risk profiles and sturdier balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com