


AI Datacom Growth Could Be A Game Changer For Amphenol Stock (APH)
- Amphenol recently reported record Q2 2026 sales and earnings, supported by strong operating cash flow and broad demand for its high speed, power and fiber interconnect products.
- The most striking detail is that AI related IT datacom already accounts for 43% of Amphenol’s sales and grew 63% organically year over year, which highlights how central data center programs have become to the business.
- We will examine how Amphenol’s investment narrative evolves as record earnings intersect with rapid AI driven IT datacom demand.
Scan beyond Amphenol and map out the wider AI infrastructure story by reviewing our hand picked 85 AI infrastructure stocks now shaping the build out of next generation data centers.
Amphenol Investment Narrative Recap
For an investor to stay with Amphenol, the key belief is that demand for high speed copper, fiber and power interconnects in AI focused IT datacom, defense and industrial equipment can stay healthy. The record Q2 2026 report, with strong cash generation, supports that operating view. The near term swing factor is whether AI related IT datacom orders can keep compounding from already high levels without sudden pauses.
The biggest operational risk right now is that any cooling in AI infrastructure spend, or delays in data center projects, would hit the 43% of sales tied to IT datacom disproportionately. Higher ongoing taxes and a high debt load add less visible pressure, since they can cap how much of that strong top line shows up as net income.
The most relevant recent data point is management’s indication that AI related IT datacom grew 63% organically year over year and now makes up 43% of Amphenol sales. That mix shift means the business is more tightly wired to AI data center build outs than it was even a year ago. It also means operational execution in this segment now matters more than any single end market.
Institutional MoneyFlows pointing to sustained interest in Amphenol tie back to this AI centric thesis. Record Q2 2026 earnings, high 20s adjusted operating margins and improving profitability at acquired operations give the AI story a stronger financial base, but they do not remove risk. A moderation in that AI related growth curve, even from a high level, would quickly test how much optimism is embedded in the current P/E multiple.
Amphenol's current earnings are reported at US$5.1b, with analysts forecasting US$10.8b of earnings and US$50.7b of revenue by 2029. This outlook rests on an assumed 20.5% yearly revenue growth rate and implies earnings would need to be a little more than double today's level, rising by about US$5.7b.
Uncover why Amphenol's fair value indicates an 18% potential upside to its current price that could narrow quickly.
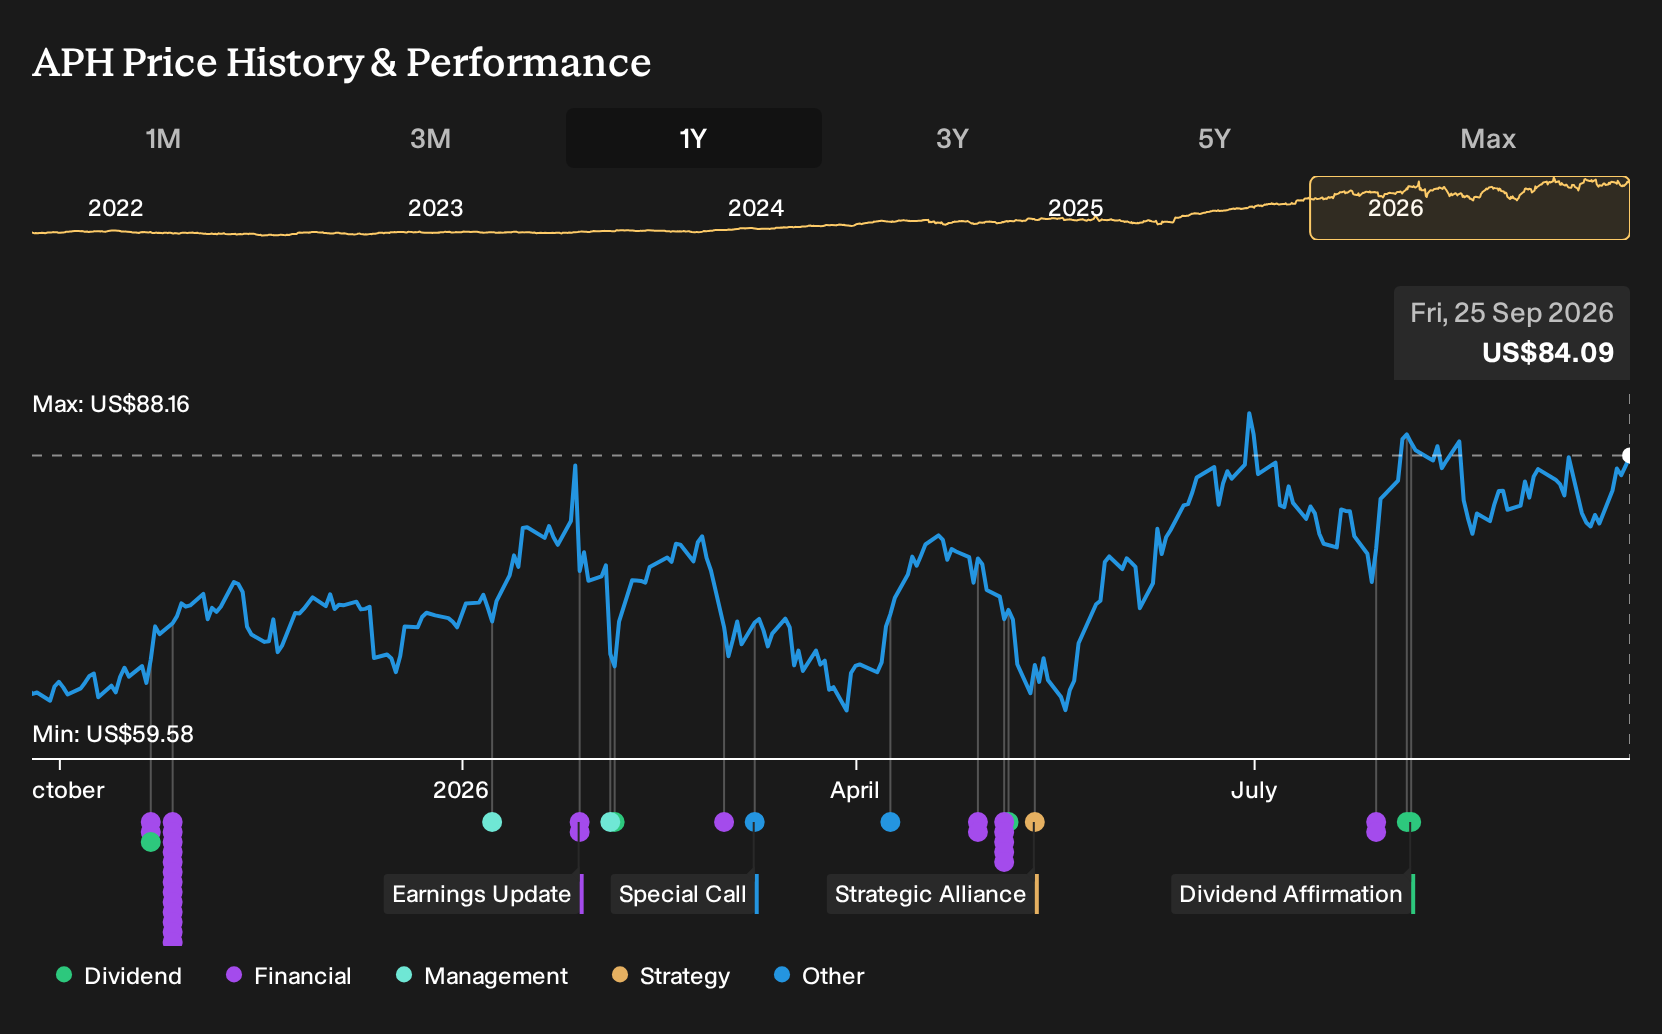
Exploring Other Perspectives
One alternate view on Amphenol leans hard into margin risk. Those analysts worry that rising R&D, regulatory and supply chain costs could squeeze profitability even as AI spend ramps. Before this Q2 2026 news, the most cautious projections were for revenue of US$39.5b and earnings of US$7.2b by 2029, a much cooler story than consensus. That spread shows how far opinions can stretch. Treat this quarter as a fresh datapoint and explore how both narratives might now shift.
Explore 6 other Amphenol fair value estimates, including one that suggests it could be worth just $87.69.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amphenol research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amphenol. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amphenol's overall financial health at a glance.
Looking For More Ideas Beyond Amphenol?
If the Amphenol story has sharpened your thinking around earnings quality, balance sheets and AI infrastructure, you can broaden that lens with a few focused stock searches using the Simply Wall St Screener.
- For investors who want to back financially stronger businesses while managing downside risk, start with a 30 resilient stocks with low risk scores that already clear our resilience checks.
- If cash strength and cleaner accounts matter most to you, filter for companies with sturdy finances and consistent fundamentals using the list of solid balance sheet and fundamentals (24 results) as your next step.
- Those hunting for underfollowed opportunities can scan a 16 high quality undiscovered gems that combine quality fundamentals with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com