


Does Leismer Expansion Progress Change The Bull Case For Athabasca Oil Stock?
- Athabasca Oil is advancing expansion of its long life Leismer thermal oil sands project in Alberta toward a planned capacity of 40,000 bbl/d by the end of 2027. The company aims to build on its low cost production base and link capital intensive projects more directly to self funded development.
- The focus on capital efficiency at Leismer and the role of Athabasca Oil’s Duvernay light oil assets highlight how management is trying to connect balance sheet strength, long life reserves and operating scale into a tighter, self funded growth model rather than relying heavily on external financing.
- We will now look at how Athabasca Oil’s push to grow low cost Leismer output could reshape the broader investment narrative around the stock.
Scan beyond Athabasca Oil and identify other producers building scale on strong balance sheets with the hand picked list of solid balance sheet and fundamentals (7 results).
Athabasca Oil Investment Narrative Recap
To own Athabasca Oil, you need to believe the thermal oil sands and Duvernay assets can convert a heavier capital program into higher production, stronger cash generation and, over time, a cleaner balance between growth and returns. The Leismer expansion is the near term proof point because it aims to increase low cost volumes without leaning hard on external funding.
The key short term catalyst is simple. Athabasca Oil needs to keep Leismer, Corner Phase 1 and Duvernay spending on schedule and on budget so free cash flow pressure does not deepen. The biggest risk is that overruns or delays extend the period of tighter cash and keep the execution narrative front and center.
Recent communication around the Leismer expansion toward 40,000 bbl/d by the end of 2027 is the announcement most tied to this story. Management is targeting capital efficiency of about $25,000 per flowing barrel and a sustaining breakeven near US$45 WTI. If delivered as outlined, this would extend the low cost production base.
Framed against the current catalysts, that Leismer plan sits alongside Corner Phase 1 and the Duvernay drilling program as the core operational drivers investors watch. The whole setup relies on execution, because a larger thermal platform, incremental Duvernay liquids and the existing credit and tax pool position only translate into better outcomes if development milestones hold together.
Athabasca Oil’s current analyst narrative points to revenues of about CA$3.1b and earnings of CA$687.9 million by 2029, based on an assumed 34.2% yearly revenue expansion and an earnings increase of roughly CA$459 million from CA$228.7 million today.
Uncover why Athabasca Oil's fair value indicates a 23% potential upside to its current price before that discount feels fully priced in.
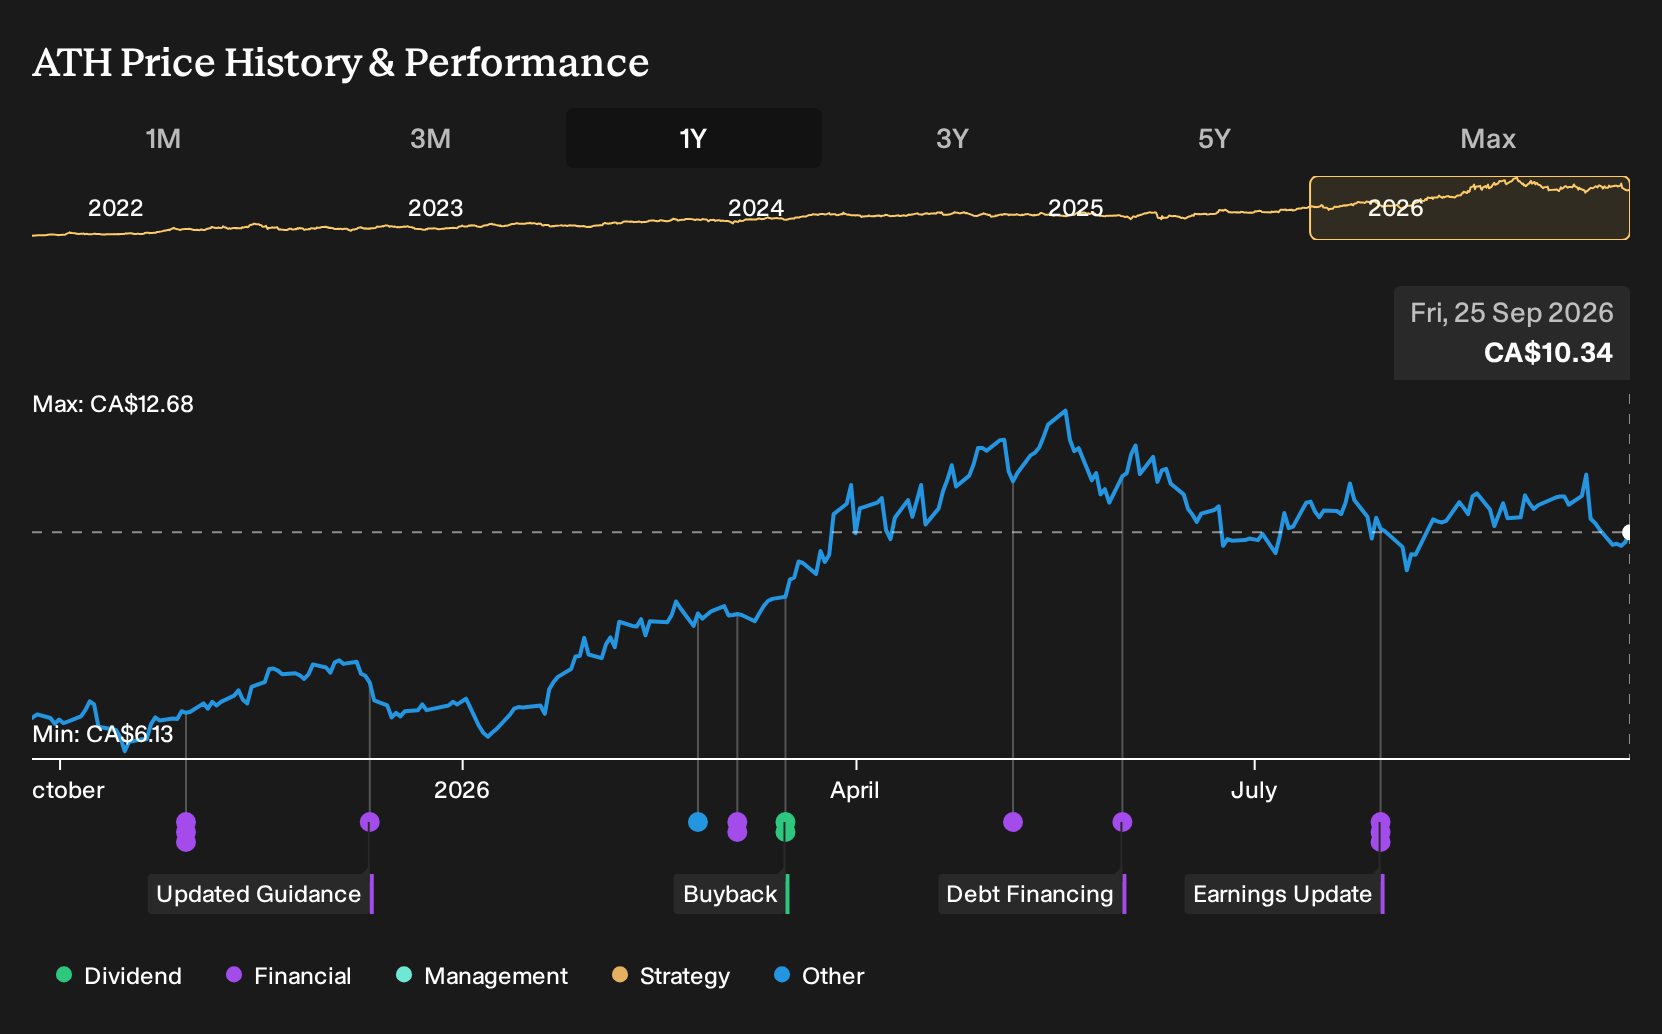
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster in a tight CA$12.73 to CA$13.44 range, which shows how even a small sample can produce different takes on Athabasca Oil. These estimates also pre date recent project updates, so reassess them in the context of execution risk at Leismer and Corner and wider market sentiment.
Explore another Athabasca Oil fair value estimate, including one that suggests it could be worth just CA$12.73!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Athabasca Oil research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Athabasca Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Athabasca Oil's overall financial health at a glance.
Looking for more Athabasca Oil style investment ideas?
If the Athabasca Oil story has you thinking about balance sheets, production profiles and where to put fresh capital to work, it can help to widen the lens and scan for other businesses that fit your preferred mix of quality and risk.
The Simply Wall St Screener lets you filter the market using the same kind of criteria you have just seen applied to Athabasca Oil, so you can quickly surface a shortlist that suits your own playbook rather than a generic list.
- For investors who want resilience to be front and center, consider starting with a basket of 8 resilient stocks with low risk scores that score well on stability and financial strength.
- If value is the priority, you can filter for companies that pair solid fundamentals with attractive pricing by reviewing a hand picked set of 5 high quality undervalued stocks.
- Income focused readers who care about cash returns today as well as balance sheet discipline may want to scan through a curated group of 1 dividend fortresses that combine higher yields with robust fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com