


Visa (V) Following The UPT Deal Is The Business Payments Story Now Fully Valued
Visa’s UPT partnership puts business payments in focus
Visa (V) is back in the headlines after UPT announced it will use Visa’s Currencycloud platform to power virtual EUR and GBP IBANs and real-time foreign exchange for corporate clients.
Visa’s share price has cooled slightly in the short term, with the stock down 3.7% over the past month after a solid 7.5% 90 day share price return, while the 1 year total shareholder return of 9.8% and 3 year total shareholder return above 60% point to momentum built over a longer stretch as the company pushes deeper into cross border and value added services, such as the UPT Currencycloud rollout.
Compare Visa’s move deeper into business payments with other high quality financials by screening for list of solid balance sheet and fundamentals (24 results) that may also be building strength in cross border and corporate flows.
Visa now trades with a recent pullback on the chart and fresh momentum in business payments after the UPT Currencycloud deal. Does that mix still skew the risk reward toward buyers, or has the easy upside already been taken?
Most Popular Narrative: 51% Overvalued
Visa last closed at $367.38, while the leading valuation narrative pegs fair value closer to $243.70 per share. That gap frames the UPT Currencycloud partnership as a growth effort layered on top of a stock that the narrative already treats as richly priced.
Visa executes steadily on its three-pillar strategy: Consumer Payments volume growing 8-9% in constant dollars driven by secular cash-to-card conversion and cross-border recovery, CMS at ~20% initially decelerating to ~12% by FY30, VAS sustaining 20-25% growth before decelerating to ~15% by FY32 as the business matures. The DOJ antitrust case resolves with a monetary settlement and limited routing adjustments, painful but not structurally disruptive to the debit network economics.
See why 10 investors see Visa as 51% overvalued.
Result: Fair Value of $243.70 (OVERVALUED)
Still, the Visa narrative could be knocked off course if cross border volume weakens or if the DOJ outcome hits margins harder than modeled.
Find out about the key risks to this Visa narrative.
Another View on Visa’s valuation
The narrative pegs Visa as heavily overvalued, yet our DCF model points in the opposite direction. On a $367.38 share price, the SWS DCF model estimates future cash flow value around $403.18, which implies a margin of safety instead of excess. Which story do you trust when the models disagree?
For a closer look at the cash flow assumptions behind that number and how sensitive they are to small changes in growth or discount rates, Look into how the SWS DCF model arrives at its fair value.
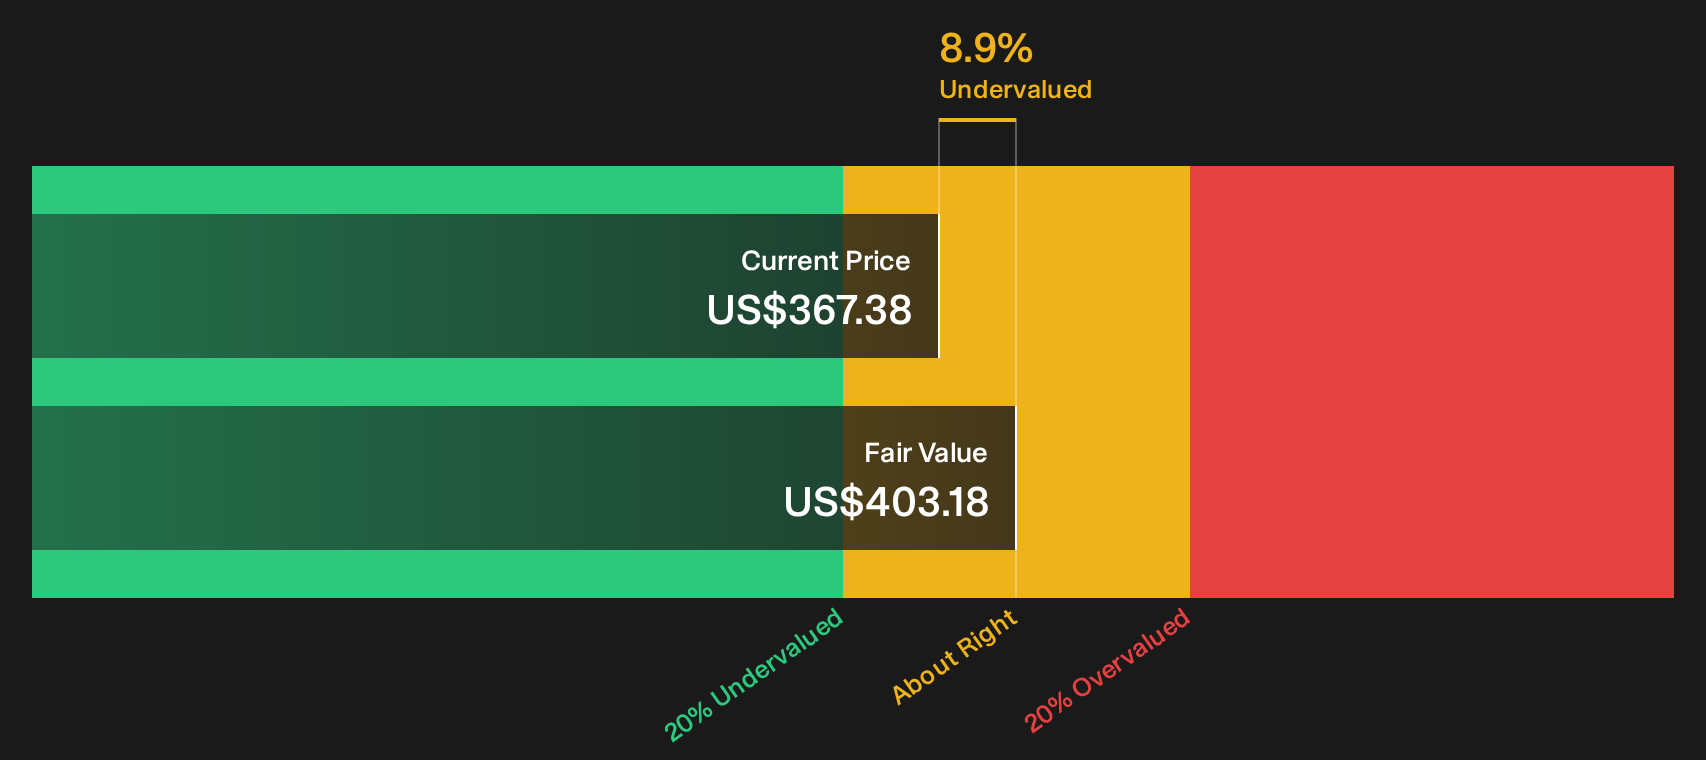
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Visa for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Visa’s value are clear, so move quickly from opinion to evidence by weighing the data, the DOJ overhang, and the 3 key rewards and 1 important warning sign.
Looking for more Visa-sized opportunities?
Visa’s story is just one angle. Broaden your watchlist with fresh ideas now, so you are not chasing the crowd after the next move.
- Spot potential value early by reviewing steady operators that screen as 30 resilient stocks with low risk scores before they draw wider attention.
- Target stronger potential upside by searching for quality companies trading below what their fundamentals suggest through the 32 high quality undervalued stocks.
- Build a cash flow base for your portfolio by focusing on income opportunities in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com