


Is Finance Team Reshuffle Altering The Investment Case For Regions Financial (RF)?
- Regions Financial announced that long-serving Treasury executive Allen Mayer has become Treasurer, succeeding retiring veteran Deron Smithy, while Craig Harrison has been hired as head of Corporate Finance to run financial planning, analytics and systems across the bank.
- This reshuffle places Mayer, who has spent 17 years working on balance sheet and hedging decisions, alongside Harrison, who brings more than 20 years of finance leadership from other large institutions. Together they will concentrate key risk, funding and planning roles under a refreshed finance bench.
- We will look at how Regions Financial's investment narrative is affected by this new finance leadership team, with particular attention to Mayer's expanded remit.
Scan how Regions Financial compares with other banks adjusting their finance teams by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) for potential ideas to research next.
Regions Financial Investment Narrative Recap
For a shareholder in Regions Financial, the core belief is that a Sun Belt focused bank with a strong deposit base and growing fee businesses can turn that footprint and product mix into steady revenue and earnings. The most important near term swing factor is whether management can reignite top line progress after flat US$1.91b quarterly revenue and softer fee momentum.
The biggest risk remains that costs stay sticky while technology and branch investments take time to flow through, keeping the efficiency ratio under pressure. The Mayer and Harrison appointments matter for execution quality, but they do not fundamentally change the near term revenue or expense catalysts on their own.
The earlier update that Regions Financial is framed as undervalued, with a fair value estimate above the recent share price, sits in the background of this leadership change. For that view to hold up, investors will be watching how the new finance bench supports earnings quality, fee diversification and capital deployment without letting credit standards slip.
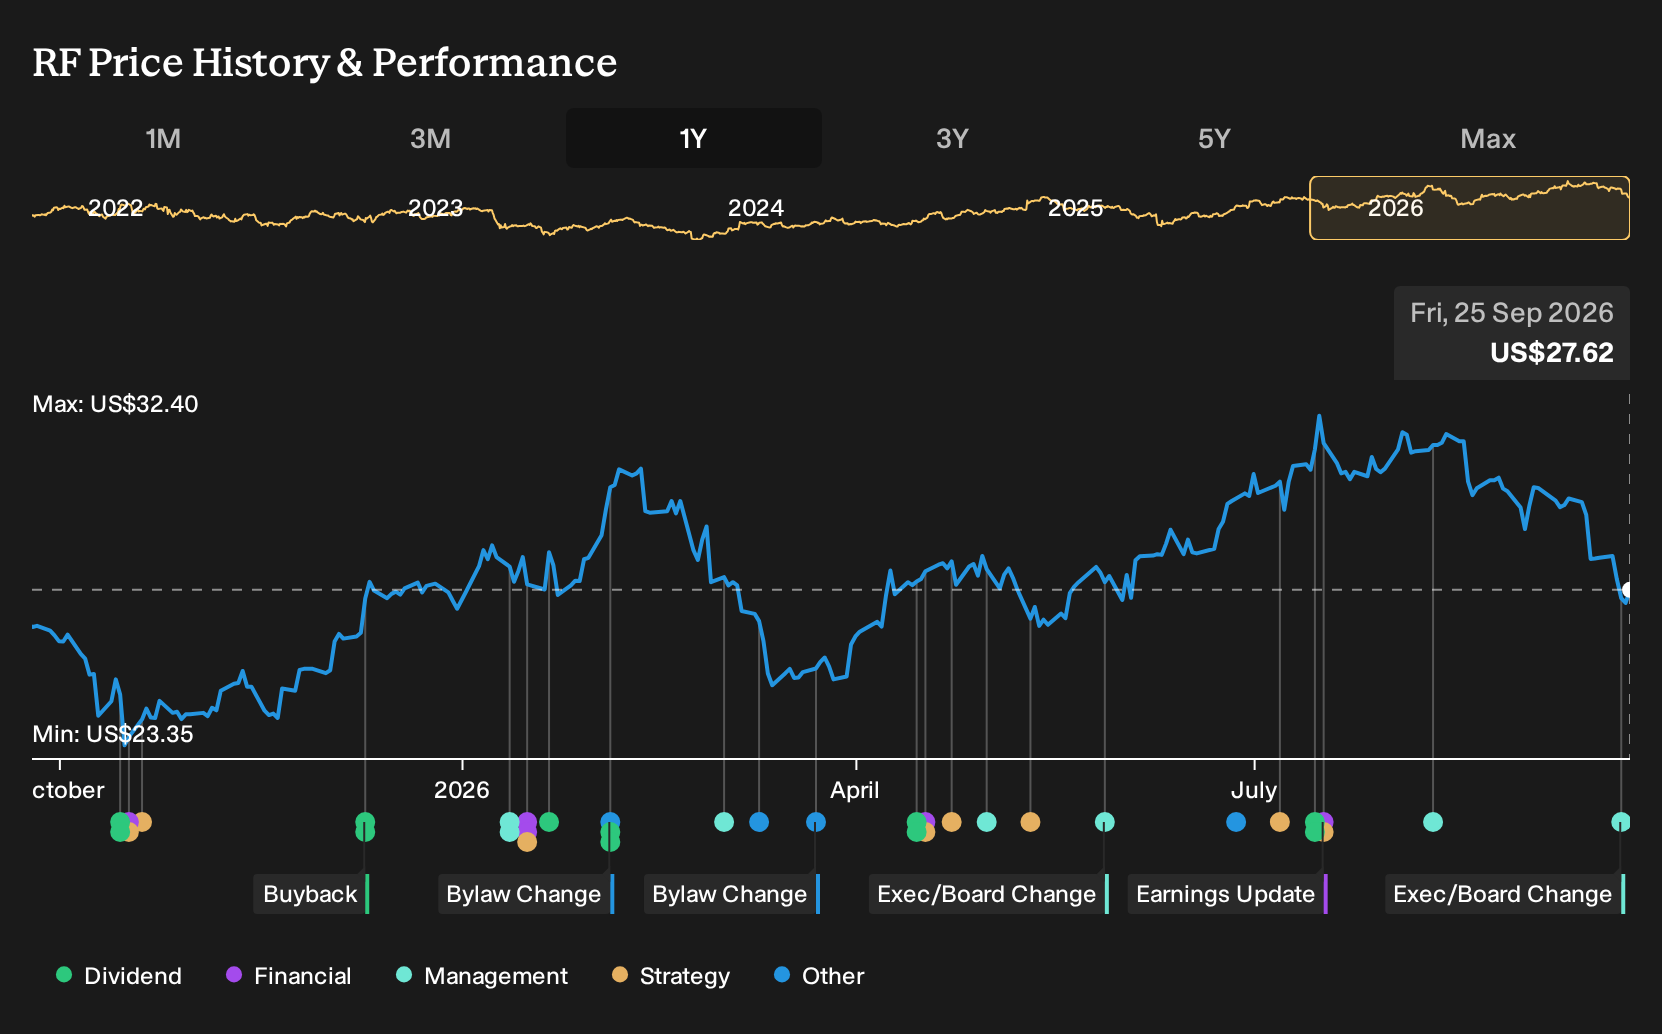
Choppy trading, with the stock down about 9% over the last 90 days and 11% over the past month, shows how sensitive sentiment already is to revenue and fee headlines. A more integrated approach to Treasury and Corporate Finance could help align funding, hedging and planning with digital and Sun Belt growth catalysts, but markets will likely want clean execution data before any re-rating of the shares.
Regions Financial's current analyst story assumes revenues of US$8.9b and earnings of US$2.5b by 2029, based on earnings today of about US$2.1b. That setup reflects 7.2% yearly revenue growth and an earnings increase of roughly US$0.4b from current levels to the consensus forecast.
Uncover how Regions Financial's fair value indicates a 19% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Across just 2 fair value estimates from the Simply Wall St Community, Regions Financial’s range runs from about US$33b to almost US$59b of implied equity value, which is a wide gap for the same bank. You can weigh that spread against risks around flat US$1.91b quarterly revenue, as well as potential catalysts from Sun Belt growth, fee build out and the new finance leadership team. That mix shows how sharply opinions can differ, so it makes sense to review several of these viewpoints before deciding how Regions fits in your portfolio.
Explore another Regions Financial fair value estimate, including one that suggests as much as 113% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Regions Financial research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Regions Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Regions Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Regions Financial?
If you want to put Regions Financial in context, it helps to compare it with a wider watchlist of potential opportunities. The Simply Wall St Screener lets you filter for traits that fit your approach, whether you care most about quality, income, or keeping risk contained.
- For investors who like resilient balance sheets and steady fundamentals, start by reviewing our list of solid balance sheet and fundamentals (24 results) to see which businesses match that profile.
- If value is your focus and you prefer to research companies that screens suggest may trade below their underlying strength, check out the 32 high quality undervalued stocks as a shortlist to investigate further.
- For readers who want potential income ideas, scan the 8 dividend fortresses and see which high yield payers line up with your risk tolerance and time horizon.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com