


Moelis (MC), Why Is The Firm Back In Focus Today?
Moelis (MC) just added a new senior banker to its European lineup by appointing Matthew Rosedale as Managing Director to help lead its Financial Sponsors business across the region.
For context, Moelis shares trade at US$58.74. The 1-day share price return of 1.94% only partly offsets a 30-day share price decline of 14.12%. The year-to-date share price return is down 17.52% and the 1-year total shareholder return is down 15.56%, even though the 3-year total shareholder return of 47.56% and 5-year total shareholder return of 18.03% point to a much stronger longer run.
Compare Moelis with a curated group of peers by scanning the 16 high quality undiscovered gems, which may be quietly setting up for their next move in advisory and capital markets activity.
Moelis trades at a double discount to both analyst targets and some fair value estimates after a weak run. Is the market being overly cautious, or does the recent slide simply reflect the fundamentals on show?
Most Popular Narrative: 17.3% Undervalued
Moelis is framed as undervalued in the most followed narrative, with a fair value of $71 against a last close of $58.74. This puts the focus squarely on whether the advisory model can support those higher assumptions over time.
The firm's growing recurring and retained advisory assignments, particularly through expansion of capital structure advisory and creditor-side franchises, provide more predictable and less volatile fee income streams. This smooths out earnings cyclicality and improves the quality of earnings, potentially leading to a valuation re-rating.
See why 10 investors see Moelis as 17% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the narrative can break if Moelis sees deal activity stall while expansion and hiring keep costs elevated, or if rivals squeeze fees and erode profitability.
Find out about the key risks to this Moelis narrative.
Another View on Moelis Valuation
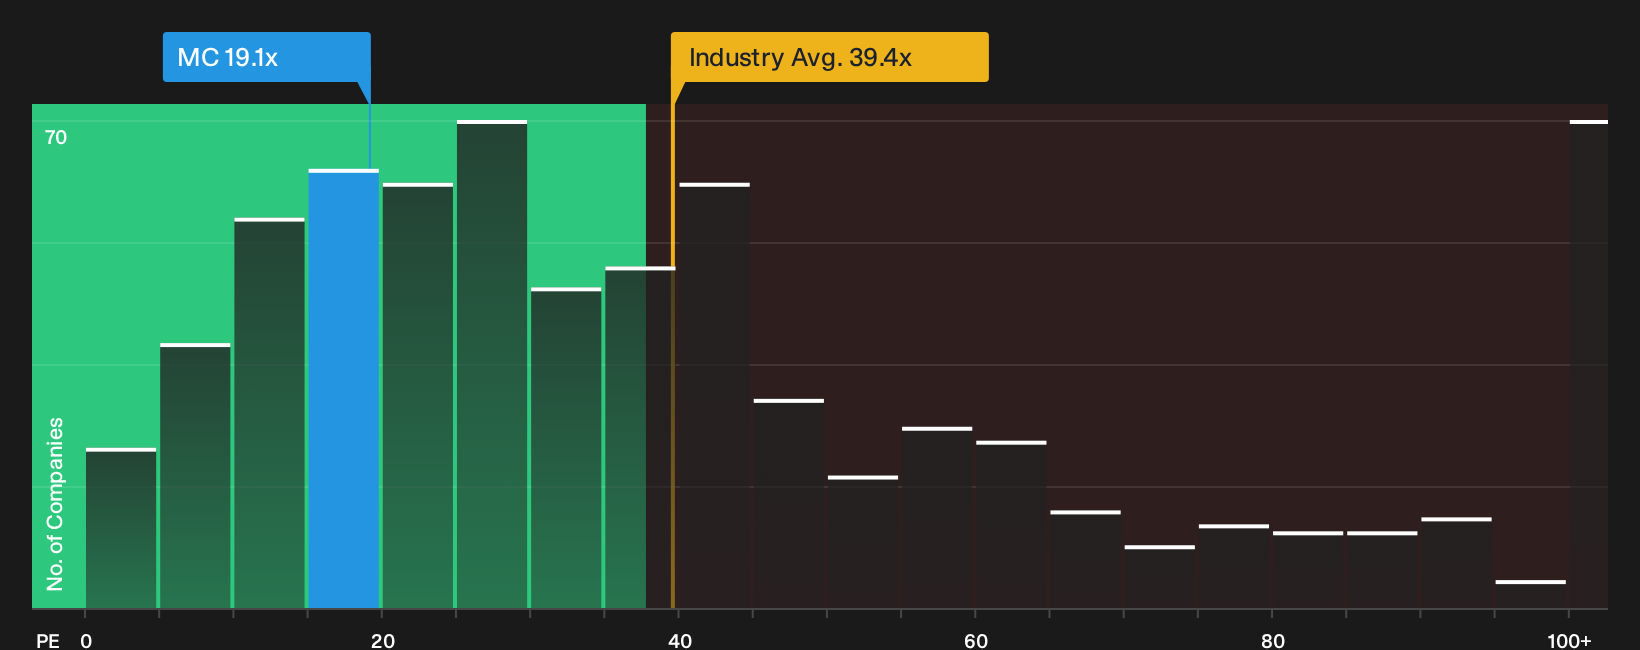
The first narrative leans on fair value estimates and analyst targets to argue Moelis looks 17.3% undervalued. A simpler lens tells a different story. On a P/E of 19.1x versus a fair ratio of 14.9x, the stock screens expensive even though it trades well below the US Capital Markets average of 39.4x and only slightly under the 19.6x peer group. Is that premium a cushion, or extra risk if sentiment turns?
For a closer look at how this valuation gap could close over time, and what that might mean for upside or downside, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Moelis so far. If you want to move quickly and rely on your own judgment, weigh up the 3 key rewards and 2 important warning signs.
Looking for more Moelis sized ideas?
Moelis might be front of mind today, but you give yourself a real edge when you line it up against other clear, data driven ideas on the platform.
- Target reliable cash engines by scanning the 32 high quality undervalued stocks that combine strong fundamentals with pricing that still looks reasonable on the numbers.
- Protect your downside by checking the 30 resilient stocks with low risk scores, where resilient businesses with steadier risk profiles could help smooth out a bumpier portfolio.
- Get ahead of the crowd by reviewing the 16 high quality undiscovered gems, which may highlight quality stories the broader market has not fully focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com