


Does Raised Outlook Change The Bull Case For Synopsys (SNPS)?
- Synopsys highlighted deeper work with TSMC, new agentic AI design flows across A14, N3P and N2P nodes, plus Ansys driven multiphysics tools alongside Q3 FY26 results that led management to raise full year revenue and earnings guidance.
- Alchip’s joint paper with Synopsys on 224G PHY based, protocol agnostic interconnects showed chip to chip bandwidth density approaching physical limits, underscoring how Synopsys IP and packaging co design are being used in real AI data center hardware projects.
- We will now look at how Synopsys' investment narrative aligns with the expanded TSMC collaboration around agentic AI design flows.
Synopsys Investment Narrative Recap
To own Synopsys, you need to believe its AI centric EDA, Ansys multiphysics tools and Design IP can keep attracting complex chip projects even as integration work and restructuring continue. The short term swing factor is execution on Ansys and agentic AI flows, while keeping profit margins, which are currently 11.4%, from slipping further as costs move through the P&L.
The biggest risk right now sits in a slower than hoped recovery in IP and any drag from Ansys integration costs, litigation and index removal on cash generation. The expanded TSMC collaboration supports the operating story but does not fundamentally change that near term risk reward balance.
The most relevant update to this TSMC news is Synopsys’ Q3 FY26 report and raised full year guidance, which tied stronger EDA and Ansys demand directly to AI chip design work. That print showed Design IP revenue of US$474 million and highlighted muted full year IP growth, so the TSMC wins matter mostly as proof that higher value IP is being used in advanced projects.
For you as an investor, the link between certified TSMC A14 and N2P flows, agentic AI tools and that earlier guidance raise is the execution thread to watch. If Synopsys converts these deep process node collaborations and Alchip class AI hardware projects into more customized and royalty bearing IP, it leans into the catalysts analysts already flagged while still carrying the integration and margin risks above.
Synopsys' current outlook points to revenues of US$13.0b and earnings of US$2.1b by 2029, based on analyst assumptions of 11.4% yearly revenue growth and an earnings increase of about US$1.0b from US$1.1b today.
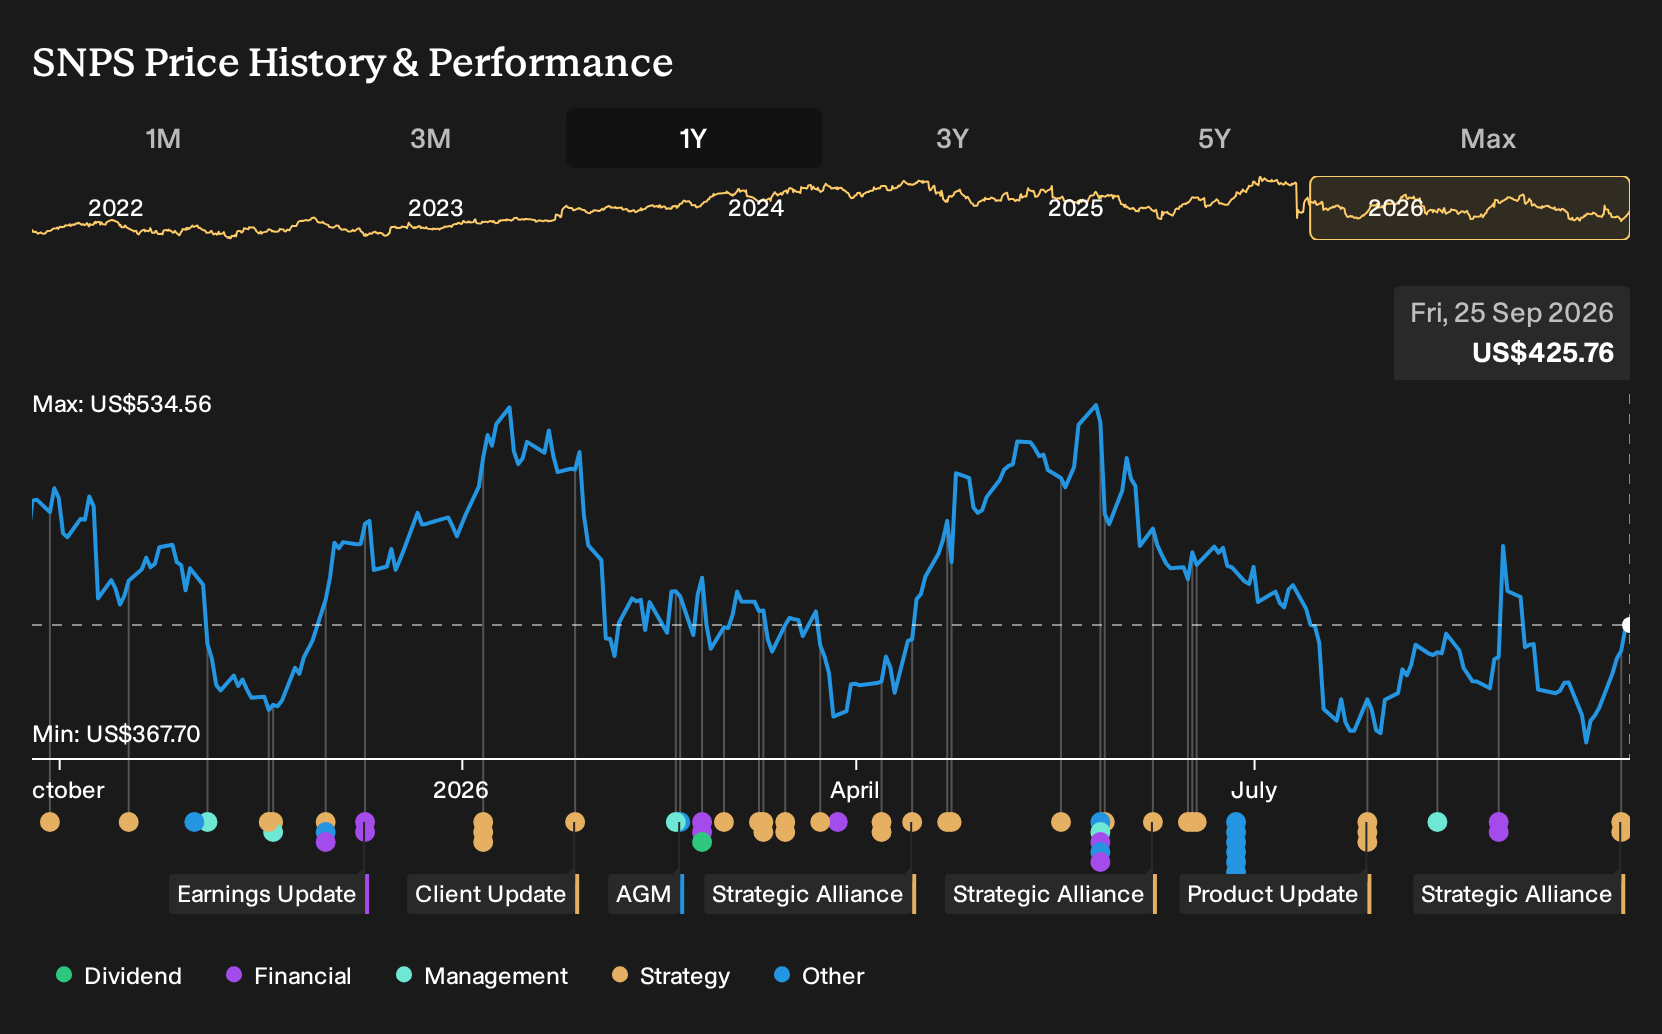
Uncover how Synopsys' fair value indicates a 28% potential upside to its current price, before enthusiasm around Synopsys' AI story closes that gap.
Exploring Other Perspectives
The Simply Wall St Community currently has 3 fair value views on Synopsys, clustered between about US$471 and US$546, so you are seeing a tight, high-priced band rather than outliers. Those private investors are not factoring in the latest TSMC and Alchip updates, or the ongoing Ansys integration risks. Use their work as a starting point, and explore several alternative viewpoints before deciding how Synopsys fits your own AI infrastructure exposure.
Explore 2 other Synopsys fair value estimates, including one that suggests as much as 28% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Synopsys research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Synopsys. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Synopsys' overall financial health at a glance.
Looking for more Synopsys style ideas?
If Synopsys has sharpened your focus on where real cash flows and balance sheet strength come from in AI and chip design, it can help to widen the lens and compare it with other businesses that share similar financial traits.
- If capital preservation is high on your list, consider starting with a set of companies screened for resilience and lower risk scores through the Simply Wall St screener using 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, use the valuation filters to surface a focused group of potential bargains via 32 high quality undervalued stocks.
- If you care most about financial strength and cleaner balance sheets, you can filter for firms with healthier debt and liquidity profiles using the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com