


What Corpay Stock's AI Agent Rollout Means For Shareholders
- Corpay, Inc. recently expanded its Corpay Complete platform with additional AI agents that automate spend analysis, transaction coding, virtual card creation, and voice driven expense handling across corporate, fleet, and vendor payments, all within existing finance controls and audit trails.
- The build out of purpose built AI agents suggests Corpay is investing directly in automation that could reshape how enterprise customers manage operational workload, compliance, and spend visibility across its payments ecosystem.
- We will now see how Corpay's expanding AI agents inside Corpay Complete might influence the broader investment narrative for the business.
See how Corpay's AI push compares with other payment and expense platforms by reviewing a curated set of 37 profitable AI stocks that aren't just burning cash that are now reshaping how businesses handle transactions and controls.
Corpay Investment Narrative Recap
To own Corpay, you need to believe the payments franchise can keep shifting mix toward higher value corporate solutions while managing regulatory and funding constraints. The expanded AI agents inside Corpay Complete fit that story because they deepen spend management utility for corporate, fleet, and lodging customers without changing the basic transaction fee driven model.
In the near term, the most important swing factor is execution on automation and cross border volumes, which management and analysts already frame as key revenue drivers. The biggest current risk is the FTC matter around U.S. Vehicle Payments. Corpay flags the proposed US$100m settlement as not material to ongoing operations, so outside perception may move more than fundamentals.
The FTC enforcement action on vehicle payments is the announcement that matters most when thinking about these new AI tools. Investors are watching whether stricter marketing rules, tighter fee practices, and higher compliance expectations in fuel cards eventually spill across to how Corpay designs, prices, and sells broader payments and expense products.
Regulatory scrutiny, along with high leverage and debt that is not well covered by operating cash flow, already sits in the risk bucket. Any further shift in disclosure standards or fee structures could pressure margins in the large Vehicle Payments segment and slow how quickly Corpay rotates capital into corporate payments, buybacks, and M&A, even as AI agents aim to make the platform stickier.
Corpay's current analyst storyline points to revenues of US$6.6b and earnings of US$1.9b by 2029, which assumes 9.4% yearly revenue growth and an earnings increase of about US$800m from US$1.1b today.
Uncover why Corpay's fair value indicates a 16% potential upside to its current price, a discount that could close sooner than you might expect.
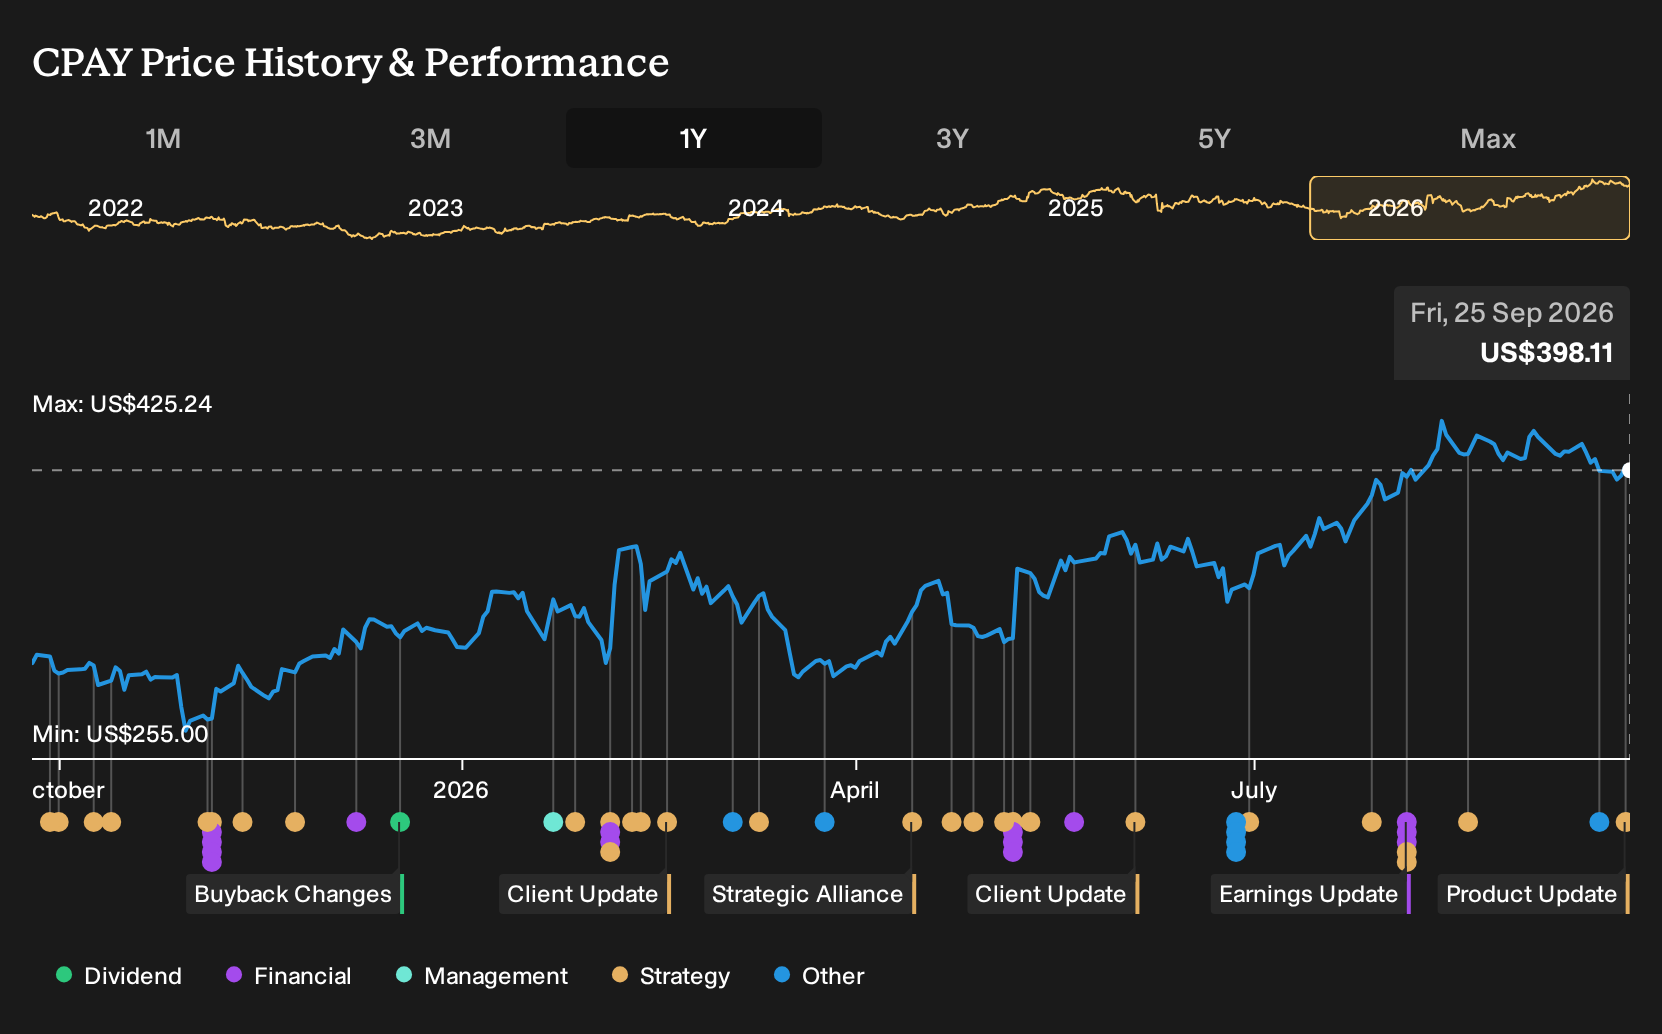
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span from about US$350 to more than US$633b for Corpay, a gap that shows just how far opinions can stretch. Put that next to the FTC settlement over vehicle payments and Corpay’s fresh AI agent rollout, and you get very different stories about future earnings power. Use those contrasts to test your own view against several alternative perspectives.
Explore 3 other Corpay fair value estimates, including one that suggests as much as 159224553000% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Corpay research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Corpay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corpay's overall financial health at a glance.
Looking For More Investment Ideas Beyond Corpay?
Once you have formed a view on Corpay, it can help to compare that thesis with other companies filtered by clear, rules based criteria using the Simply Wall St Screener.
- If capital protection is a priority, start with companies that screen for resilience and lower risk profiles through the 30 resilient stocks with low risk scores.
- For readers hunting for strong fundamentals, consider stocks with cleaner balance sheets and solid financial footing using the list of solid balance sheet and fundamentals (24 results).
- If you are looking for potential under the radar opportunities, scan through a curated set of 16 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com