


Everpure (P) Lifted Guidance, Is The Upside Already Priced In?
Everpure guidance sparks fresh look at the stock
Everpure (P) issued new earnings guidance for fiscal 2028, projecting revenue between $7.0b and $7.3b, which has pushed the stock to an all-time high and sharpened investor focus on its data storage business.
The earnings outlook has arrived on top of a sharp price move, with Everpure’s share price returning 82.6% year to date and 82.2% over the past 90 days. Its 1 year total shareholder return of 52.9% and 3 year total shareholder return of about 2.5x suggest momentum has been building despite the stock’s recent removal from two Russell small cap indexes on 18 September.
Compare Everpure’s surge with a curated group of fast growing tech players by scanning the 16 high quality undiscovered gems now that guidance and momentum are firmly in the spotlight.
Everpure’s guidance-fueled surge could signal investors are finally pricing in its data storage ambitions, or it could reflect a rapid swing in sentiment. How does the current valuation line up with those expectations?
Most Popular Narrative: 30% Undervalued
Everpure last closed at $126, while the most followed narrative on the stock anchors fair value closer to $180 and frames that gap around AI infrastructure optionality rather than storage alone.
The real bet is a multiple re-rating event, driven by three specific catalysts.
The hyperscale design win. Everpure secured its first EXA-scale hyperscale customer in FY2026. The company expects hyperscale revenue to ramp materially in FY2027. One additional hyperscale win at this scale represents $200 to $300 million in incremental product revenue in year one, more than the company's entire quarterly subscription revenue from two years ago. At that point, Everpure is no longer a story about enterprise storage share gains, it is a story about being a critical supplier to the largest infrastructure buildout in history. The multiple changes.
See why 45 investors see Everpure as 30% undervalued.
Result: Fair Value of $180 (UNDERVALUED)
Still, Everpure’s case can break if hyperscale demand underwhelms or if rivals in AI storage win key deployments and reduce its pricing power.
Find out about the key risks to this Everpure narrative.
Another View: Everpure on Rich Multiples
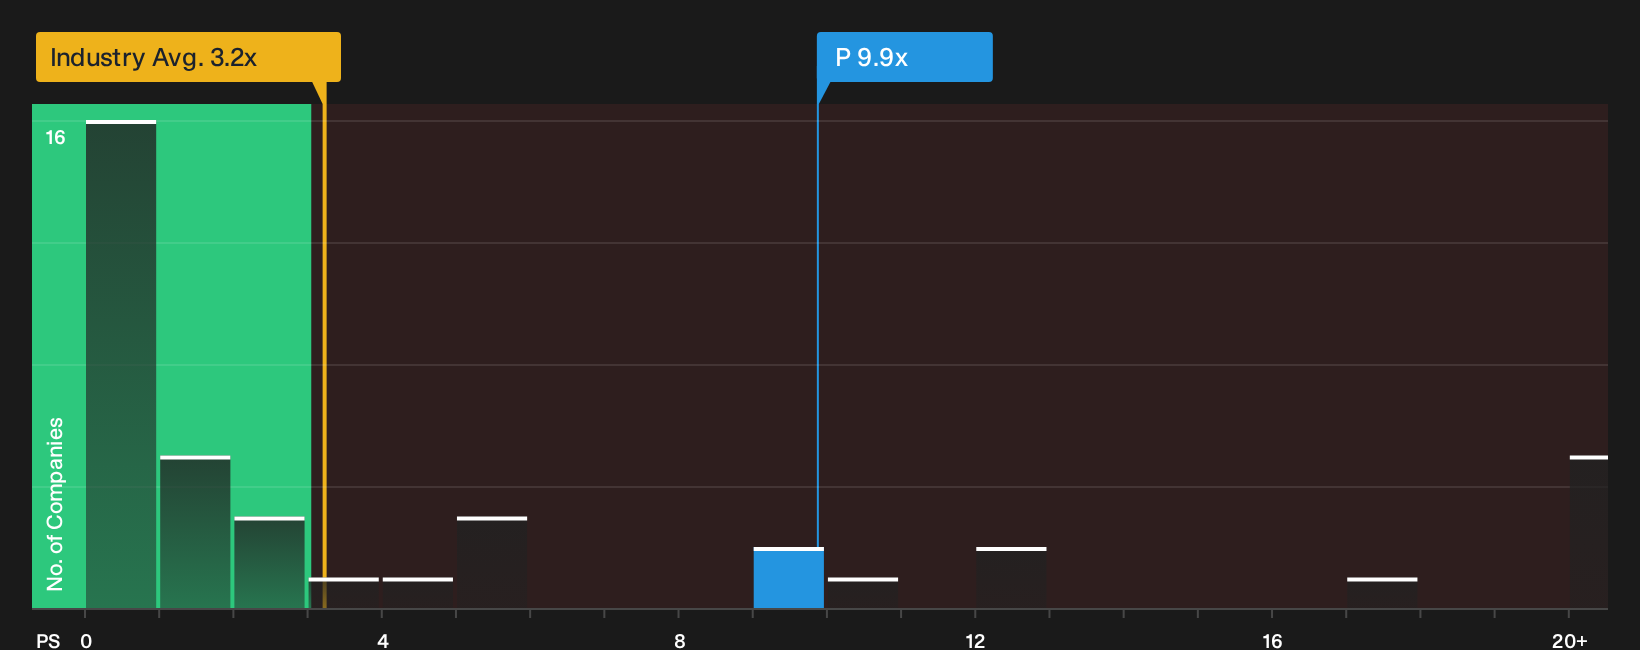
The DCF narrative presents Everpure as heavily undervalued, yet the simple P/S check tells a different story. The stock trades at 9.9x sales versus roughly 3.2x for the wider US tech group and about 2.1x for peers, even though the fair ratio model suggests 18.8x as a level the market could move toward. That spread highlights potential upside if the higher fair ratio is accurate, but also potential downside if investors eventually gravitate toward peer and sector averages. Which signal carries more weight for a stock that has already moved this far?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Everpure leaves you undecided, move quickly to inspect the full picture yourself and weigh both sides carefully. Start by reviewing the 3 key rewards and 2 important warning signs.
Looking for more Everpure-sized opportunities?
If Everpure has sharpened your focus on what strong ideas can look like, do not stop here. Use the Simply Wall St Screener now to spot other potential opportunities before they move.
- Target resilient compounding potential by scanning 8 dividend fortresses that aim to combine robust payouts with disciplined balance sheets.
- Hunt for mispriced quality by reviewing the 32 high quality undervalued stocks that pair solid fundamentals with room for a rerating.
- Protect your downside first by focusing on 30 resilient stocks with low risk scores that score well on financial strength and volatility checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com