


Should Contract Extensions Require Action From Jacobs (J) Investors?
- Recent client announcements show Jacobs Solutions was reselected and expanded on large infrastructure and energy transition projects in Germany and the U.K., including thyssenkrupp Steel’s hydrogen-capable Duisburg plant and National Grid’s multi region Asset Health Intervention Programme.
- The cluster of wins points to Jacobs Solutions deepening its role in complex, long duration infrastructure programs where execution discipline, specialist engineering and program management capabilities are central to long term client demand.
- We will look at how Jacobs Solutions expanded role on National Grid’s asset health program could reshape the company’s broader investment narrative.
Scan beyond Jacobs Solutions to compare its infrastructure and energy transition momentum with a curated list of 40 power grid technology and infrastructure stocks that could also be shaping critical grid upgrades.
Jacobs Solutions Investment Narrative Recap
To own Jacobs Solutions, you need to be comfortable with a story built around long duration infrastructure, energy transition and AI related projects turning a US$29b backlog into steadier earnings, even as current profit margins sit at 2.5% and trail last year. The near term swing factor remains execution quality on those complex programs, not short term trading moves in the stock.
The biggest risk still sits in exposure to public sector and regulated utility budgets, which can slow or shift with political cycles and affect backlog conversion. The recent wins in Germany and the U.K. look additive to visibility but do not obviously change that core risk reward balance on their own.
The National Grid Asset Health Intervention Programme reappointment looks most relevant for the Jacobs Solutions story right now. It extends the firm from one to three U.K. regions over five years and covers more than 800 transmission assets, with Jacobs as sole supplier for detailed design, data collection and construction support on live network equipment.
This type of multi year framework lines up directly with the key catalysts that investors already watch. It reinforces the infrastructure and power grid pipeline that supports use of global delivery, digital tools and standardized designs, which management has tied to margin ambitions toward 2029. It also highlights the flip side of the risk. Dependence on regulated clients can underpin long contracts, yet leaves the business sensitive if funding plans or regulatory timelines shift.
Jacobs Solutions' current narrative ties to analysts projecting US$17.5b in revenue and US$1.2b in earnings by 2029, built on 7.1% yearly revenue growth and an earnings increase of about US$840.7m from US$359.3m today.
Uncover why Jacobs Solutions' fair value indicates a 17% potential upside to its current price, which could narrow quickly.
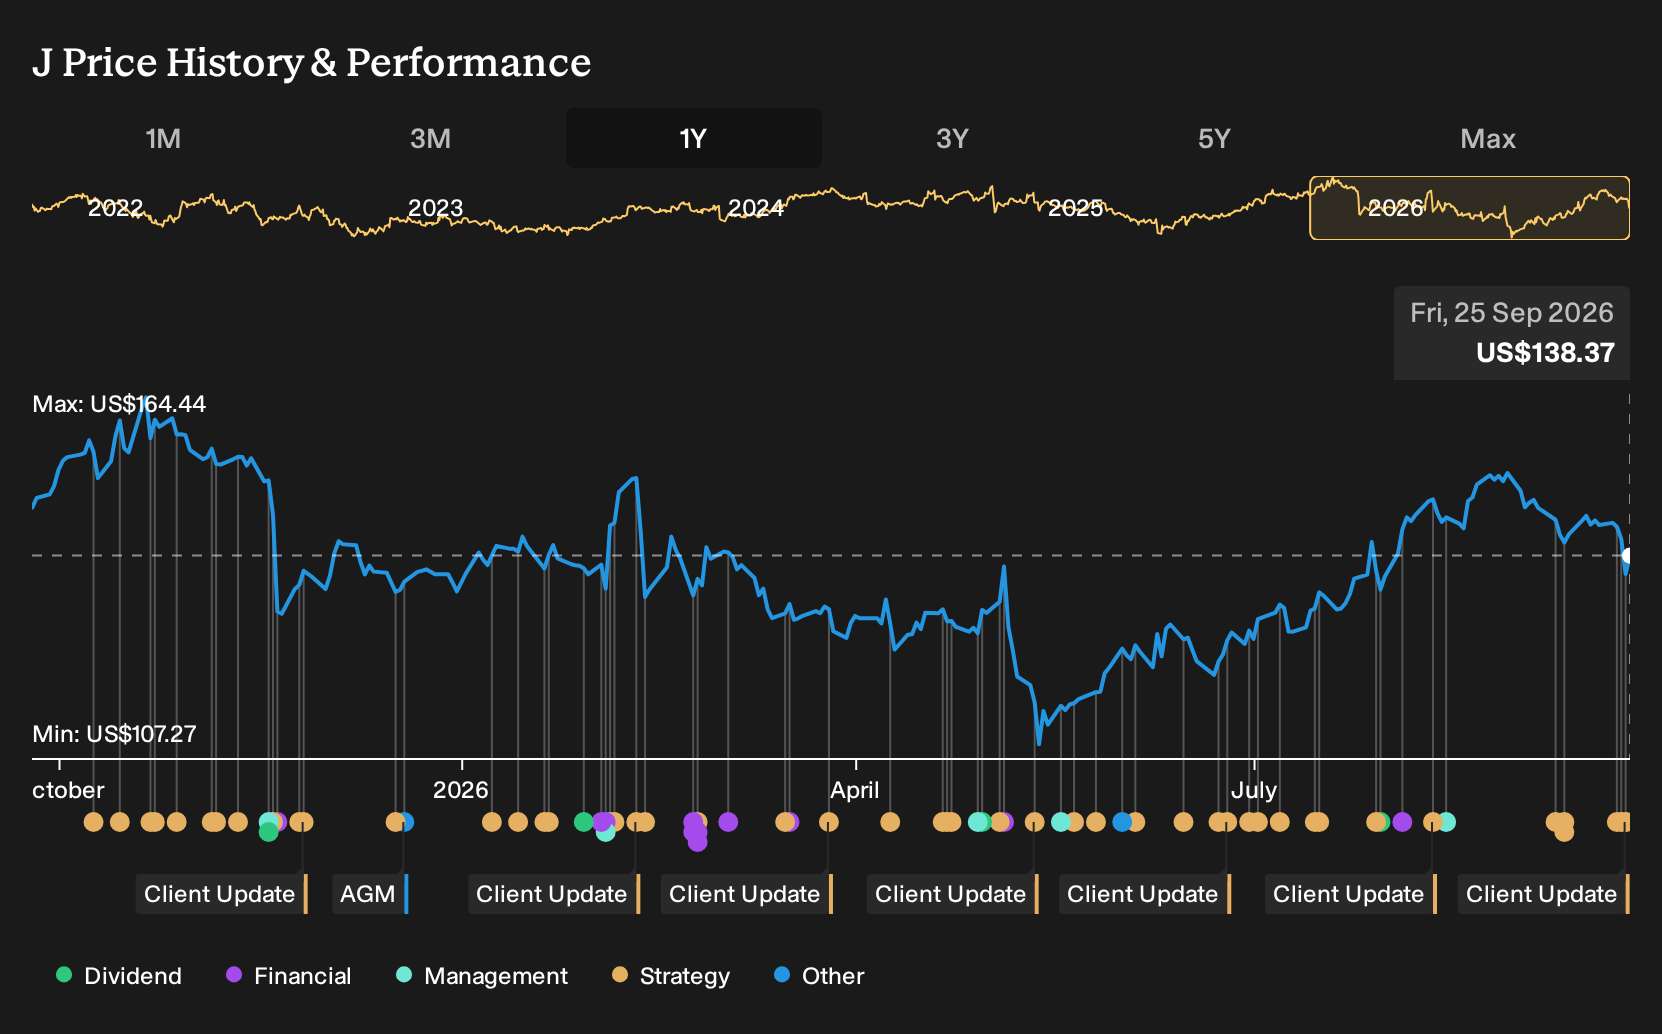
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span roughly US$110 to about US$277, so you see both deep discount and stretch pricing cases for Jacobs Solutions before these recent contract wins. When you set that against heavy reliance on public budgets and AI related build outs, you get very different expectations for how reliably future projects translate into earnings. Opinions can diverge widely, so explore several of these community viewpoints before you decide how convincing the Jacobs Solutions story really looks to you.
Explore 3 other Jacobs Solutions fair value estimates, including one that suggests as much as 100% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jacobs Solutions research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Jacobs Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jacobs Solutions' overall financial health at a glance.
Looking for more investment ideas beyond Jacobs Solutions?
If the Jacobs Solutions story has sharpened your view on long duration infrastructure and earnings quality, it can be helpful to stress test that thinking against a wider watchlist built from different angles of the market.
- For investors who want potential bargains with solid fundamentals, start by scanning a 32 high quality undervalued stocks and see which candidates line up with your return and risk expectations.
- If portfolio resilience matters most to you, filter for steadier profiles using a 30 resilient stocks with low risk scores that screens for businesses with lower risk scores and more durable characteristics.
- When you want to widen the opportunity set beyond the usual large caps, broaden your radar with a 16 high quality undiscovered gems that surfaces underfollowed stocks with strong underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com