


Fastly (FSLY) Stock Could Be Fully Priced Following New AI Security News
Fastly has been on a sharp run, and with the share price recently closing at US$24.96, the question for investors is whether that jump is supported by its sales or mainly by excitement around the story.
- Fastly has delivered a 193.6% return over the past year, which raises the stakes for whether recent buyers are paying a premium for each dollar of revenue.
- New AI focused security products and a stronger revenue profile can support higher expectations for the business, which influences how much investors may be willing to pay per unit of sales.
- There is a second opinion on Fastly worth weighing. See what analysts think Fastly's shares could be worth.
The key issue is whether Fastly's current share price is justified by the sales it is generating today and those investors expect it to deliver in the future.
If you are weighing whether Fastly's 193.6% 1 year return matches up with its sales profile, it can help to compare that question across 85 AI infrastructure stocks.
Does Fastly Look Pricey on Sales?
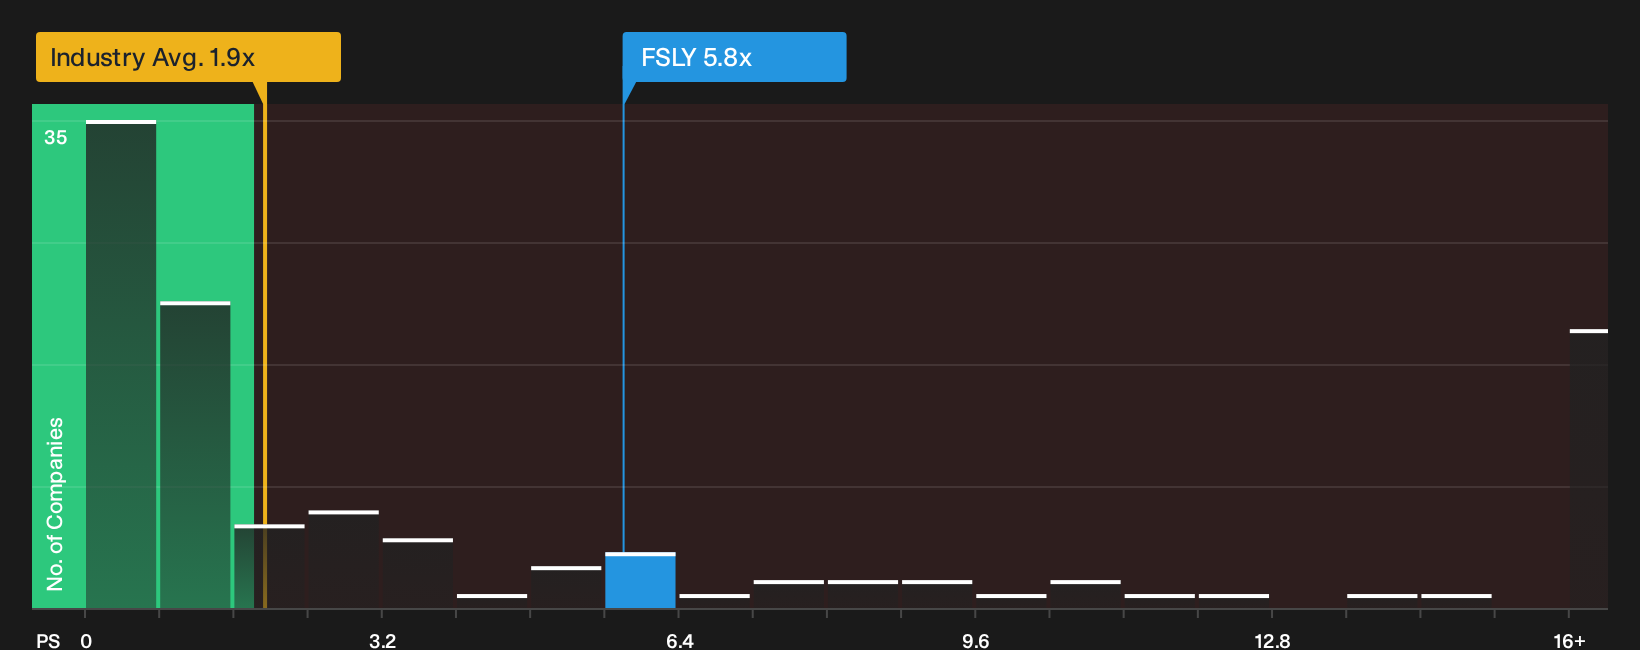
P/S is often a useful lens for Fastly because the company is still building its earnings profile while investors focus heavily on top line potential. On this measure, Fastly trades on a P/S of about 5.8x, which is well above the IT industry average of roughly 1.9x and still below the peer group around 11.6x. That puts the stock in a middle ground where it is not the most aggressively priced in its space, yet clearly valued at a premium to the broader sector on sales alone.
The Fair Ratio model, which looks at Fastly's growth outlook, profitability, risk profile and size, points to a lower P/S than the current level, so the shares screen as overvalued on this framework. Because the recent AI security launches and strong 2026 revenue print have already pushed sentiment higher, the present P/S multiple suggests that a fair amount of that optimism is already reflected in the price. Explore the numbers behind Fastly's P/S valuation.
The Fastly Narrative: What Would Justify Today's Price?
Fastly's Simply Wall St Narratives pick up where the valuation puzzle leaves off by spelling out what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than it is today. They sit on the Community page. Rather than relying on a single multiple or model point estimate, each narrative lays out the explicit assumptions behind its fair value so you can compare those with future results as they are reported.
The Fastly community sketches two very different paths, one focused on expanding security and compute workloads, the other on narrative risk and hype.
Bull case: 8% undervalued
"Successful execution of a platform-based cross-sell and upsell strategy with nearly 50% of customers now using 2+ products boosts wallet share..."
Discover why this Narrative puts Fastly at 8% undervalued.
Bear case: 402% overvalued
"What to look for is the narrative becoming more and more widespread and more and more people entering..."
Explore why this Narrative puts Fastly at 402% overvalued.
Before deciding what Fastly is worth, one more piece matters
Fastly's story on sales and expectations is only part of what investors are weighing, because our broader checks have also flagged specific concerns that deserve your attention before you move further. Take a closer look at 3 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com