


Accor (ENXTPA:AC), What Is Drawing Fresh Attention Now?
Accor (ENXTPA:AC) is back on investor screens after recent trading left the share price at €45.89. This is prompting a fresh look at how the hotel operator’s earnings profile lines up with its current valuation.
Recent trading has been choppy, with Accor’s share price slipping over the past month and quarter, even as the one year total shareholder return of 16.23% and five year total shareholder return of 62.19% point to a stronger longer term trend.
Scan how Accor stacks up against a hand-picked 182 high quality undervalued stocks that pair stronger fundamentals with more modest valuations.
Accor now trades about 20% below the average analyst target and at an even steeper implied discount to intrinsic value, yet the share price has softened in recent months. Is that caution earned or overdone?
Most Popular Narrative: 17% Undervalued
Accor’s most followed valuation story pegs fair value at about €55.29 against the current €45.89 share price, putting the spotlight on how its business mix and capital-light push are expected to reshape earnings quality.
Continued shift toward an asset-light model, with disciplined focus on higher fee-per-room contracts and quality churn, is expected to improve net margins and enhance stability/recurrence of earnings by reducing capital expenditure and exposure to owned hotel volatility.
Increasing deployment of AI-driven, cloud-based technology platforms (CRM, revenue management, PMS) is improving direct distribution, customer personalization, and pricing dynamics, which is likely to drive higher EBITDA margins through both cost efficiencies and top-line growth.
See why 7 investors see Accor as 17% undervalued.
Result: Fair Value of €55.29 (UNDERVALUED)
Still, that thesis leans heavily on Accor reducing exposure to owned hotel assets, while managing currency swings that can drag reported revenue and profit away from operational progress.
Find out about the key risks to this Accor narrative.
Another View On Accor’s Valuation
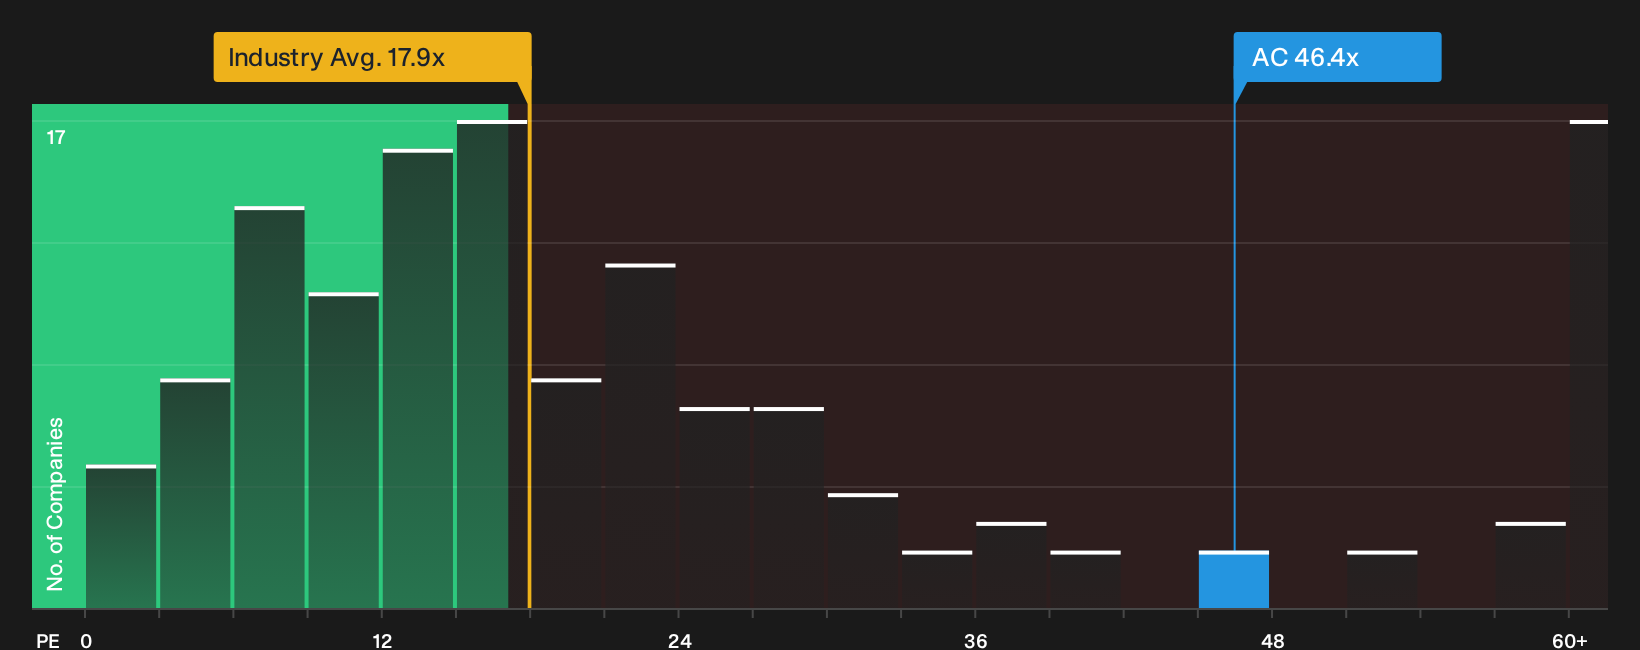
There is a catch. Accor trades on a P/E of 46.4x, while the European Hospitality group sits at 17.9x and the fair ratio is 26.9x. That gap points to richer expectations and more valuation risk if earnings progress stumbles. Which narrative feels closer to your own assumptions?
For investors who lean more on earnings multiples, there is a ready way to stress test whether this rich P/E still feels acceptable. Start with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Accor’s valuation story make this a moment to move fast on your own homework rather than rely on headlines. To weigh those trade offs directly, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Accor?
If Accor has you rethinking valuation, do not stop there. Use targeted screeners to surface fresh opportunities that fit the way you like to invest.
- Target potential upside in out of favor quality by scanning a curated pool of underappreciated stocks through the 182 high quality undervalued stocks.
- Prioritise resilience and capital strength by filtering for companies with cleaner finances using the list of solid balance sheet and fundamentals (201 results).
- Spot lesser known opportunities with strong numbers before the crowd notices by sifting through the 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com