


Will Google Cloud AI Partnership Change BNP Paribas Stock Narrative
- BNP Paribas and Google Cloud announced a five year partnership to expand the bank's access to Google Cloud infrastructure and Gemini AI models, supporting broader deployment of agentic AI across functions such as corporate credit analysis, sales, trading, research, and customer service.
- The agreement ties BNP Paribas' AI program directly to quantified value creation targets, linking Gemini powered agents to specific objectives in revenue generation, cost efficiency, and risk management across the corporate and institutional banking franchise.
- We will look at how BNP Paribas' investment narrative is shaped by this large scale Gemini Enterprise driven AI rollout with Google.
Scan how BNP Paribas is using Gemini Enterprise, then widen your watchlist with hand-picked AI infrastructure plays in our 85 AI infrastructure stocks that could experience the same structural tailwinds.
BNP Paribas Investment Narrative Recap
To own BNP Paribas, you need to be comfortable with a large Eurozone bank that leans heavily on regulated home markets while trying to squeeze more profit out of scale, technology and fee income. The Google Cloud and Gemini deal speaks directly to that. It targets efficiency in areas like credit analysis and trading workflows rather than changing the core banking mix overnight.
The key short term swing factor remains execution on cost and complexity. High operating expenses and a multi division setup still weigh on margins. The AI rollout could help if it simplifies processes and reduces manual work. The biggest near term risk remains structurally pressured Eurozone profitability and regulatory demands on capital and funding.
The most relevant supporting announcement for this AI story is the broader Group wide AI adoption program that BNP Paribas links to learning and agent development. That context matters. It shows the Gemini Enterprise partnership fits into an existing effort rather than a stand alone pilot.
For catalysts, this matters because operational benefits from Gemini agents will depend on how quickly staff adopt the tools and how tightly they are integrated with risk controls and existing systems. Execution risk is not trivial. BNP Paribas is also dealing with higher bad loan levels and a relatively high risk funding mix, so any efficiency gains from AI need to be realized without adding new operational or compliance issues.
BNP Paribas' current analyst story points to revenues of €60.9 billion and earnings of €16.4 billion by 2029, based on assumed yearly top line expansion of 5.9% and an earnings increase of about €3.6 billion from €12.8 billion today.
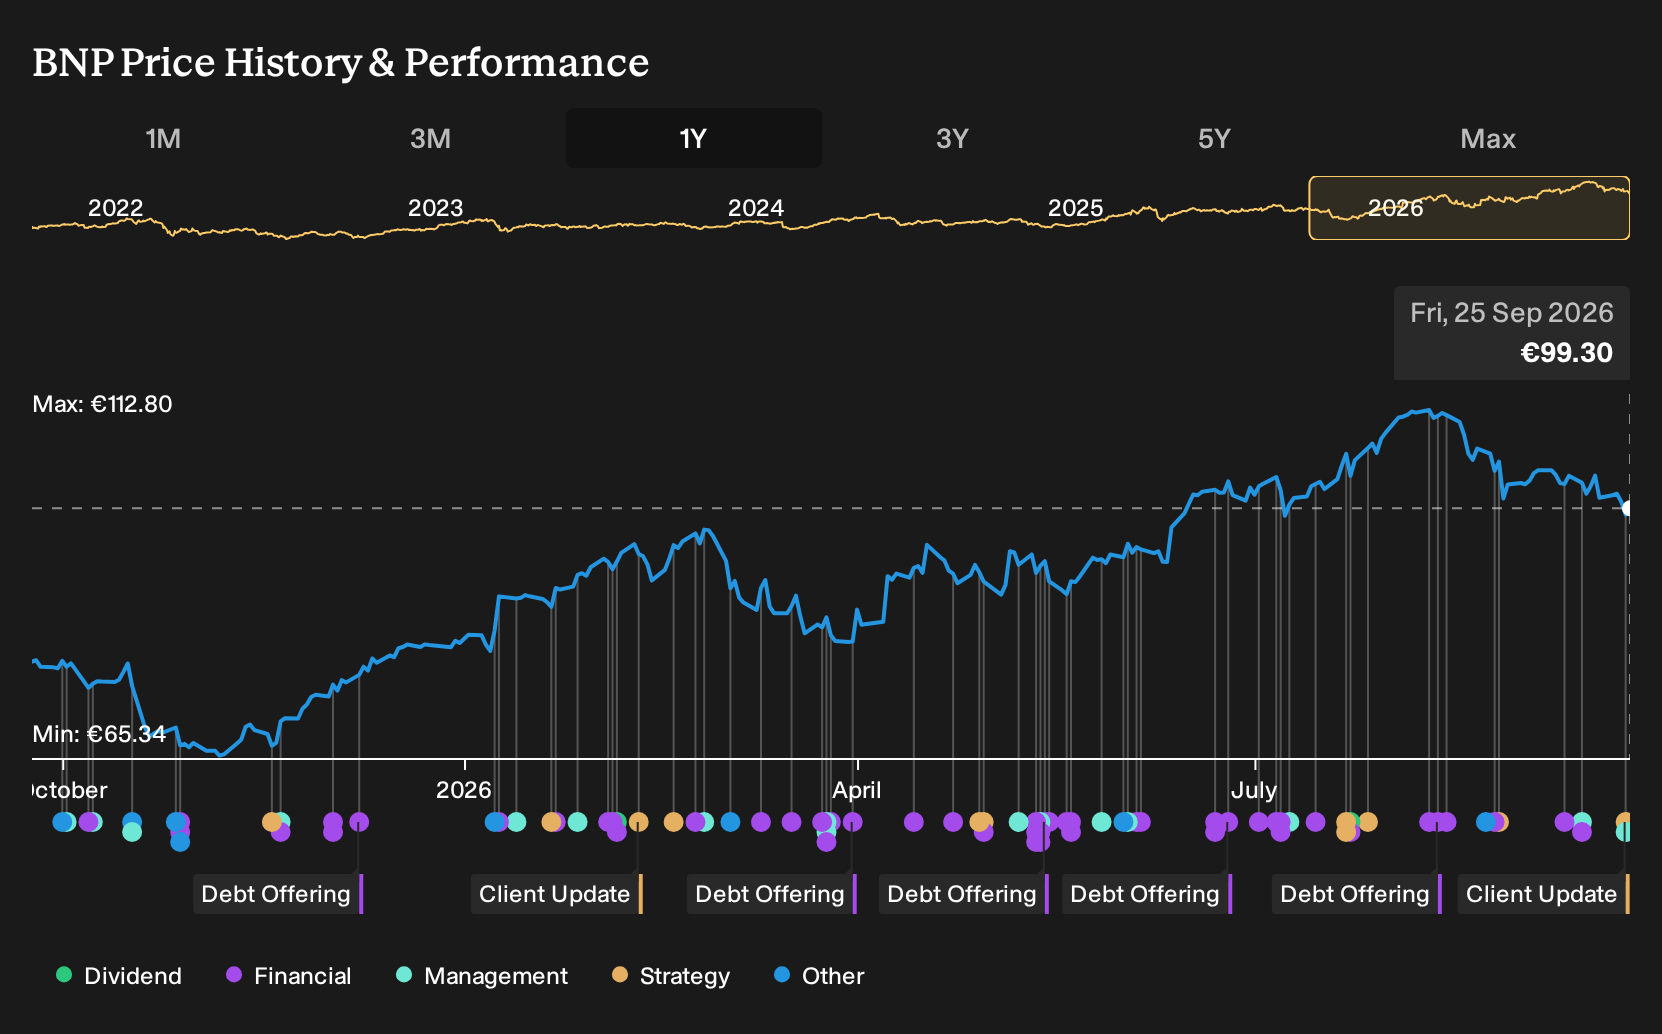
Uncover why BNP Paribas' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for BNP Paribas from 2 private investors in the Simply Wall St Community cluster between about €106 and €117, which is a tight band for such different viewpoints. You are still seeing contrasting emphasis though. Some focus on AI and tokenisation as potential earnings drivers, while others worry about Eurozone profitability and regulatory capital pressure. Use these gaps as a cue to explore multiple angles before deciding how this story fits your portfolio.
Explore another BNP Paribas fair value estimate, including one that suggests it could be worth just €106.35.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BNP Paribas research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BNP Paribas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BNP Paribas' overall financial health at a glance.
Looking For More Investment Ideas Beyond BNP Paribas?
If the BNP Paribas story has sharpened your thinking on risk, returns and business quality, it can be useful to line it up against other opportunities that share some of the traits you care about most.
- If resilience matters to you, start by scanning 226 resilient stocks with low risk scores that aim to keep portfolio volatility in check.
- If balance sheet strength is your priority, compare BNP Paribas with companies in our list of solid balance sheet and fundamentals (201 results) that focus on robust finances and cleaner leverage profiles.
- If you are hunting for mispriced potential, broaden your watchlist with our 619 high quality undiscovered gems that pair quality fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com