


How Investors May Respond To Bank of Hawaii Stock After Net Interest Income Miss
- Bank of Hawaii reported Q2 revenue up 13.2% year on year with earnings per share aligned to expectations, although net interest income fell short of analyst estimates.
- The combination of solid top line performance and a shortfall in net interest income highlights pressure on Bank of Hawaii's core lending profitability, despite disciplined balance sheet management.
- We will now look at how Bank of Hawaii's net interest income miss could influence the broader investment narrative around the bank.
Compare Bank of Hawaii's pressure on lending margins with other regionals by scanning our hand picked list of solid balance sheet and fundamentals (24 results) for potential alternatives facing similar rate and earnings crosswinds.
Bank of Hawaii Investment Narrative Recap
To own Bank of Hawaii stock, you need to be comfortable with a tightly focused regional lender that leans heavily on Hawaiian real estate and local deposits. The recent Q2 report kept revenue on track but highlighted pressure on net interest income. For the near term, the key swing factor is how quickly funding costs and loan yields rebalance.
The main risk remains concentration. A weaker local economy or property market could hit both credit quality and demand for new loans. The latest numbers did not fundamentally change that risk profile. They did, however, draw a sharper line under how sensitive Bank of Hawaii's earnings can be to margin compression.
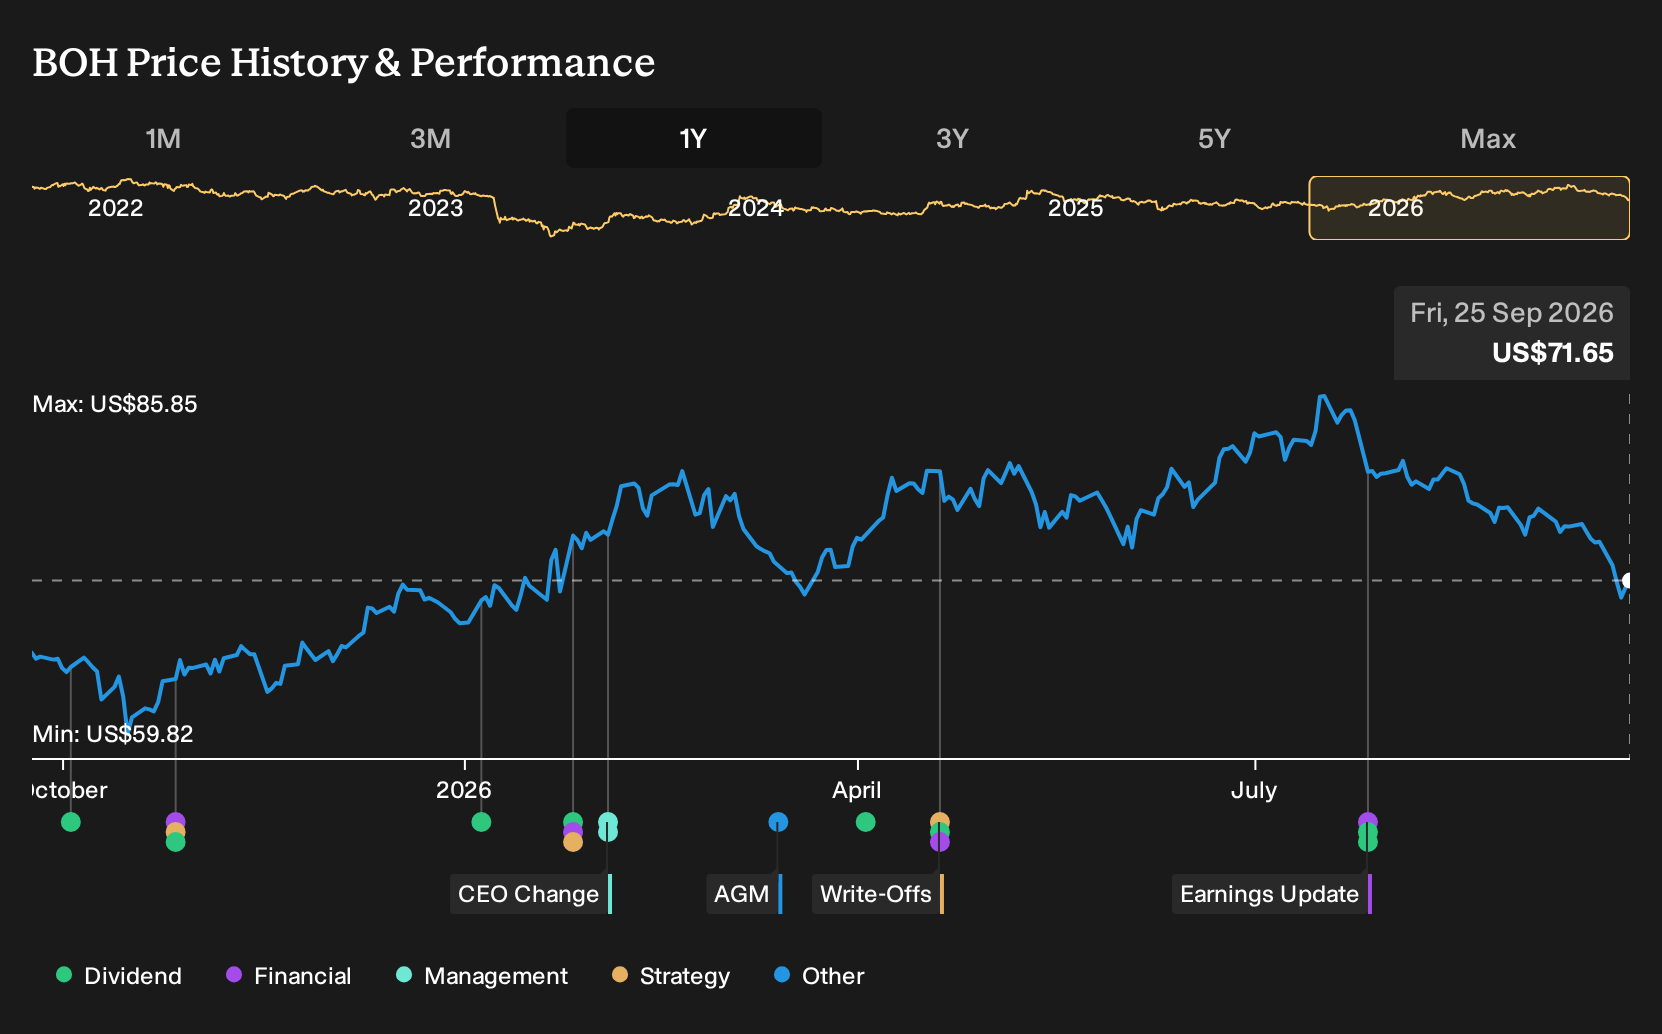
The most relevant development is the Q2 earnings release itself, which paired 13.2% year on year revenue growth with a miss on net interest income expectations and a sharp 16.2% share price drop after the report. That combination indicates that the market is highly focused on the bank's core lending profitability rather than headline revenue.
For you as an investor, the immediate question is whether Bank of Hawaii can keep growing fee based lines like wealth and trust services while managing deposit costs and defending credit quality in a real estate heavy book. Execution on digital investment and expense control now matters even more, because it can offset some of the pressure from tighter lending spreads.
Bank of Hawaii's current earnings are $198.3 million, with analysts projecting revenue growth of 11.2% per year and forecasting 2029 revenues of $1.0 billion and earnings of $335.6 million. This implies an earnings increase of about $137.3 million from today by 2029.
Uncover why Bank of Hawaii's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community only has two fair value estimates for Bank of Hawaii, yet they stretch from about $86.67 to more than $106,000 per share, which shows how far opinions can stray. Those figures were set before the recent Q2 reaction, so reassess them in light of concentration risks, real estate exposure, and flat deposit trends.
Explore another Bank of Hawaii fair value estimate, including one that suggests it could be worth just $86.67!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A useful starting point for your Bank of Hawaii research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank of Hawaii. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Bank of Hawaii's overall financial position at a glance.
Looking for more investment ideas beyond Bank of Hawaii?
If the Bank of Hawaii story has sharpened your thinking about risk, return, and concentration, you can use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- For investors hunting for resilient prospects with limited downside, you might start by reviewing a curated set of 30 resilient stocks with low risk scores that may better match your comfort with volatility.
- If income matters most to you, consider focusing on companies that combine higher yields with staying power by checking out a selection of 8 dividend fortresses that might complement Bank of Hawaii in a diversified portfolio.
- If you prefer overlooked opportunities with solid fundamentals, you could widen your watchlist by scanning through 16 high quality undiscovered gems that may sit off the usual radar yet still meet your quality filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com