


HalowsLtd (TSE:2742) Stock Cheapens As Profit Holds And Margins Tighten
HalowsLtd stock has drifted lower in recent weeks, yet the latest quarter shows a retailer still grinding out earnings power. The headline is simple. Q2 2027 basic earnings per share landed at ¥101.08 on revenue of ¥59,390 million, while trailing 12 month profit now totals ¥9,037 million. The gap that matters is not between promise and story, but between that profit engine and a P/E of 9.3x that sits below both consumer retail peers and the broader Japan market. The market hesitated. The numbers show a business still quietly compounding.
Love the earnings power HalowsLtd is still putting up but wondering if that sub-market P/E signals opportunity or risk instead of value? Benchmark it against our hand picked 18 high quality undervalued stocks to see how other profitable retailers with solid fundamentals line up.
Q2 2027 Earnings Summary
- Revenue, Q2 2027 vs. Q2 2026: ¥59,390 million vs. ¥59,046 million (close to flat, slightly higher)
- Net Income, Q2 2027 vs. Q2 2026: ¥2,158 million vs. ¥1,954 million (up about 10%)
- Basic EPS, Q2 2027 vs. Q2 2026: ¥101.08 vs. ¥91.54 (up about 10%)
- Net Profit Margin, Last 12 Months vs. Prior Year: 3.9% vs. 4.1% (slight compression)
Prefer clean charts instead of another block of dense financial text? Get a full visual read on HalowsLtd, including how the valuation compares with its recent earnings power, in the company report for HalowsLtd.
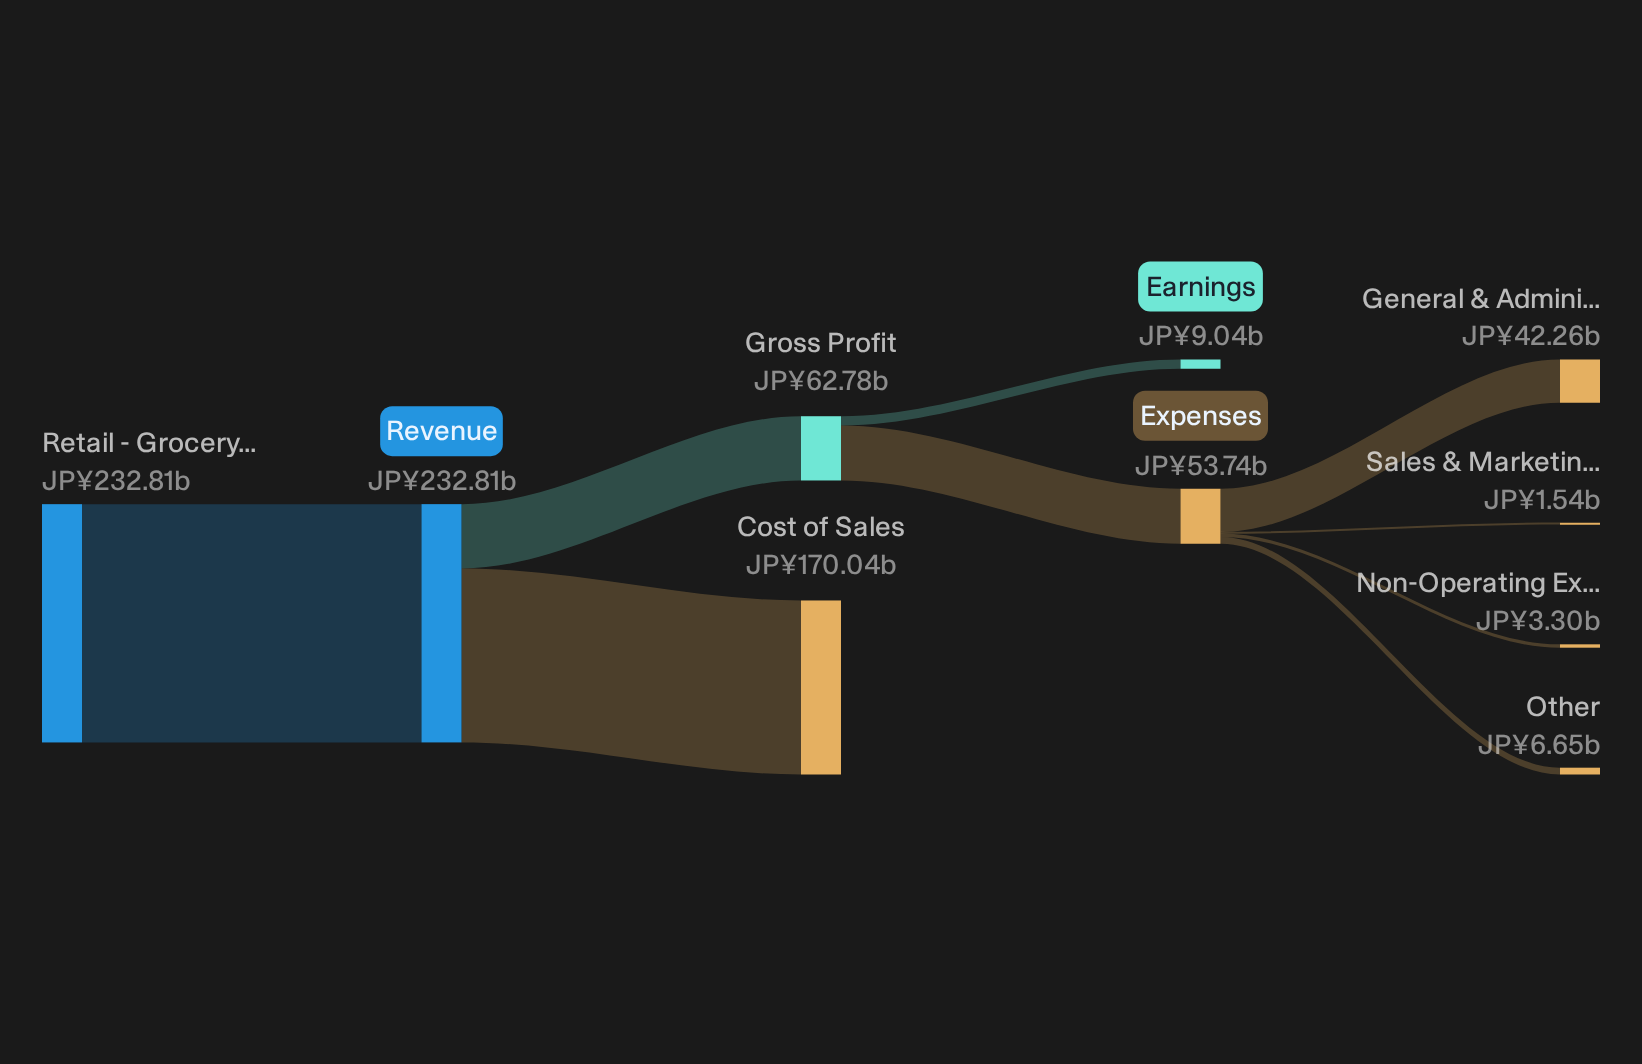
HalowsLtd earnings, backing the defensive story
HalowsLtd looks like the classic food retailer that keeps grinding. Revenue in Q2 2027 held close to prior year levels while net income and basic EPS both moved higher by about 10%. That points to better earnings efficiency rather than volume-driven growth. Trailing net profit of ¥9,037 million with a 3.9% margin also fits the picture of a steady, lower margin supermarket model. For investors leaning on the defensive, essentials-based narrative, these numbers broadly line up with a stable, cash-generating grocery chain.
Margin squeeze and slow top line test the downside
There is still a bear story here. Net profit margin edged down from 4.1% to 3.9%, which hints at cost pressure in an already tight supermarket structure. Revenue only nudged higher year on year, so earnings progress leaned on efficiency rather than clear demand growth. Recent share performance adds to that cautious read, with the stock down over the past week and month even though the 90 day return is positive. For a low margin retailer, that combination keeps competitive and cost risks very real.
After a quarter where HalowsLtd leans on efficiency gains while margins compress and the share price drifts, it is fair to ask whether cost pressure, cash conversion and competitive intensity are early warning signs or just short term noise. Scan the independent risk analysis for HalowsLtd which shows 2 important warning signs to see if this margin wobble masks deeper structural risks already flagged in the risk scorecard.Take Control Of Your Edge
If HalowsLtd's earnings power and sub market P/E have you interested but cautious, register free with Simply Wall St and add it to your Watchlist so you can track the share price against fair value and wait for a setup that matches your plan. Once you own it or any other holding, use the Portfolio Command Center to cut through noise and focus on the key valuation shifts, fundamental changes and alerts that matter most to your returns. For a longer view, lean on the Community to see how other investors are interpreting the same numbers, catalysts and risks. That mix of tools can help you identify potential pressure points or upside triggers early and stay a step ahead of the wider market.
Seeking Alternatives Beyond HalowsLtd?
Fresh ideas tend to move first when breakouts start appearing and momentum shifts before the crowd even notices. Scan under the radar for now, while it matters, and aim to get in early.
- Spot cash rich businesses before momentum stories fully catch on by running the list of solid balance sheet and fundamentals stocks (22 results) and filtering for durability while others chase headlines.
- Hunt for stronger income plays while yields are still holding up by checking the curated 14 dividend fortresses before these payouts may be fully reflected in prices.
- Track where the AI build out really needs hardware and infrastructure by using the focused 87 AI infrastructure stocks while the theme continues to surface new potential leaders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com