


How Investors May Respond To Granite Construction Stock Joining Silicon Valley Program
- Granite Construction announced that it joined Plug and Play Tech Center's Real Estate & Construction program in Silicon Valley, gaining access to a global network of startups and technology providers focused on how infrastructure is planned, built, and maintained.
- The move gives Granite Construction a structured way to test new construction technology with potential to influence project execution, cost control, and long-term cash generation, rather than leaving experimentation to ad hoc pilots.
- This article examines how Granite Construction's investment narrative around technology adoption and margin quality could be reshaped by its Plug and Play partnership.
Scan beyond Granite Construction and spot other infrastructure players leaning into construction tech with our curated 40 power grid technology and infrastructure stocks for this theme.
Granite Construction Investment Narrative Recap
To own Granite Construction, you need to believe its core contracting and materials franchises can turn a large, publicly funded project pipeline into steadier free cash flow over time. The near term focus is still on converting record infrastructure demand and recent acquisitions into cleaner margins, without losing pricing discipline on bids or overcommitting balance sheet capacity.
The biggest swing factor remains project execution quality, especially on complex, long duration jobs where cost inflation or delays can erode profitability. High debt and reliance on external borrowing raise the risk if cash conversion disappoints. The Plug and Play move is directionally helpful on operations, but it is not a near term catalyst by itself.
The Plug and Play Real Estate & Construction program announcement is a clear link to Granite Construction’s margin and cash flow story. Access to construction technology and process tools could support better estimating, scheduling, and materials usage, which matters for a contractor that is currently unprofitable and working to improve earnings quality.
For shareholders, the central question is execution. Can management translate this ecosystem access into fewer project surprises, better materials integration, and more consistent free cash generation while carrying meaningful debt? If the partnership contributes to tighter cost control and risk management on new work, it could reinforce existing catalysts tied to backlog and vertical integration.
Granite Construction's current analyst story points to revenues of $6.3b and earnings of $434.8m by 2029, based on expected yearly revenue growth of 10.8%. That path assumes earnings move from $185.0m today to $434.8m, an increase of about $249.8m.
Uncover why Granite Construction's fair value indicates a 45% potential upside to its current price. This gap could close faster than expected.
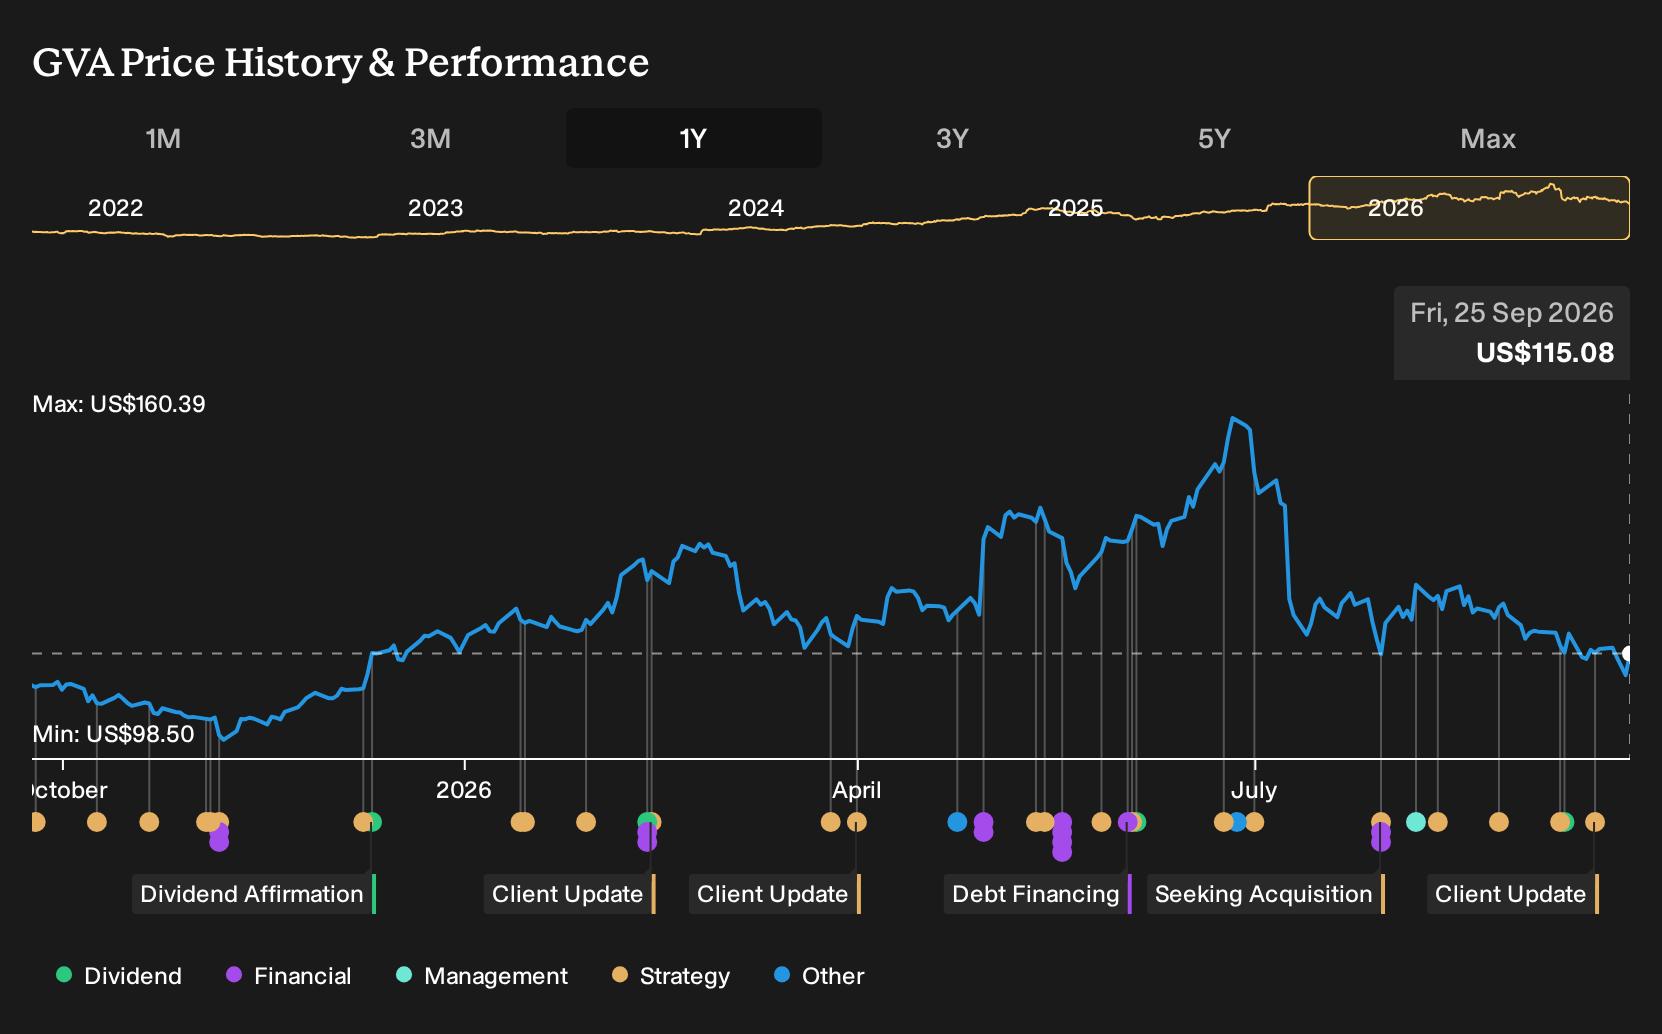
Exploring Other Perspectives
Some of the most optimistic analysts already saw Granite Construction as a technology and efficiency story, not just an infrastructure beneficiary. Before this Plug and Play news, they were modeling around $6.4b of revenue and $539.3m of earnings by 2029. You can read that as a much punchier margin narrative that might shift again as this partnership plays out.
Explore 3 other Granite Construction fair value estimates, including one that suggests as much as 74% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns do not typically come from following the herd, so go with your instincts.
- A great starting point for your Granite Construction research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Granite Construction. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Granite Construction's overall financial health at a glance.
Looking for more ideas beyond Granite Construction?
Granite Construction may be your starting point, but the next compelling opportunity could be sitting in a very different corner of the market. Use the Simply Wall St Screener to quickly filter for stocks that better fit your risk appetite, income needs, or quality preferences.
- If you want to focus on quality and valuation, start with a curated set of companies screened for strong fundamentals and attractive pricing using our 32 high quality undervalued stocks.
- For investors who care most about resilient balance sheets and financial strength, filter for companies with robust funding profiles through the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for under-the-radar stories, cast a wider net with a curated 16 high quality undiscovered gems that surfaces smaller businesses with strong underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com