


Aramark (ARMK) Lands AI Data Center Housing Deal On Undervalued Narrative
Aramark (ARMK) just landed a new hospitality contract tied to an AI data center workforce housing project in Texas, putting its Nexus unit deeper into large scale infrastructure and specialized labor projects.
Recent trading has been choppy, with the share price up 1.1% on the day to $54.92 but down 7.7% over 30 days and 2% over 90 days. Aramark still carries a 50.1% year to date share price return and a 126.7% three year total shareholder return that point to longer term momentum behind the stock.
Scan for other companies building exposure to AI infrastructure and specialized workforce housing by running the hand picked 87 AI infrastructure stocks alongside Aramark in your research.
Aramark is riding a strong multi year run, even as the share price has cooled in recent weeks. For investors eyeing this AI linked contract, the question is whether it is worth stepping in now or waiting for a cleaner entry before the valuation workup.
Most Popular Narrative: 19% Undervalued
Against a last close of $54.92, the most followed narrative pegs Aramark's fair value at about $67.97, which implies a clear valuation gap that hinges on how durable recent contract wins and earnings trends prove to be.
Significant investments in technology and AI for dynamic menu planning, supply chain efficiency, and contract management are driving measurable margin expansion, with AOI increasing 60 bps year-over-year, and expected to continue boosting net margins and profitability over time.
See why 3 investors see Aramark as 19% undervalued.
Result: Fair Value of $67.97 (UNDERVALUED)
Still, rising labor expenses and heavy exposure to education and sports contracts mean that Aramark's thin margins could come under pressure if costs or client budgets shift.
Find out about the key risks to this Aramark narrative.
Another View: Aramark Looks Expensive On Earnings
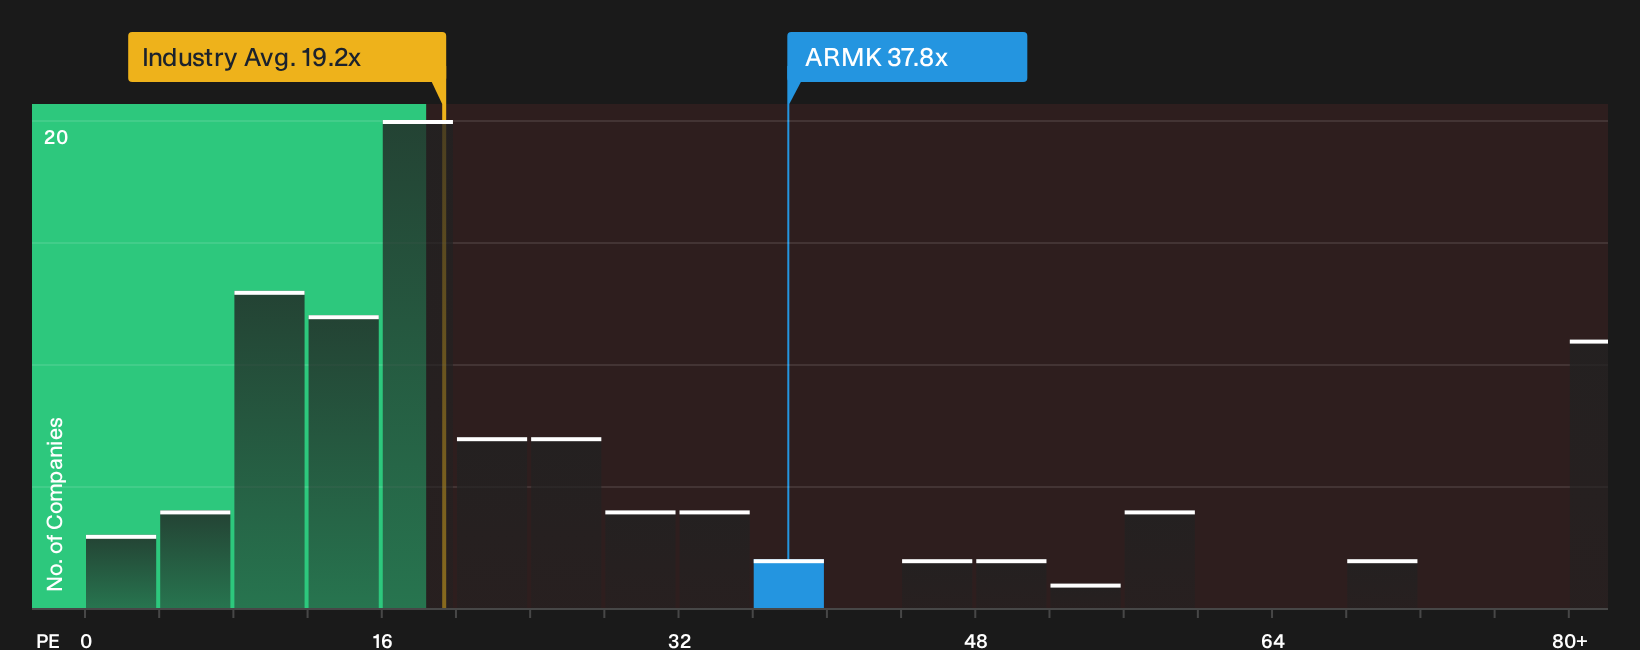
On the flip side of the underpriced fair value story, Aramark screens as pricey on a simple P/E check. The stock trades at 37.8x earnings compared with 19.9x for the US Hospitality sector, 18.7x for peers, and a fair ratio of 27.6x that the market could migrate toward over time. That premium points to valuation risk if high growth expectations fade. How much runway do you think is left in this multiple?
For a closer look at how this pricing stacks up against fundamentals, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty in this Aramark story pulls in different directions, so move fast, review the underlying numbers yourself, then weigh the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Aramark?
If Aramark has your attention, do not stop here. Broader context from other opportunities can sharpen your judgment, balance your risk, and highlight what real value looks like.
- Target potential mispricing by scanning a focused basket of quality candidates through the 32 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for companies that carry robust finances using the list of solid balance sheet and fundamentals (24 results).
- Spot early stage opportunities with healthier foundations before they move onto everyone else's radar by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com