


Eversource Energy (ES) Slides 10% In A Month, Is It A Bargain?
Eversource Energy (ES) has come under the spotlight after its share price fell about 10% over the past month, prompting fresh questions about the utility stock’s valuation and income appeal.
For Eversource Energy, the recent slide has come on top of a broader soft patch, with the share price down 11.2% over 30 days and 13.4% over 90 days, even as the latest close sits at US$63.67. That near term weakness contrasts with a much healthier 3-year total shareholder return of 25.8%, which suggests momentum has faded recently while longer term holders have still seen positive overall outcomes.
Scan the wider utilities space for other resilient grid and infrastructure plays by reviewing our curated list of 40 power grid technology and infrastructure stocks that are already on investor radars.
So is Eversource Energy’s recent slide telling you something new about the utility’s fundamentals, or has sentiment simply swung too far and opened up a potential valuation gap?
Most Popular Narrative: 14% Undervalued
Against the last close of $63.67, the most followed narrative for Eversource Energy points to a fair value of about $74.08. This frames the recent pullback as a move that has taken the share price below that reference point while still leaving plenty of debate around the assumptions.
Rising electricity demand from the rapid electrification of transportation and heating is expected to drive consistent long-term load growth for Eversource, directly supporting sustained revenue increases as regulatory-approved investments expand the company's rate base.
Accelerated infrastructure investments in grid modernization, including advanced metering, battery storage, and substation upgrades, are positioned to improve operational reliability and efficiency, leading to lower O&M costs and potentially boosting net margins over time.
See why 18 investors see Eversource Energy as 14% undervalued.
Result: Fair Value of $74.08 (UNDERVALUED)
Still, that story can easily change if Connecticut regulation tightens further or if planned moves, such as the Aquarion sale or storm cost securitization, stall.
Find out about the key risks to this Eversource Energy narrative.
Another View: Eversource Energy Through A Cash Flow Lens
Valuation built on analyst price targets paints one picture for Eversource Energy. The SWS DCF model tells a different story. On that framework, ES at $63.67 sits above an estimated future cash flow value of $58.79, which points to the stock trading at a premium instead of a discount.
That gap is not huge. Yet it flips the question for investors: Is the market already paying up for Eversource Energy's projected cash generation, or are the DCF inputs too cautious for a regulated utility with this earnings profile?
Look into how the SWS DCF model arrives at its fair value.
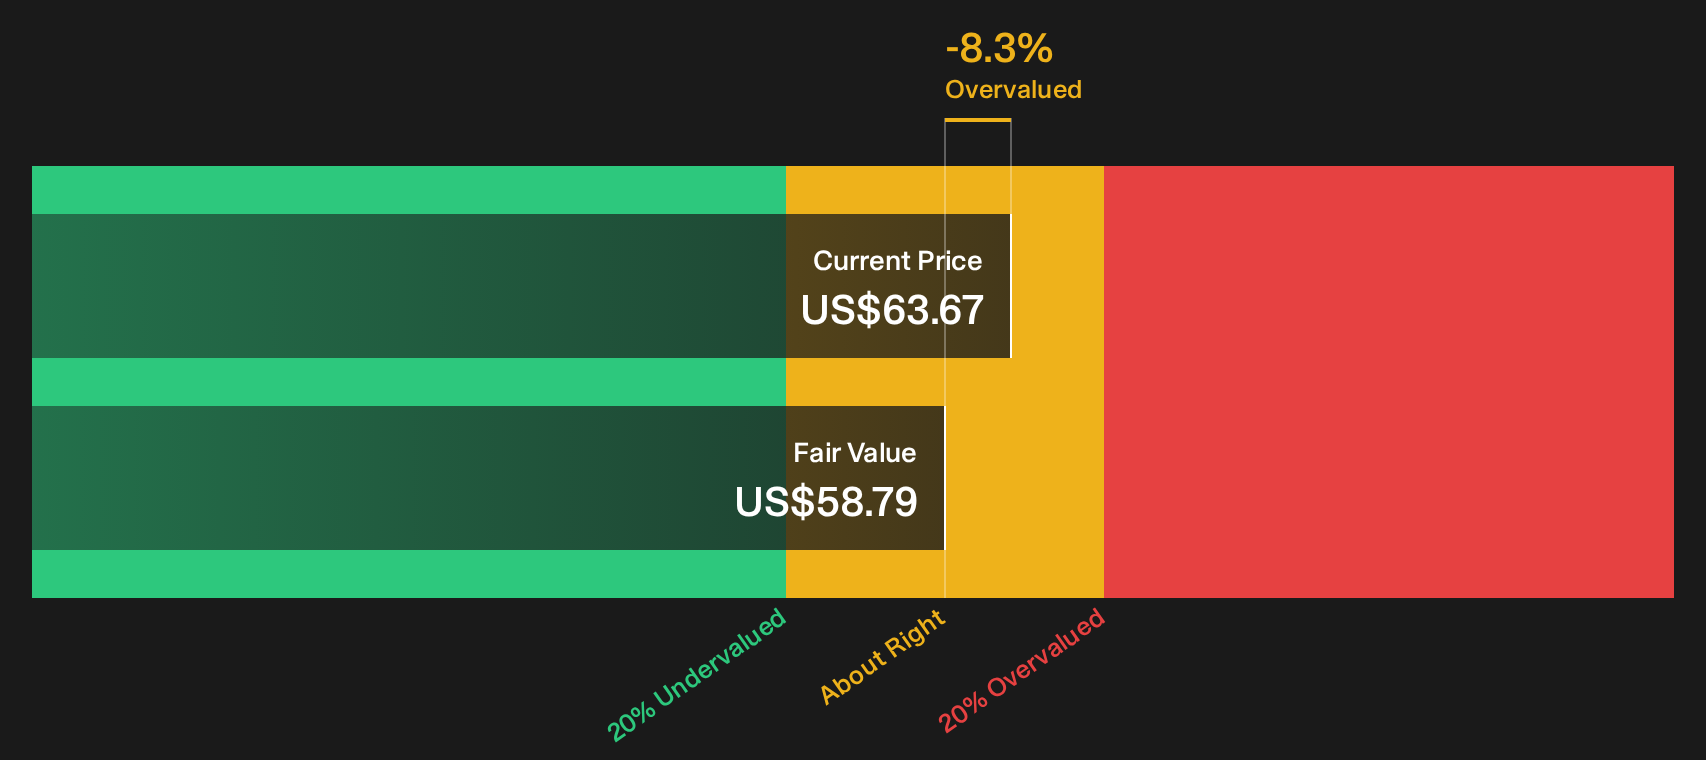
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Eversource Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Eversource Energy is clearly split right now. Consider acting promptly, review the data for yourself, and weigh both sides of the story with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Eversource Energy?
If Eversource Energy has your attention, broaden your watchlist with a few targeted stock ideas sourced from Simply Wall St screeners that surface different types of opportunities.
- Target resilience by focusing on companies with strong finances and low leverage using our list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by scanning a curated pool of potentially cheap quality businesses through the 32 high quality undervalued stocks.
- Prioritise stability by reviewing companies flagged as having relatively lower risk profiles via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com