


MONY Group And 2 British Dividend Stocks To Improve Your Portfolio
With the Bank of England tightening policy to keep inflation in check, cash in the bank feels safer but does little for long term income needs. Reliable UK dividend payers offering more than a 3% yield can help bridge that gap, especially when payouts look well covered and steadily rising. This article walks through three high income stocks from this quality filter that aim to deliver sturdier cash flow for a portfolio.
The three stocks below are just a starting sample from this idea, while the full screen surfaced 63 more companies with equally income focused stories that are not covered here. To go straight to the full Dividend Powerhouses list, analyze the yield quality, and identify your own highest conviction picks, head into the Dividend Powerhouses (3%+ Yield) screener.
MONY Group (LSE:MONY)
MONY Group runs price comparison and money saving platforms like MoneySuperMarket, MoneySavingExpert and Quidco that funnel regular traffic into insurers and banks, generating recurring lead fees and advertising income that help support its high yield dividend profile.
MONY Group earns most of its £448.1 million revenue in the UK from Insurance comparison at £236.9 million, Money at £110.5 million, and Cashback at £49.3 million, with smaller contributions from Home Services at £54.8 million, and has a market value of about £908 million.
What really matters for income focused investors is how this digital engine turns everyday price comparison habits into recurring cash flow that can support a covered, growing payout over time.
"The ongoing investment in digital and AI-enabled platforms is increasing automation and operational efficiency, evidenced by a 300% improvement in tech productivity and cost reductions from replatforming, which is likely to support sustainable long-term expansion of net margins."
Dividend strength will increasingly hinge on how one unseen pressure around funding costs and leverage resolves in the next few years.
If that funding question is what you are weighing, the full narrative for MONY Group shows how MONY Group’s cash engine, balance sheet and payout ambitions line up.

Lloyds Banking Group (LSE:LLOY)
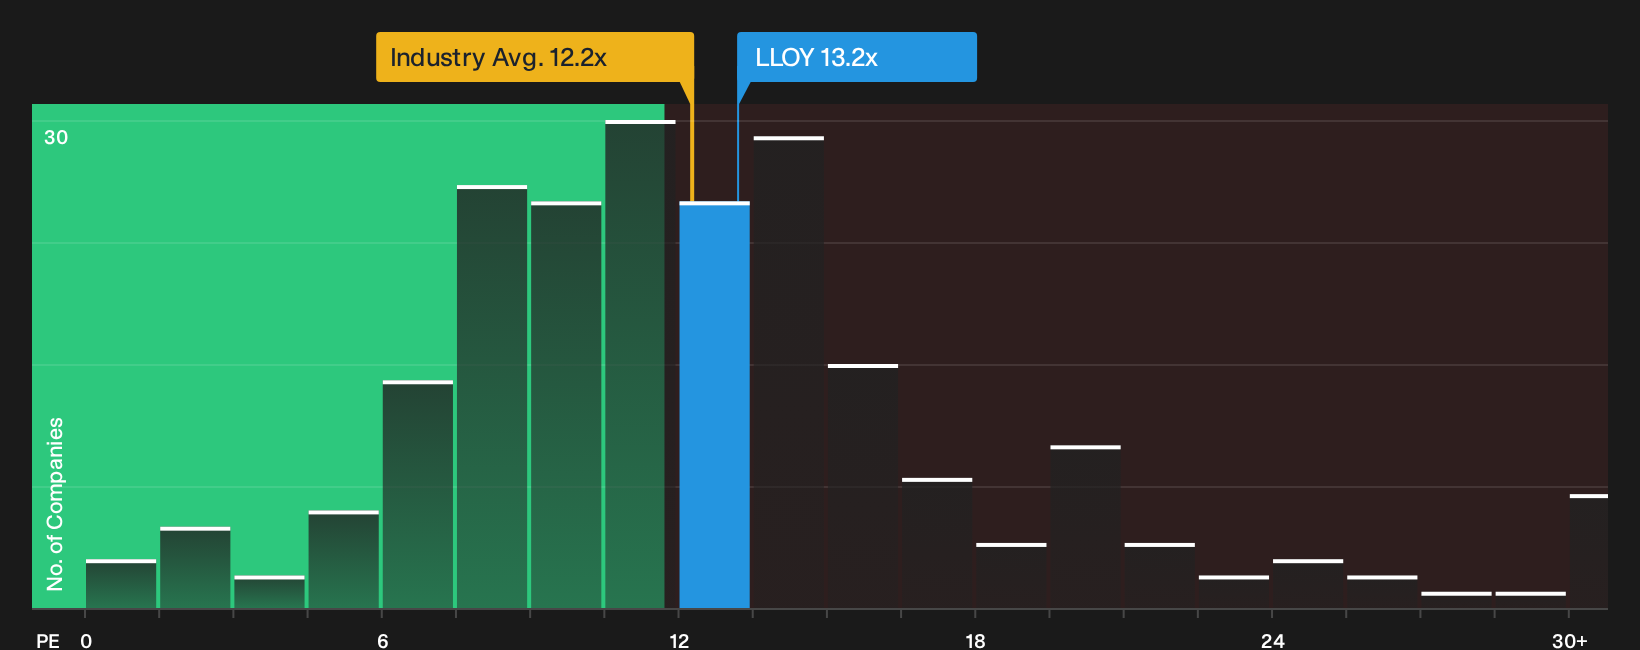
Lloyds Banking Group is a UK focused lender and financial services group whose regular cash dividends are closely tied to earnings from its Retail and Commercial Banking arms, with most of its £20.7b revenue coming from Retail at about £11.9b and Commercial Banking at £5.7b, and a market value around £62.6b.
Lloyds Banking Group taps into the Dividend Powerhouses theme by using its broad high street presence to turn everyday banking, mortgages and business lending into the kind of recurring earnings investors often associate with a 3%+ payout.
"Digital transformation and AI adoption are associated with reduced costs and greater efficiency, which may support margin expansion and changes in earnings quality."
A key consideration will be how any future shift in its capital returns mix shapes the balance between income today and the trajectory of those earnings over time.
That trade off between income and growth is exactly what the full narrative for Lloyds Banking Group unpacks, as it shows where Lloyds Banking Group may be quietly accelerating or stalling beneath the headline numbers.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is an infrastructure and private equity manager whose income focused real assets business links neatly to the 3%+ dividend theme, with most revenue from Real Assets at £114.8 million and Private Equity at £50.1 million, and a market value of about £476 million.
Income investors looking at Foresight Group Holdings are really asking whether a specialist in renewable and infrastructure funds can keep turning asset-backed cash flows into a dependable, growing payout without taking on equity-like volatility in the process.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
Where that story gets most interesting is in how one unresolved pressure around funding costs and leverage shapes the trade off between growth and dividend resilience.
That funding trade off is where the full narrative for Foresight Group Holdings digs in, revealing how Foresight Group Holdings could turn today’s constraints into income potential that may accelerate for patient holders.

Curious About What You Might Be Missing?
Fresh ideas move first. While the market chases yesterday’s winners, quiet breakouts and new momentum plays stay under the radar for now. Scan them before the crowd and act now.
- Spot resilient balance sheets backing real earnings power. Then run your own filter across the curated list of solid balance sheet and fundamentals (10 results) before the strongest stories get fully priced.
- Catch early-stage miners before sentiment changes, using the hand picked 36 elite gold producer stocks to track producers while information still feels one step ahead.
- Track robotics demand before orders hit headlines. Scan the curated 93 robotics and automation stocks while valuations still reflect hesitation rather than full on momentum buying.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com