


Rayonier (RYN) Could Be 27% Undervalued As Share Weakness Tests Its Story
Rayonier (RYN) has been drawing attention after recent share performance data showed declines over the past week, month and past 3 months, prompting investors to reassess what the timberland focused REIT offers today.
Over the past year, Rayonier has moved from a period of relative stability into a weaker stretch, with the share price down 12.63% year to date and total shareholder return declining 20.40% over the last 12 months. This points to fading momentum as investors reassess both growth prospects and risk around the current US$18.88 level.
Scan beyond Rayonier's recent share declines and compare this timber REIT with a hand picked 32 high quality undervalued stocks that also combines cash flow strength with more conservative pricing.
Rayonier's slide has raised a simple but important issue. Are investors reacting to real pressure in the timber and land business, or has sentiment moved faster than the underlying value? The valuation work now needs to test this.
Most Popular Narrative: 27% Undervalued
The most followed Rayonier narrative puts fair value at $26, which sits well above the recent $18.88 close and frames the current weakness as a valuation gap that needs explaining.
The development and sale of high-value real estate in the U.S. South, particularly through large master-planned communities like Wildlight and Heartwood, is capitalizing on population growth and migration trends; continued robust demand and a substantial unsold acreage pipeline support expectations for steadily increasing earnings and margin enhancement.
See why 22 investors see Rayonier as 27% undervalued.
Result: Fair Value of $26 (UNDERVALUED)
Still, the Rayonier story can break if severe weather hits Southern timber assets hard, or if weaker pulpwood demand keeps pressuring harvest volumes and pricing.
Find out about the key risks to this Rayonier narrative.
Another View On Rayonier’s Valuation
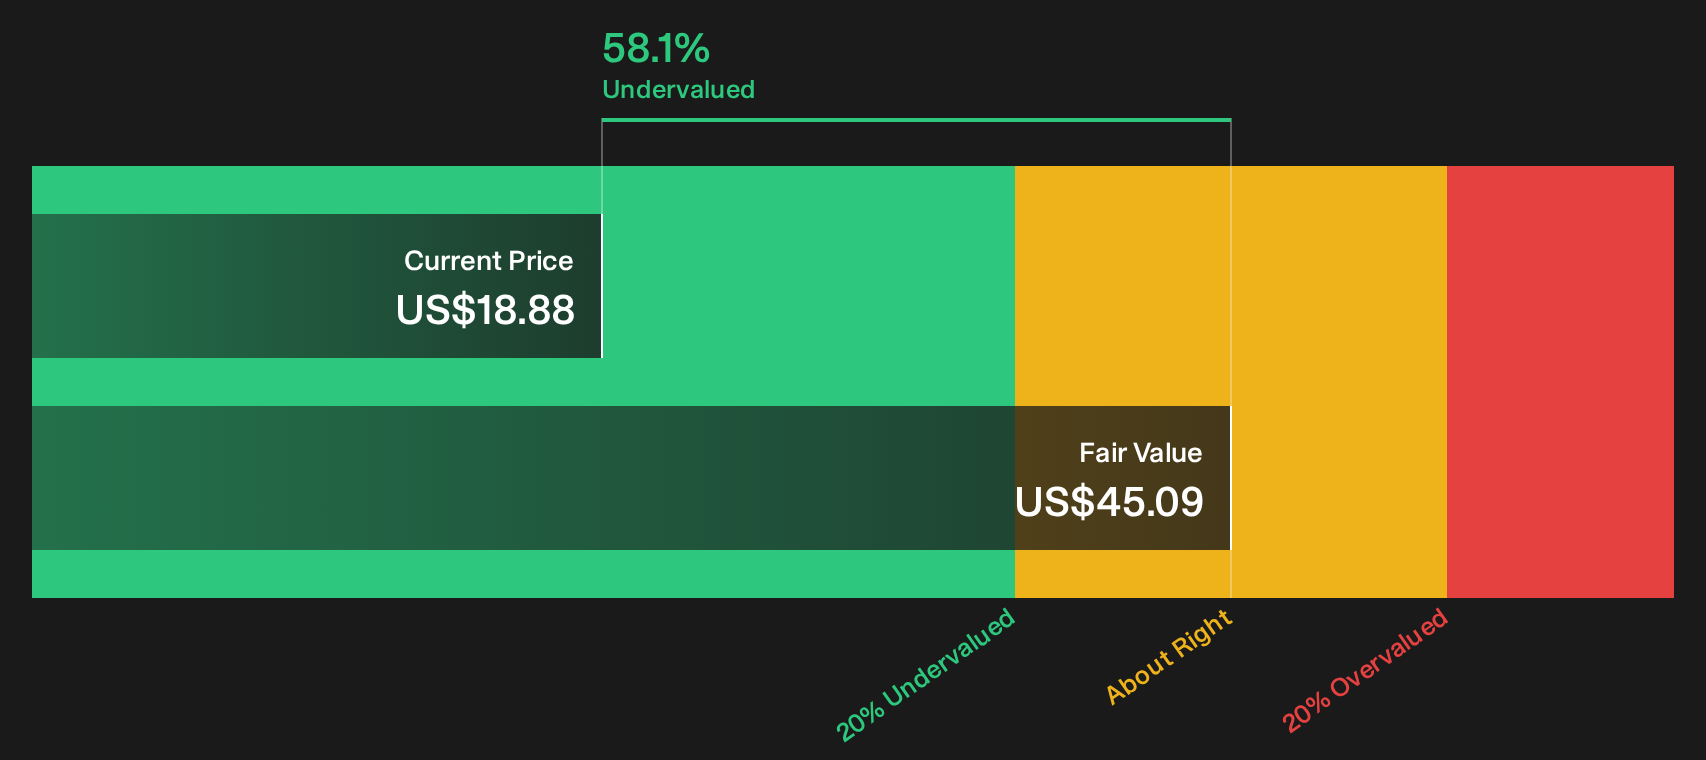
Rayonier screens as undervalued on future cash flows, with the Simply Wall St DCF model putting fair value at $45.09 versus a $18.88 share price, a 58.1% gap. That is a very different message to a weak share chart. Which signal do you trust more: the cash flow math or recent sentiment?
Our DCF model is only as strong as the assumptions that sit underneath it, so it is worth understanding exactly how that fair value has been built up before leaning on it too heavily in your own work. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Rayonier is clearly split, which is exactly when doing your own homework matters most. Move quickly, review both sides of the story and weigh the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Rayonier?
If Rayonier has sharpened your focus on value and risk, broaden your watchlist with a few targeted screens that surface different types of opportunities.
- Target potential upside by scanning a 16 high quality undiscovered gems that often fly under the radar but still show solid fundamentals.
- Protect your downside by filtering for 30 resilient stocks with low risk scores that score well on financial strength and business stability.
- Strengthen your core holdings by building around a list of solid balance sheet and fundamentals (24 results) that can better handle tough conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com