


Why Howard Hughes Holdings Stock Is In Focus After Ackman Backing
- Howard Hughes Holdings plans its 2026 annual shareholder meeting for September 30 in New York City, with leadership outlining progress on shifting toward a diversified holding structure and increasing emphasis on insurance through Vantage while reducing capital intensity in its master planned communities business.
- The endorsement from major shareholder Bill Ackman and upcoming detail on reallocating capital toward insurance indicate a potential rebalancing of Howard Hughes Holdings’ earnings mix between real estate cash flows and insurance-related income.
- This analysis will examine how Howard Hughes Holdings' investment narrative is affected by Bill Ackman’s public backing and the holding company pivot.
Howard Hughes Holdings Investment Narrative Recap
To own Howard Hughes Holdings, you need to be comfortable with a real estate developer that is gradually turning into a broader holding company built around insurance. The short-term story still hinges on healthy cash generation from master planned communities and operating assets, while management reallocates capital toward Vantage and away from more capital-heavy projects.
The biggest near-term swing factor is execution on this pivot without letting the existing communities or recurring NOI lose momentum. The main operational risk is simple: a complex shift into insurance, on top of a sizeable debt load that is not well covered by operating cash flow, leaves less room for missteps if the transition is slower or more expensive than planned.
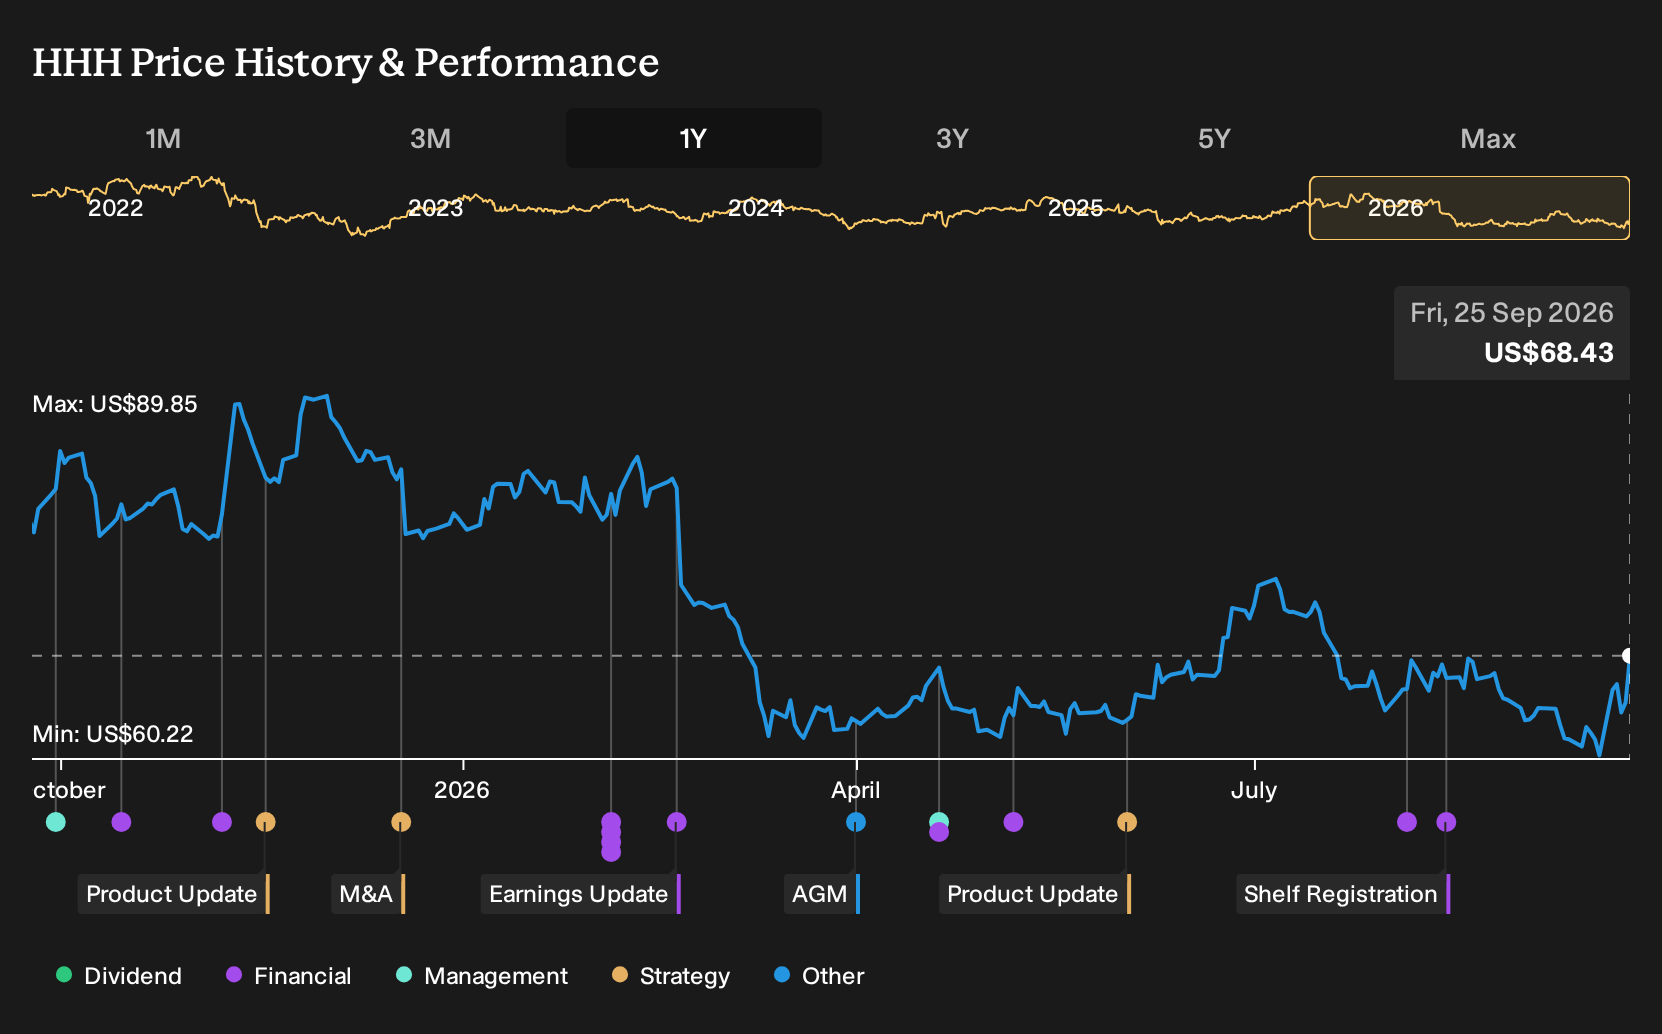
The upcoming 2026 shareholder meeting is the clearest reference point right now. Howard Hughes Holdings has indicated that Bill Ackman and David O’Reilly will lay out more detail on how the group reduces capital intensity in real estate and leans further into Vantage. That is where investors are likely to look for concrete execution milestones, rather than just high-level messaging.
This event also arrives after a year in which the stock has trailed the broader US market, even with an 8.9% move higher following Ackman’s endorsement. For you as a shareholder, the key question is whether the meeting provides enough operational clarity on insurance integration, debt management and future capital allocation to offset concerns around concentrated real estate exposure and a relatively low current and forecast return on equity.
Howard Hughes Holdings' current analyst narrative points to US$1.6b in revenue and US$353.6 million in earnings by 2029, based on a 2.7% yearly revenue growth rate and a move from US$121.6 million in earnings today to that 2029 consensus, which implies earnings roughly tripling over the period.
Discover how Howard Hughes Holdings' fair value indicates a 32% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community cluster between about US$89.67 and US$139.98, with some members seeing Howard Hughes Holdings as deeply undervalued before the recent Ackman-backed pivot gained attention. You should weigh those pre-event views against execution risk around insurance integration and debt, and then explore several contrasting community opinions for balance.
Explore 5 other Howard Hughes Holdings fair value estimates, including one that suggests it could be worth just $89.67!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Howard Hughes Holdings research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Howard Hughes Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Howard Hughes Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Howard Hughes Holdings?
If the Howard Hughes Holdings story has sharpened your thinking about risk, balance sheets and long-term compounding, it can be useful to line it up against a broader watchlist of potential opportunities using the Simply Wall St Screener.
- For investors who care most about resilient balance sheets and fundamentals, review a curated list of solid balance sheet and fundamentals (24 results) that might offer a different risk profile to Howard Hughes Holdings.
- If steady income is your priority, scan a handpicked 8 dividend fortresses that could complement a more growth-focused holding like Howard Hughes Holdings.
- Those hunting for mispriced potential can compare Howard Hughes Holdings with a focused 16 high quality undiscovered gems that the market may not be fully paying attention to yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com